When comparing medical expense insurance, you should carefully examine your usual hospital usage habits and the generation of your coverage rather than simply looking for the cheapest product. As national healthcare costs have risen significantly and household financial burdens have increased, the wisdom of choosing the right coverage for your specific needs has become more important than ever. Many people regret enrolling in a policy based solely on friends’ recommendations, only to find out later that they are not receiving the expected benefits when they actually visit the hospital. In particular, given the rising trend in non-covered medical expenses, it is essential to accurately understand the pros and cons of each generation of medical expense insurance. In this article, we will explore easy-to-follow criteria for comparing medical expense insurance and specific tips for wisely reducing premiums. We will explain complex insurance terms and clauses in an easy-to-understand manner, so please read through to the end carefully.
=
Essential Tips for Comparing Medical Expense Insurance and How to Reduce Premiums
1. Understanding the Evolution and Differences of Medical Expense Insurance by Generation
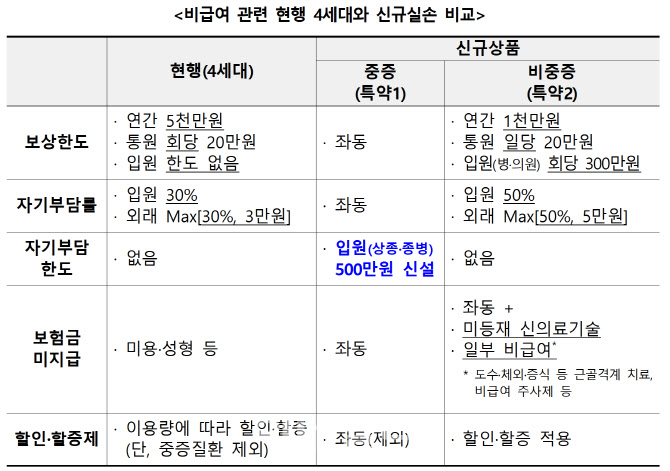
Medical expense insurance shows significant differences in structure and out-of-pocket cost ratios from the 1st generation (purchased in the past) to the 4th generation (currently on sale). 1st and 2nd generation products have very low or no out-of-pocket costs, which alleviates concerns about hospital bills, but the burden can increase over time due to soaring renewal premiums. On the other hand, the recently introduced 4th generation medical expense insurance is designed to offer premium discounts to policyholders who rarely visit the hospital, while applying surcharges for those who frequently receive non-covered treatments. Therefore, rather than simply keeping an old product because it is assumed to be better, you should coldly evaluate your health status and financial situation to consider switching. In fact, there is a growing trend of office workers decisively switching to the latest products to reduce their fixed monthly expenses. Since there are subtle differences in underwriting criteria and discount conditions among insurance companies, it is essential to compare multiple products side by side. According to the National Health Insurance Service, healthcare expenditure is reaching new highs every year, and private insurance accounts for a significant portion of this spending. Understanding this macro trend of rising healthcare costs will broaden your perspective when choosing the right insurance for you. When considering switching generations, you must weigh not only the immediate premium savings but also the risk of hospital costs that may arise as you age.
You can choose the most advantageous product for you by understanding the differences in out-of-pocket costs and renewal cycles across generations of medical expense insurance.
2. The Balloon Effect of Non-Covered Medical Expenses and Countermeasures
Recently, the frequency of medical expense insurance claims has surged as many people receive non-covered musculoskeletal treatments such as physical therapy and extracorporeal shock wave therapy. Non-covered items, which are not subject to National Health Insurance, have varying prices at different hospitals, making them a primary cause of increased overall healthcare burdens. In fact, it is not uncommon to see cases where people casually undergo expensive non-covered injection treatments and later regret it when they face a “renewal bomb” (a sudden spike in premiums). To prevent this, you must develop the habit of carefully checking whether the treatments you frequently receive are fully covered by your medical expense insurance. Indiscriminate use of non-covered treatments ultimately leads to premium increases for all policyholders, so a wise attitude of utilizing only necessary treatments is required. The latest insurance companies are rapidly expanding systems that use artificial intelligence to automatically review simple claims within 24 hours. Thanks to technological advancements, you can easily claim insurance benefits through smartphone apps without the hassle of preparing complex documents. However, just as claims have become more convenient, a balanced perspective is needed to ensure that unnecessary claims do not increase. Properly understanding and addressing the characteristics of non-covered items is the shortcut to saving on insurance premiums in the long run.
You can prevent a premium shock by understanding the characteristics of rapidly increasing non-covered medical expenses and reducing unnecessary claims.
3. How to Use Insurance Comparison Sites Tailored to Your Conditions
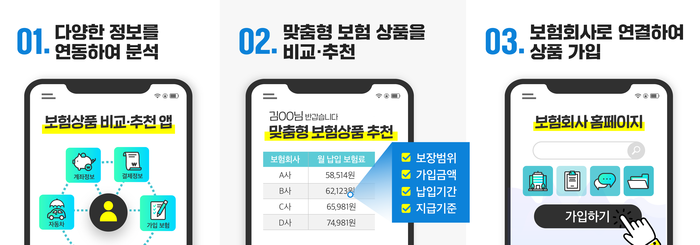
Using comparison sites that aggregate products from multiple insurance companies at a glance can be a great help in saving hidden costs. However, rather than blindly chasing the cheapest options, you should carefully examine whether the necessary riders are properly included for your age group and gender. For example, people in their 20s and 50s have completely different types of common illnesses and hospital visit frequencies, so they should not choose the same product. It is essential to enter identical conditions such as age and occupation on a comparison site, then display quotes from multiple companies side by side to compare the differences. In fact, Mr. Kim, an office worker, felt his monthly premiums were a waste and compared coverage details across several comparison sites, eventually removing unnecessary riders. As a result, he managed to lower his premiums to a much more reasonable level while maintaining core coverage. Just like this, even with the same coverage, the monthly amount varies depending on each company’s risk calculation method, making comparison an essential process rather than an option. The most reliable way to save money is to make an effort to compare directly based on objective indicators rather than relying solely on a specific agent’s advice.
You can find the most reasonable product that fits your budget by comparing quotes from multiple companies under identical conditions.
4. Checkpoints to Always Verify When Selecting Riders
When enrolling in other products such as comprehensive insurance or cancer insurance alongside medical expense insurance, you must carefully check for duplicate coverage. Since medical expense insurance reimburses the actual hospital bills you pay, enrolling in multiple policies does not increase the actual coverage amount. On the other hand, lump-sum benefits like cancer diagnosis fees or cerebrovascular disease diagnosis fees can be advantageous if you have multiple policies, so they should be separated according to their purpose. This principle should also be applied when looking into senior insurance for parents or children’s insurance for kids to prevent unnecessary expenses. Occasionally, I see cases where people enroll in comprehensive package products recommended by agents, only to find that they overlap with coverage they already have, wasting money every month. Before signing a contract, you must accurately analyze your existing coverage by policy and only fill in the gaps with essential additions. In particular, familiarizing yourself in advance with exclusion periods and reasons for claim denial can prevent difficulties when claiming insurance benefits later. A meticulous attitude of examining even the fine print in the terms and conditions serves as a shield protecting your and your family’s valuable assets.
You can prevent unnecessary expenses by checking for duplicate coverage and selecting only the riders you truly need.
5. Convenience and Precautions for Insurance Claims
These days, you can simply take a photo of your hospital receipt using a mobile device and upload it, and the insurance money will be deposited into your bank account within minutes. The hassle of carrying piles of paper documents to a counter or mailing them, as was common in the past, has disappeared, making daily life much more convenient. For small amounts, the process is simple with just the medical receipt and detailed itemized statement, which is highly appreciated by busy office workers. For insurance companies that have introduced AI-based automatic review systems, the waiting time for review has been significantly reduced, leading to higher satisfaction. However, just as the claiming process has become more convenient, delays in review due to minor document omissions or entry errors still occur occasionally. It is a good habit to double-check on your smartphone screen whether the patient’s resident registration number or treatment code is accurately recorded on the documents issued by the hospital. Also, since there is a statute of limitations for claiming from the insurance company within a certain period from the date of payment, you should apply promptly without delaying. It is advantageous to familiarize yourself with how to use the smartphone app in advance to avoid missing out on valuable insurance benefits due to minor negligence.
While actively utilizing the convenient mobile claiming system, you must carefully check for document omissions and claim deadlines.
6. Final Recommendations for Wise Maintenance of Medical Expense Insurance
Since the burden of national healthcare costs is likely to continue increasing, medical expense insurance will continue to serve as a reliable safety net in our lives. Rather than hastily canceling a contract just because the premium feels burdensome, you should re-examine which generation and conditions are most suitable for you right now. Instead of reacting emotionally to the rising renewal amounts each year, the best tip for saving is to manage your health well to reduce the frequency of hospital visits. Referring to objective advice from experts and wisely utilizing various comparison platforms will be a great help to your household economy. Please calmly review your bank statements to see if money is being wasted on unnecessary riders at this very moment. Small interests and comparison habits can collectively protect our family’s wallets from a future hospital bill shock. Based on what you have learned today, I hope you will coldly compare various products around you and complete your own customized plan. I sincerely hope you will continue to become a wise financial consumer in the changing healthcare environment.
You should wisely overcome household healthcare cost risks through consistent monitoring and smart management from a long-term perspective.
Frequently Asked Questions
=