NH Investment & Securities announced that it maintains its Buy recommendation on KCC, raising its target price from 680,000 won to 730,000 won, driven by expectations of a full-scale rollout of shareholder returns. Recent corporate value enhancement plans have outlined specific strategies for utilizing the company’s stake in Samsung C&T, drawing significant market attention. Analysts widely view this move as a pivotal turning point for the company’s valuation. Many shareholders are closely monitoring securities firm reactions, hoping that long-standing undervaluation factors will be resolved. Against this backdrop, interest in the company’s overall financial health and future profitability outlook has naturally increased. This article examines KCC’s changes in shareholder return policies and the potential for performance improvement in its silicone division from multiple perspectives.
=
Target Price Raised on Expectations for KCC Shareholder Returns via Samsung C&T Stake Utilization
1. Utilization of Samsung C&T Stake and Special Dividend
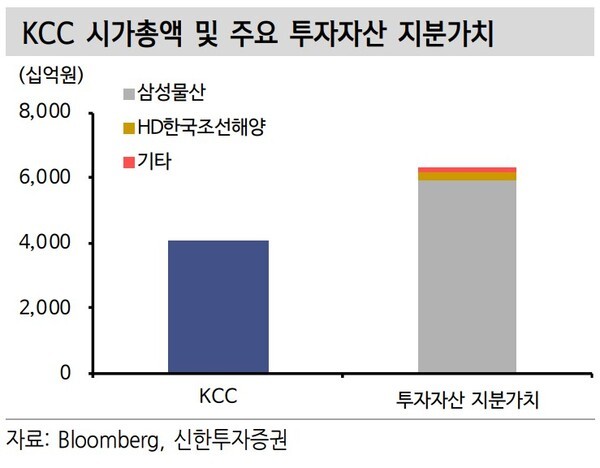
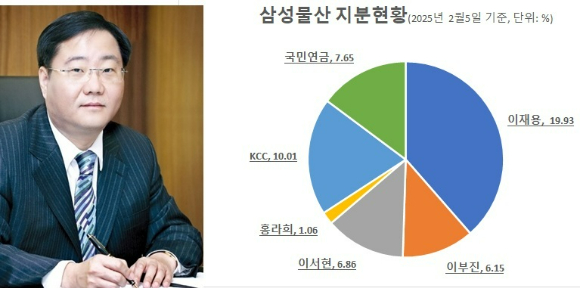
Through its corporate value enhancement plan, KCC has clearly stated its policy to actively utilize its held stake in Samsung C&T. The company currently holds approximately 17.01 million shares of Samsung C&T, representing a substantial 10.49% of the total issued shares. With the recently decided special dividend from Samsung C&T, KCC has secured a significant dividend fund of up to 220 billion won. Investors are increasingly expecting this cash inflow to lead to expanded dividends or investments in new businesses. Experts interpret this not merely as dividend receipt but as a signal of actively returning the value of held assets to shareholders. In capital markets, asset efficiency is considered one of the most powerful drivers of stock price appreciation. This aligns with the trend of large conglomerate affiliates shifting from conservative capital management to aggressive shareholder policies. Therefore, this move is likely to serve as a signal for long-term corporate structural improvement rather than a one-off event. Market valuation is expected to become more favorable depending on how this massive asset is allocated and utilized in the future.
Secured 220 billion won in dividend funds via Samsung C&T’s special dividend, laying the foundation for shareholder returns.
2. Large-Scale Share Buyback and Cancellation Plan
The announcement of a large-scale cancellation of treasury shares is also acting as a key factor positively impacting the stock price. KCC plans to cancel 77% of its held treasury shares by September of next year, in accordance with its announced buyback plan. This means that a massive amount of shares, equivalent to 13% of the total issued shares, will be completely removed from the market. As the number of shares decreases, earnings per share (EPS) naturally rise, directly enhancing shareholder value. Generally, large-scale share cancellations are the most definitive measure of a company’s commitment to supporting its stock price and protecting shareholder rights. This highlights management’s will to move away from management centered on a few major shareholders and share profits with general shareholders. Many market participants hope that this bold shareholder return policy will serve as a model for resolving the chronic undervaluation problem in the domestic stock market. Indeed, immediately after the announcement, securities firms have collectively raised target prices and released positive reports. It is now a time to carefully monitor the cancellation schedule through September of next year to formulate investment strategies.
Plans to cancel 77% of treasury shares, equivalent to 13% of total issued shares, by September of next year.
3. Credit Rating Upgrade and Potential Additional Stake Sales
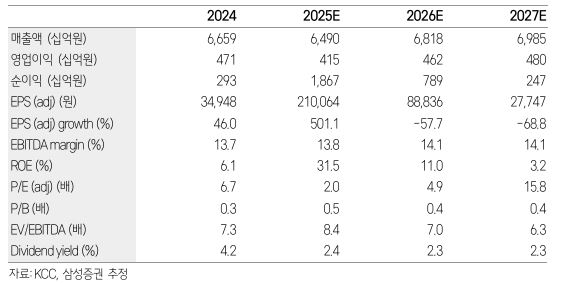
While the utilization of the Samsung C&T stake has settled on receiving a special dividend for now, additional possibilities remain open. The securities industry does not rule out the scenario where the company may sell remaining shares to raise its overseas credit rating by one notch. Maintaining an excellent credit rating is essential to lower borrowing costs and strengthen the financial structure in the global market. If additional stake sales materialize, a large-scale cash inflow of several trillion won could enable unprecedented shareholder returns that exceed investors’ imaginations. The expectation itself that hidden asset value can be returned to shareholders at any time provides strong downside support for the stock price. This is precisely why, when analyzing a company, one must consider not only current operating profits but also the potential for monetizing held assets. Companies like KCC, which hold abundant high-quality assets, possess the potential to trigger significant stock price surges depending on market conditions. Investors must meticulously monitor the detailed plans disclosed by the company and management’s statements without missing any detail.
The possibility of additional stake sales aimed at upgrading the overseas credit rating remains open.
4. Structural Profit Rebound in the Silicone Division
In addition to asset value, the core silicone division is also entering a period of structural profit rebound, further adding to its investment appeal. The company has significantly reduced the revenue share of low-priced products that previously burdened performance and restructured its portfolio to focus on high-margin product lines. Combined with the full reflection of proactive product price increases in its results, profitability is rapidly recovering. It is assessed that KCC’s market dominance is actually becoming more solid as the global chemical industry’s supply chain is restructured. Specifically, major events such as Dow’s closure of its UK plant and Elkem’s sale of its silicone business division are resolving industry-wide oversupply. Amid these external environmental changes, KCC is fully benefiting as a competitive manufacturer. Professional institutions forecast that the operating profit margin of the silicone division will clearly improve to around 5% in the second half of this year. As the profitability of the core business expands, combined with the added value of asset sales and dividends, the stability of performance has significantly increased.
By reducing low-priced products and expanding high-margin products, the silicone division’s operating profit margin is expected to improve to around 5%.
5. Global Supply Chain Restructuring and Spillover Benefits
The global silicone market is undergoing massive landscape changes due to consecutive structural adjustments by major competitors. As European plants close due to environmental regulations and cost burdens, supply shortages are gradually emerging. Amid this global supply-demand imbalance, KCC’s position to stably supply high-quality products has become more solid. The company, which has gained an advantage in price negotiation power, has succeeded in defending its margin rates and strengthening its performance resilience. In the stock market, cyclical stocks tend to show the steepest upward curves when the industry cycle bottoms out and turns around. Since the silicone industry is entering exactly this recovery phase, the current stock price level is still considered attractive. The speed of operating profit improvement may be faster than market expectations, driven by cost reduction efforts and price increases. Long-term investors who understand the characteristics of the chemical industry prefer strategies that increase accumulation during such industry turnaround periods.
A favorable supply chain environment has been created by plant closures and business division sales by global competitors.
6. Target Price Raised to 730,000 Won and Investment Strategy
Reflecting these complex positive factors, NH Investment & Securities raised KCC’s target price from 680,000 won to 730,000 won. This is because two powerful engines—materialized shareholder return policies and the return to profitability in the core business—have started operating simultaneously. Investors should check whether the roadmap presented by the company is being executed without delay, rather than reacting emotionally to short-term stock price fluctuations. It is advisable to keep in mind the treasury share cancellation schedule through September of next year and the timing of the special dividend payment. In conclusion, KCC is evolving into a model company that breaks the mold of traditional manufacturing and actively practices shareholder value enhancement. If a virtuous cycle of returning the value of held assets to shareholders is established, the stock price will leap to a higher level. Investors seeking both stability and growth in their portfolios are recommended to closely examine this opportunity. We hope you will make wise investment decisions by regularly checking related disclosures and securities firm reports.
Target price raised to 730,000 won based on the full-scale rollout of shareholder returns and core business improvement.
Frequently Asked Questions
=