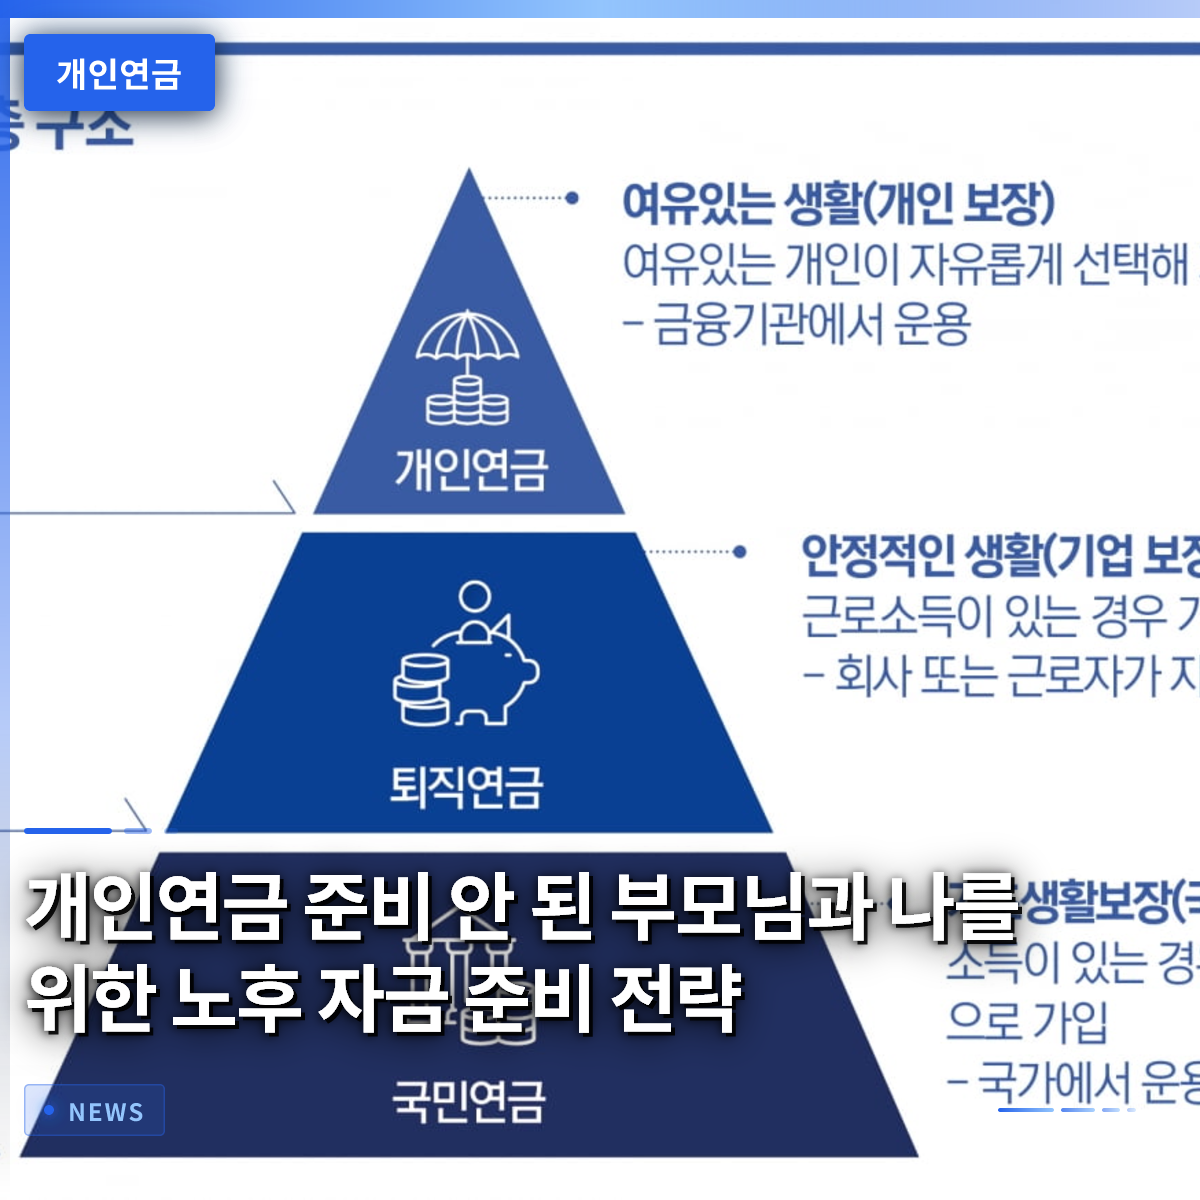
To secure a stable life after retirement, you must start preparing additional personal pension funds immediately rather than relying solely on the National Pension. It is easy to overlook retirement savings when burdened by student loans or housing costs in your younger years, but when retirement arrives, a much larger gap in living expenses than expected often emerges. In reality, many parents of the current generation, who spent their lives raising children and buying a home without preparing any personal pension, are facing significant difficulties due to insufficient living expenses after retirement. You should carefully check whether you have accumulated any retirement pensions from your employment or personal pension products you subscribed to in the past through the integrated inquiry website. Today, we will take a detailed look at why we need to start personal pension savings now to enjoy economic freedom after retirement, along with realistic examples.
=
Retirement Funding Strategy for Parents Who Haven’t Prepared Personal Pensions and for Myself
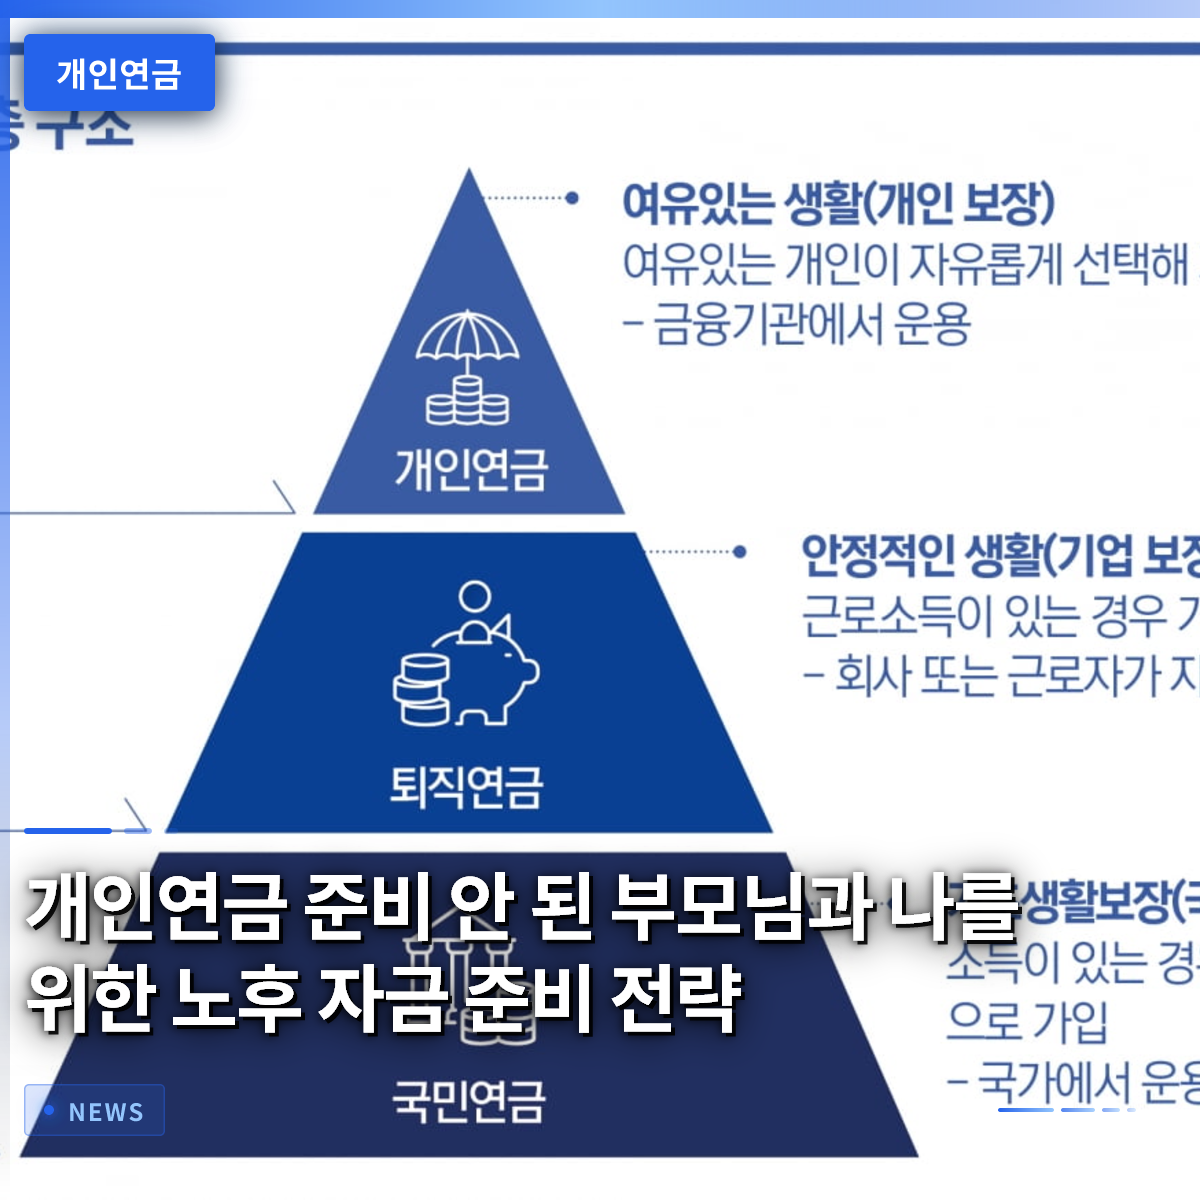
1. The Retirement Gap That Hits When You Rely Only on the National Pension

The per-household income statistics we commonly see differ significantly from the actual after-tax monthly salary or living expenses that individuals receive. Since this figure includes business income, property income, and government transfer payments, it often diverges from the living costs felt when shopping for groceries. When a gap occurs between quitting a job and the time when National Pension benefits begin, you may find it difficult to even cover immediate monthly food and management fees. In particular, as the eligibility age for National Pension benefits continues to be delayed, the income cliff between retirement and the start of pension payments is becoming deeper.
To safely get through this gap, personal assets accumulated directly by the individual are absolutely necessary, in addition to state-provided systems. The part that retired seniors around us regret the most is not having started pension savings in their younger days. Since it is not easy to reduce fixed monthly expenses, you will face significant difficulties if you do not create a cash flow in advance. Ultimately, a stable retirement life is only possible when personal savings built up by the individual are layered on top of the basic safety net provided by the National Pension.
It is difficult to fill the post-retirement income gap with the National Pension alone, so additional assets are needed.
2. The Retirement Scars Left by Student Loans and Housing Costs

Student loans taken on in one’s 20s and 30s do not end as just a heavy burden of youth; they become a boomerang that erodes retirement funds. If you cannot accumulate surplus funds because you are paying off loan principal and interest from the start of your career, you will miss the golden time to begin saving. When you scrape together every penny to take out a loan for a home and pay the interest, you often have no energy left to think about your own retirement.
If such financial obstacles are not overcome early, you may be shocked to face a much smaller retirement savings amount than others when you reach your 40s and 50s. In reality, compared to 20 years ago, the debt scale of individuals with assets has snowballed, and this is the biggest culprit hindering retirement preparation. Without a strategic financial plan that balances loan repayment and retirement preparation, you may end up working your whole life only to age with empty hands. Therefore, you must develop the habit of mandatorily depositing money into pension accounts from the very early stages of earning income to break this vicious cycle.
The burden of student loans and housing costs in one’s younger years is a major cause blocking retirement fund savings.
3. A Strategy for Starting Equity-Based Systematic Investment with Small Amounts

Many people delay joining a pension plan because they lack a large sum of money, but in fact, you can sufficiently prepare for the future even with very small amounts. Recently, securities firms offer very well-developed systematic investment services that automatically purchase index funds on a daily, weekly, or monthly basis. Since investors can steadily accumulate stocks according to set rules without directly monitoring complex market prices, this is perfect for busy office workers.
However, if you rashly join any product just because the yield looks attractive, you may suffer immense mental shock when the market fluctuates later. Since retirement funds are long-term investments looking decades ahead rather than money needed immediately, you must choose robust stocks that can withstand volatility. You must also make the effort to regularly check your portfolio returns and adjust them slightly according to market conditions. Consistent systematic investment becomes a powerful weapon that lowers the average purchase price without being shaken by short-term price fluctuations.
Using systematic investment possible with small amounts allows you to accumulate stable retirement assets in the long term.
4. The Hidden Secrets of Tax Benefits and Pension Income Tax
One of the biggest attractions of joining a personal pension product is the generous tax deduction benefit received during the year-end tax settlement. This is why office workers diligently deposit their hard-earned money into pension savings or retirement pension accounts to save even a little on their annual taxes. However, you must be aware that when you actually receive pension benefits after retirement, taxes are imposed differently depending on the amount received.
If the annual pension receipt exceeds a certain amount, it becomes subject to comprehensive income tax or falls into a bracket with a higher pension income tax rate. Surprisingly, many retirees regret having deposited large sums all at once to save on taxes, only to face a tax bomb when receiving the benefits. Therefore, you need the wisdom to spread the receipt period over a longer duration so that the monthly pension amount received after retirement does not exceed specific tax thresholds. You should seek help from a tax professional or study relevant financial knowledge yourself to design the optimal receipt method that minimizes taxes.
Just as important as securing the year-end tax deduction benefit is thoroughly managing the tax brackets at the time of receipt after retirement.
5. A Realistic Way to Secure Living Expenses for Parents and Myself
For families with parents who have spent their lives supporting their children and have no cash on hand other than their own home, it is worth actively considering a reverse mortgage (housing pension). This is a very useful system that allows you to receive a stable monthly living expense in the form of a pension from the state or financial institutions while continuing to live in your current home. This is an excellent alternative that allows parents to spend their retirement with dignity without placing an economic burden on their children.
At the same time, we, the younger generation, must use our parents’ missteps as a mirror and thoroughly manage our personal pensions from now on to break the vicious cycle. You should carefully use the integrated pension inquiry service to find any retirement funds accumulated from past jobs or insurance products you may have forgotten. A dual strategy where parents secure their current living expenses by utilizing their housing and we save even small amounts into pension accounts every month will protect our family. Retirement preparation is not a story from a far-off land or someone else’s business; it is a practical reality that requires us to open our bank accounts and check them starting today, just as we open the refrigerator.
For the entire family’s retirement to be peaceful, parents should utilize their housing and we should prepare personal pensions in advance.
6. Concrete Action Plans for a Successful Retirement
Start by turning on your smartphone or computer right now and checking the status of all pension assets registered in your name at a glance. You must gather all your National Pension, retirement pension, and past personal pension insurance to see your true retirement report card. A small action, such as reducing consumption by just 100,000 won from your monthly income and setting up an automatic transfer to a pension account, can change your destiny decades later.
In the future, AI-based personalized asset management tools will become more widespread, opening a world where anyone can easily check their retirement portfolio. No matter how good the technology becomes, if you do not practice saving money and consistently depositing it into your account, your account will always remain empty. From the moment you read this article, put into practice the pension account opening or additional deposits you have been postponing to complete a secure and happy retirement life yourself. The pension account built with your own hands will be the strongest and most reliable best friend for us as we age.
You must start with an integrated pension inquiry and practice consistent monthly savings to welcome a successful retirement.
Frequently Asked Questions
=