To qualify for income tax deductions, you must spend more than 25 percent of your total annual income on credit cards. Additionally, using installment payments for services like gym memberships is safer in case the business closes down. If you swipe your cards out of habit without counting how many you have in your wallet, you may soon find yourself facing an unmanageable bill. Hearing stories from others about receiving tax refunds of several million won at year-end can make you anxious about whether you are missing out on benefits. However, if you properly understand the basic principles and systems of card usage, you can reduce expenses while still getting good value. In this article, we will thoroughly examine common payment knowledge and hidden benefits that are easily overlooked in daily life. Learn the right way to manage your wallet and start a journey of smart consumption.
=
How to Use Credit Cards Wisely: Hidden Benefits and Income Tax Deduction Criteria
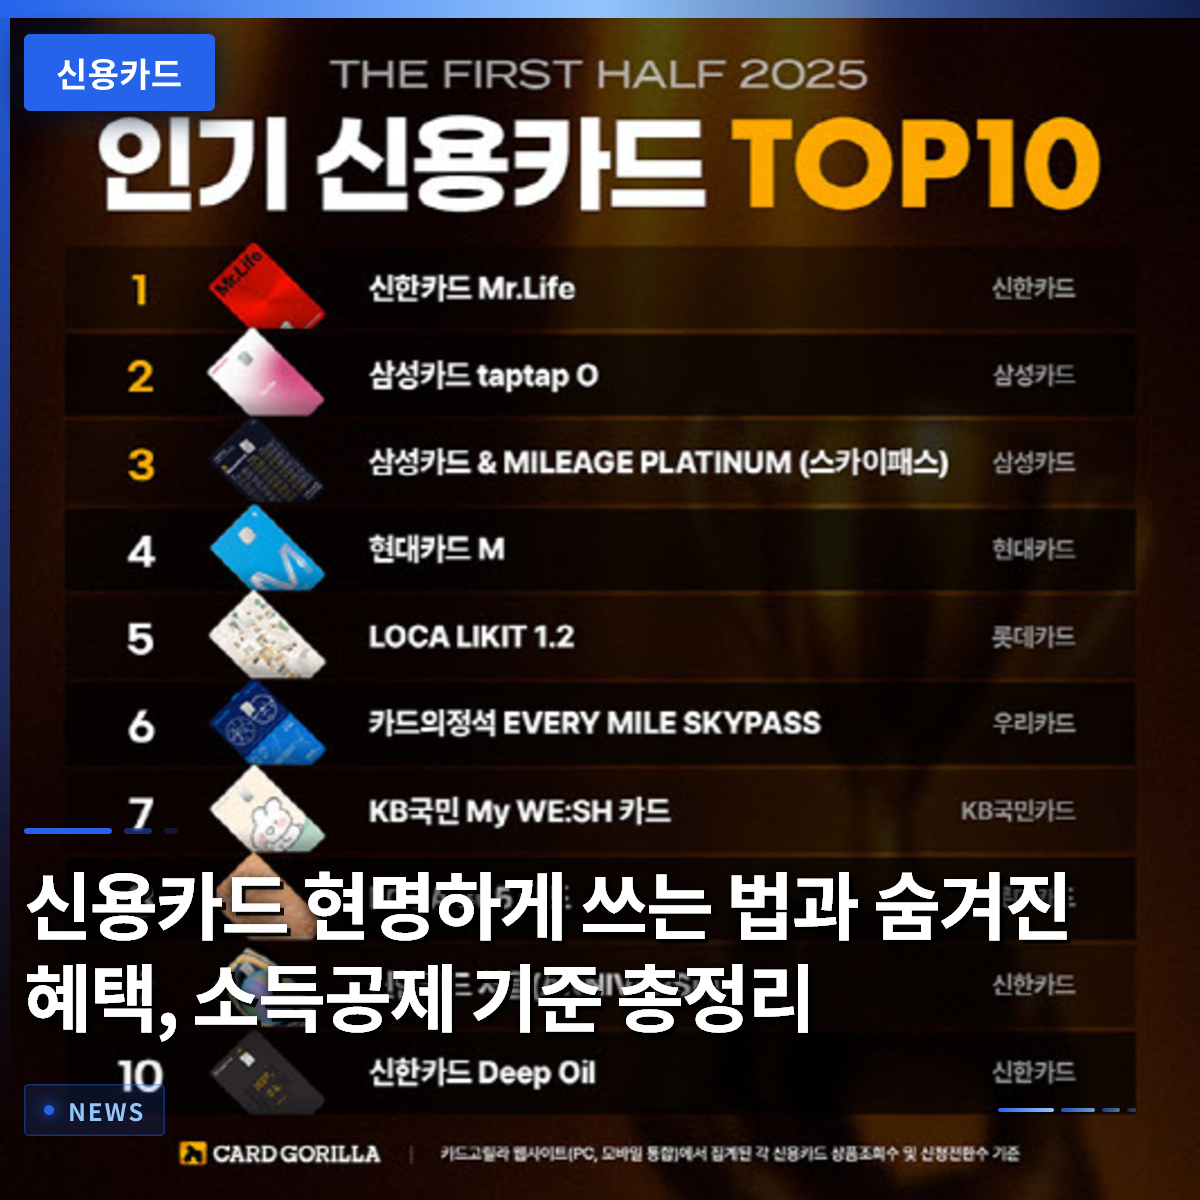
1. Year-End Tax Settlement Income Deduction Criteria

You can only receive the credit card income tax deduction benefit if your spending exceeds 25 percent of your total annual income. For an office worker with an annual salary of 40 million won, spending up to 10 million won using general payment methods will not qualify for any deduction. Tax benefits are applied at a favorable rate compared to check cards or cash receipts only after this threshold amount is exceeded. For example, a strategy is needed where you primarily use cards with large discounts from January to October, and then focus on using payment methods with high deduction rates once the threshold is met. Instead of just envying colleagues who brag about their year-end tax refund “bombs,” you should first check your own spending habits. If you do not carefully analyze your usual consumption patterns month by month, you are likely to face a tax burden or miss out on refund opportunities every year. To maximize income tax deduction benefits, you must develop the habit of periodically reviewing your spending plan set at the beginning of the year. It is much wiser to make strategic purchases aligned with year-end tax settlement calculations rather than simply trying to save money blindly.
You must exceed 25 percent of your total annual income to enter the income deduction bracket, so choosing the right payment method for each period is important.
2. The Hidden Safety Net of Installment Payments

It is essential to choose installment payments when purchasing long-term membership passes worth hundreds of thousands of won at places like gyms or swimming pools to ensure safety. If you pay for an amount of 200,000 won or more in installments over three months or longer, you can exercise your right of defense with the card company even if the business suddenly closes down or the owner disappears. There are many cases where consumers who were left stranded due to unresponsive businesses requested the card company to waive the remaining installment payments and received relief. If you pay in a lump sum and the establishment closes, it is difficult to get a cash refund, but using the installment system provides a minimal shield. When entering into service contracts that require a large amount of money, you should resist the temptation of lump-sum payments to prepare for unforeseen circumstances. It is not uncommon to see cases where people hesitate to pay high lesson fees in one go and end up suffering significant losses. If you want a safe consumption life, it is a wise measure to utilize installment transactions for offline services with long contract periods as much as possible. Small differences in choices can protect your valuable assets from potential financial losses that may occur later.
Installment transactions of 200,000 won or more over three months or longer are an excellent safety net that guarantees the right of defense in case of business closure.
3. Cleaning Up Dormant Cards and Annual Fee Refunds
It is advantageous to cancel cards that have been sitting unused in the corner of your wallet for months by making a single phone call before the annual fee is charged. Having many unused cards is not only disadvantageous from an asset management perspective but can also negatively impact your credit utilization ratio calculations. In reality, many people are happy to receive a pro-rated refund of the annual fee for the remaining period after calling the customer center to organize unnecessary cards. Using an integrated inquiry service that lists all financial products registered under your name can help you find plastic cards you don’t even remember having. Simply organizing unused accounts and cards can effectively stop money from leaking out every year. It also completely blocks the risk of cards being stolen or information being leaked, providing a two-fold benefit. Periodically checking and organizing unused financial assets is the most basic and easy step in the habits of the wealthy. You need the initiative to turn on your smartphone right now and check the list of cards in your name.
You should cancel unused cards before the annual fee is charged and receive a refund for the remaining amount, which is beneficial for credit management and expense defense.
4. How to Handle Card Loss Incidents
If you lose your entire wallet, do not panic; immediately contact the card company’s customer center to report the loss and request a usage suspension. If unauthorized transactions are found due to malicious use by someone else, you must immediately initiate the compensation application process to minimize the damage. There is a system in place that allows you to receive compensation for fraudulent use amounts incurred around the time of the loss report after a certain period of investigation. If you lose multiple cards at once, utilizing the bulk reporting service can save you significant time and effort. Be aware that if a family member or acquaintance borrows your card and uses it without permission, causing issues, it may be excluded from the compensation scope. Storing emergency financial contact numbers in your smartphone in advance allows you to respond quickly in crisis situations. Remember that a thorough sense of security and prompt reporting are the most powerful weapons to protect your assets. Since accidents can happen anytime and anywhere, it is safe to always maintain a prepared posture.
You must report a lost card immediately and go through the fraudulent use compensation process to prevent financial loss.
5. The Trap of Short-Term Loans and Revolving Credit
Just because you urgently need cash does not mean you should casually use credit card cash services, card loans, or revolving credit, as this can lead to serious trouble. At first glance, these systems seem convenient as they allow you to convert your remaining limit into cash immediately, but they are actually high-interest loans. Revolving credit fee rates often approach the legal maximum interest rate, so a moment of negligence can result in a snowballing interest bomb. Frequently using these short-term funding services can cause your personal credit score to drop sharply, leading to disadvantages when applying for a mortgage later. Even if people around you encourage you by saying it is easy and fast to borrow money, these are financial products you must absolutely avoid for the sake of your future creditworthiness. If you truly need emergency funds, it is much safer to look into bank emergency loans or other legitimate channels. You must never take lightly the scary price of high interest and credit score drops hidden behind convenience. Do not forget that it takes an enormous amount of time and effort to recover a credit score once it has collapsed.
Cash services and revolving credit are high-interest loans, so you should avoid them as much as possible to prevent a drop in your credit score.
6. Differences Between Corporate and Personal Cards
News reports are daily highlighting that corporate credit card usage has reached an all-time high as the performance of semiconductor companies recovers. Corporate-named payment instruments play a crucial role in enhancing corporate accounting transparency and systematically managing expense details. On the other hand, personal cards must be carefully selected and managed according to the individual’s strict consumption tendencies and asset management goals. The financial environment will become more complex in the future, with various benefits and risk factors coexisting. To survive in a changing system, you should first reflect on your own consumption habits rather than blindly chasing products just because others recommend them. Please apply the income tax deduction criteria, installment right of defense, and card organization tips learned today to your real life immediately. A wise financial consumer is not created overnight but is completed through the accumulation of small practices and attention. Take out the list of plastic cards in your wallet right now to check them and design a smarter consumption life.
Corporate cards are an indicator of corporate growth, while personal cards require strict expense management and benefit comparison.
Frequently Asked Questions
=