Individual Retirement Pension (IRP) accounts are the most reliable way to save for retirement while reducing your tax burden. Many employees rush to their accounts as the year-end tax settlement approaches to claim tax deduction benefits, but they often suffer losses due to a lack of understanding regarding the exact limits and precautions. For instance, confusing the annual contribution limit with the tax deduction limit can lead to over-contributing, resulting in a tax bomb when the funds are eventually withdrawn. In this article, we will explore practical methods to save on taxes using pension savings and IRPs, along with tips for wisely protecting your severance pay. By reading this content to the end, you will find the answers to retirement planning and tax-saving strategies that may have seemed complex.
=
Maximizing Tax Savings with IRP Retirement Pensions: A Complete Guide to Year-End Tax Deduction Limits
1. Tax Deduction Limits for Pension Savings and IRP

To increase your year-end tax refund, you must accurately understand the combined contribution limits for pension savings and Individual Retirement Pensions (IRP). You can receive tax deduction benefits on a combined annual maximum of 9 million KRW, with pension savings alone eligible for deductions up to 6 million KRW. For example, if you contribute 6 million KRW to pension savings and an additional 3 million KRW to an IRP, you will fully utilize the 9 million KRW limit and enjoy the maximum benefit. If your total annual income is 55 million KRW or less, a deduction rate of 16.5% applies, allowing you to receive a maximum refund of 1.485 million KRW. Conversely, if your total income exceeds this amount, a deduction rate of 13.2% applies, resulting in a refund of 1.188 million KRW. When calculating the contribution limit, it is based on the amount you actually contribute; severance pay deposited by your company is excluded from tax deduction eligibility. Mr. Kim, an office worker, calculates the shortfall each year and makes additional contributions to receive the maximum refund annually. Setting the optimal contribution amount according to your income level is the first step toward tax savings.
By combining Pension Savings and IRP contributions up to 9 million KRW annually, you can receive tax deduction benefits of up to 16.5%.
2. The Difference Between Lump-Sum and Pension Receipt of Severance Pay

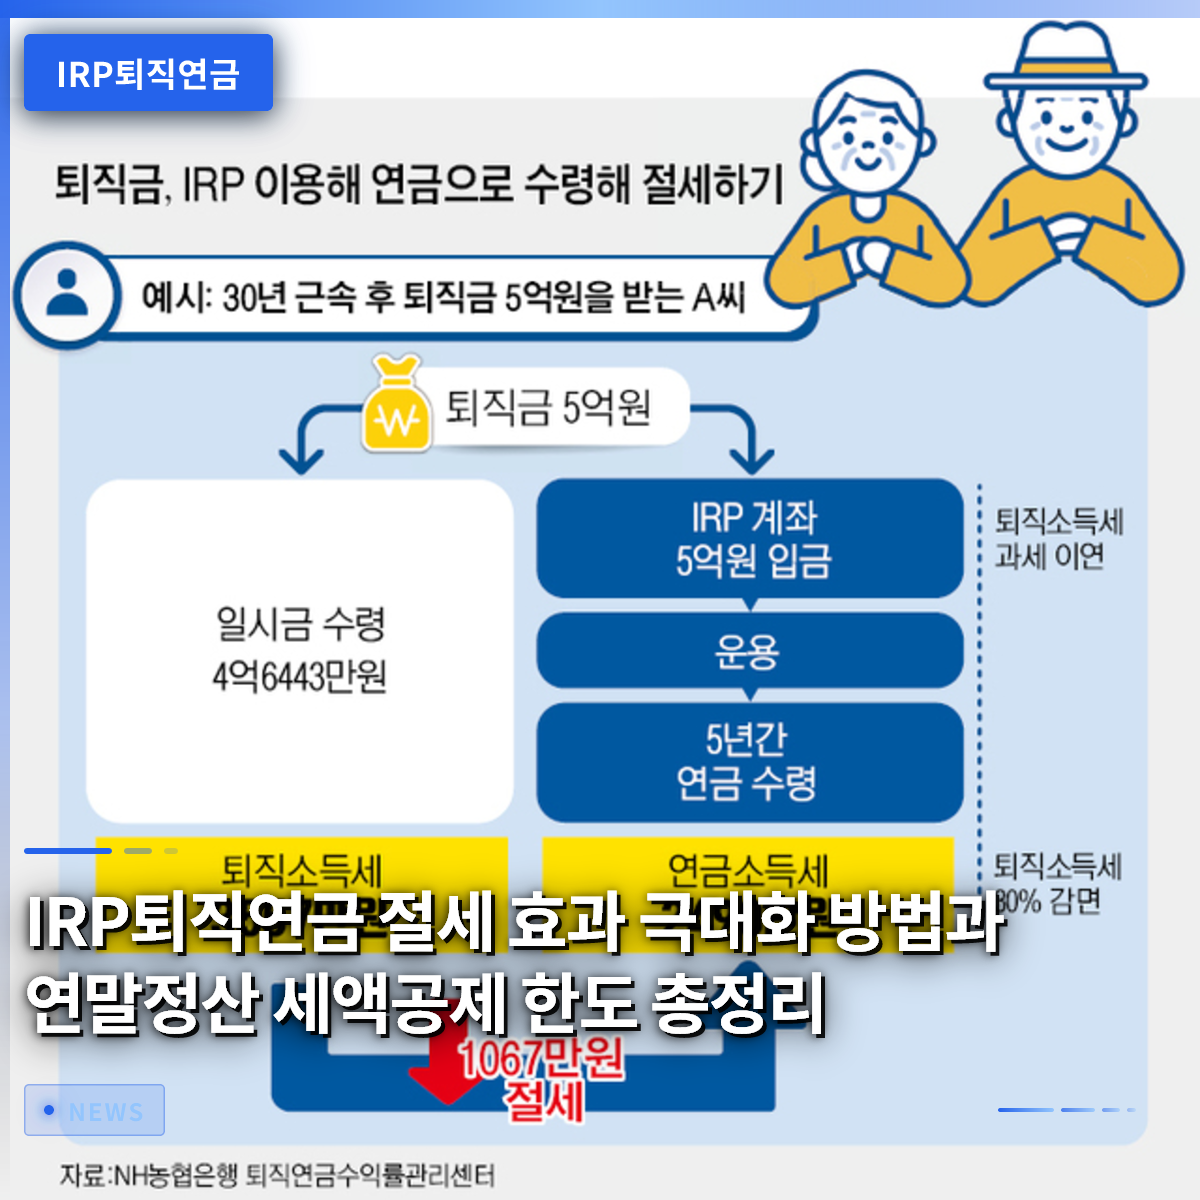
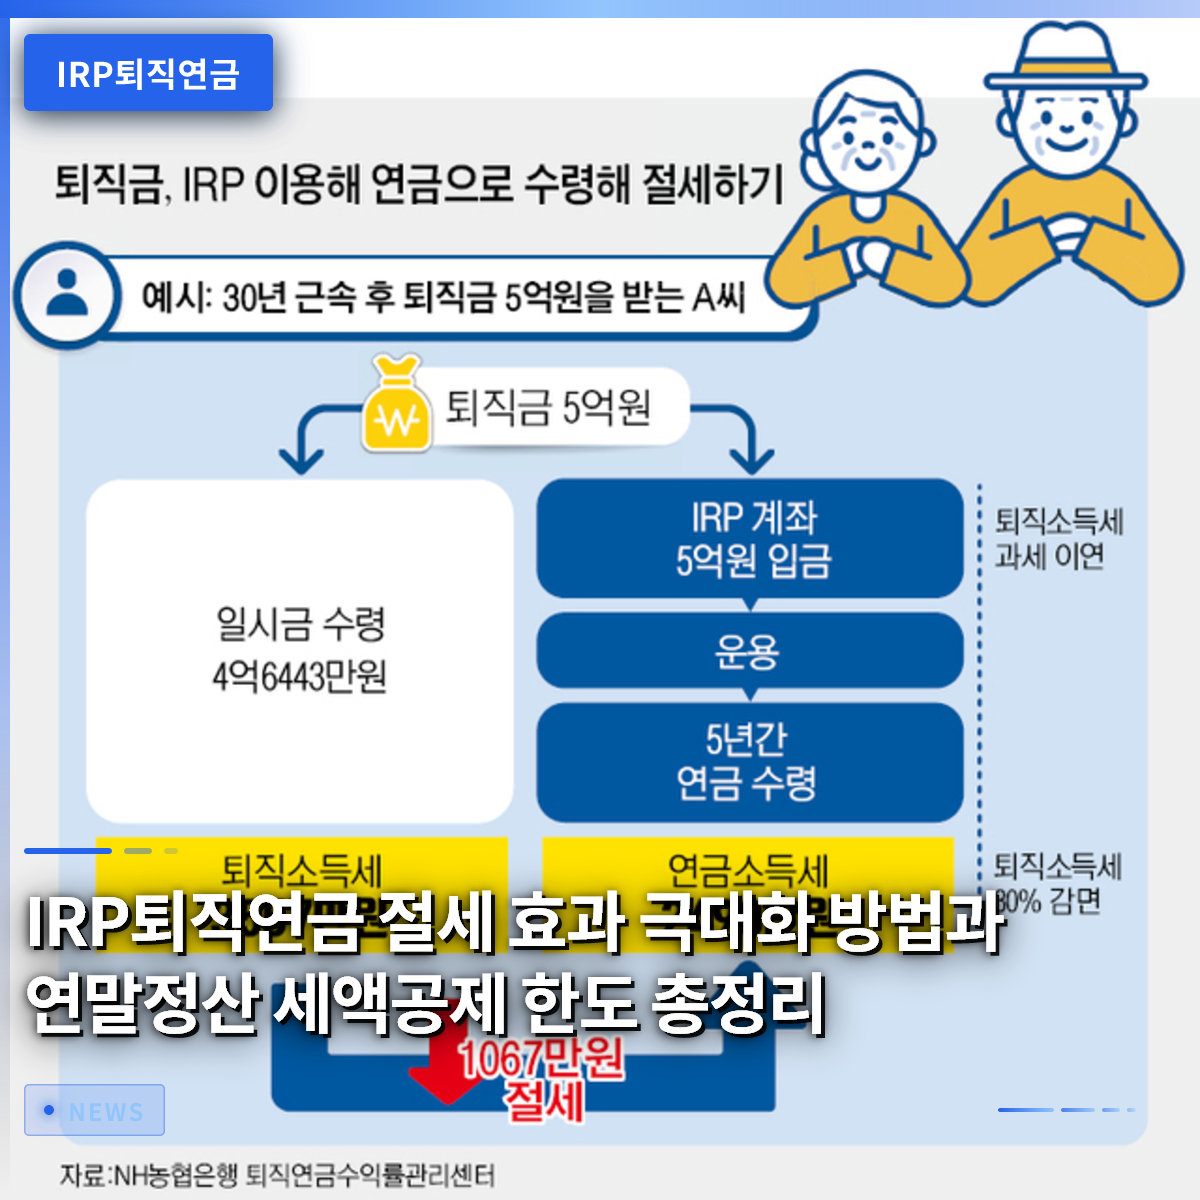
Deciding whether to receive your severance pay as a lump sum or as a pension is a crucial decision that determines the fate of your retirement funds. Receiving severance pay as a lump sum allows you to use a large amount of money immediately, but you must pay severance income tax all at once, resulting in a heavy tax burden. On the other hand, if you transfer your severance pay to an IRP account and receive it as a pension over 10 or 15 years, you can receive a tax reduction of 30% to 40% on severance income tax. For example, transferring 100 million KRW in severance pay to a pension account and receiving it in monthly installments can significantly reduce tax expenses compared to receiving it as a lump sum. Additionally, since you can invest the funds within the account to grow your assets while receiving the pension, it is far more advantageous in terms of asset growth. Mr. Park, an office worker nearing retirement, transferred his severance pay to an account and receives it monthly as living expenses for 15 years, saving on taxes while creating a stable cash flow. Choosing to receive funds in installments rather than using a large sum at once is the secret to achieving both tax savings and retirement stability.
Transferring severance pay to an IRP and receiving it as a pension can reduce taxes by up to 40%.
3. The Secret Behind the 15 Million KRW Annual Pension Income Limit

You may have heard warnings that you could face a tax bomb if your annual pension receipt exceeds 15 million KRW. Under tax law, if annual pension income is 15 million KRW or less, a low-rate pension income tax is applied. However, if it exceeds this amount, it may be combined with other income and taxed as comprehensive income. Consequently, among retirees, a strategy to adjust the pension receipt amount to around 1.2 million KRW per month to stay under the 15 million KRW limit has become essential. If your severance pay is large enough that the annual receipt would significantly exceed 15 million KRW, you should consider extending the receipt period to lower the annual amount. For example, extending the receipt period from 10 years to 15 or 20 years reduces the annual receipt amount, significantly lowering the tax burden. Since relevant standards may be fine-tuned according to the government’s direction on tax law revisions, it is advisable to seek expert advice before starting receipts. You must accurately understand the loopholes in the system to prevent your hard-earned retirement funds from being drained by taxes.
If the annual pension receipt exceeds 15 million KRW, the taxation method changes, so you should adjust the receipt period to save on taxes.
4. Conditions and Exceptions for Early Withdrawal
Life often presents situations where you urgently need a large sum of money, leading many to wonder if they can withdraw their retirement pension midway. Defined Contribution (DC) and Individual Retirement Pensions (IRP) generally have very strict rules regarding early withdrawal, which is only permitted in specific cases such as home purchase or securing a deposit for non-homeowners. Early withdrawal is also possible if you or a family member requires medical treatment for more than six months, allowing you to put out a fire in an emergency. However, early withdrawal is not possible for simple lack of living expenses or personal debt repayment, so you should maintain a separate emergency fund. Early withdrawal not only requires you to return the tax benefits received but also leads to the fatal consequence of losing precious retirement funds. Mr. Lee, an office worker, considered early withdrawal to buy a house but revised his plan to use a collateral loan, worried about reducing his retirement funds. It is wise to treat retirement pensions as a last resort and avoid early withdrawal as much as possible, maintaining the account until the end.
Early withdrawal from retirement pensions is only possible in exceptional circumstances defined by law, such as home purchase for non-homeowners or medical treatment.
5. Financial Company Events and Asset Management
Recently, many financial institutions are running events offering various gift certificates based on new sign-ups and asset management performance to attract IRP customers. When choosing a bank or securities firm, you should carefully compare the types of products you can manage yourself and the fee structure, rather than simply chasing gifts. Some financial institutions have introduced AI-based asset management tools to help subscribers easily invest in funds or bonds according to market conditions. You must diagnose your investment style and build an appropriate portfolio to increase returns in the long term. The quality of tax consulting or retirement planning programs also varies by financial institution, so it is advantageous to open your main account considering your post-retirement plans. Rather than relying solely on recommendations from acquaintances or advertisements, you need the wisdom to compare fees directly through the mobile apps of various financial institutions. The size of the assets you hold after retirement varies depending on how actively you manage your account.
Compare fees and investment product lineups by financial institution, and actively manage your assets using tools such as AI management systems.
6. Practical Strategies for a Successful Retirement
If you want a stable retirement, you need to immediately check the status of your pension account and start filling in the shortfall in contributions. Simply setting up automatic transfers to your IRP from a portion of your fixed monthly expenses creates a sturdy shield for your future. As the aging society deepens, the importance of self-prepared pensions will inevitably grow, and you must actively utilize the carrot of tax benefits. Based on the tax deduction limits and pension receipt strategies learned today, we hope you will receive a larger refund than others at next year’s year-end tax settlement. It may seem complex and difficult at first, but do not forget that small practices accumulate to determine the abundance of your retirement. Open your mobile app right now to check your contribution limits and managed products, and start your tax-saving investment today.
Consistent automatic transfers and thorough account management complete a successful retirement life and ample retirement funds.
Frequently Asked Questions
=