The Individual Retirement Pension (IRP) account is an essential asset management tool and a core tax-saving strategy that every employee must prioritize. To get straight to the point, if you fill the annual contribution limit of 9 million KRW, you can receive a substantial tax credit refund of up to 1.485 million KRW. Many employees postpone managing their retirement pensions, thinking retirement is still far away, but you must start preparing immediately to avoid a tax bomb during the year-end tax settlement. Recently, banks are offering diverse promotions, such as mobile gift cards, for new enrollees and customers managing investment products, making this an excellent opportunity. In this article, we will walk you through everything from calculating tax credits to receiving severance pay and practical investment tips in a friendly manner. Let’s explore the smart way to secure a stable retirement while saving on taxes.
=
IRP Retirement Pension Tax Deduction Limits and 2026 Enrollment Benefits: A Complete Guide
1. Basic Concepts and Importance of the Individual Retirement Pension (IRP)

The Individual Retirement Pension (IRP) is a highly useful system that allows employees to accumulate their severance pay in a personal account and continue investing it until retirement. In the past, severance pay managed by companies was often received directly into bank accounts, where it was easily spent or left neglected. However, by principle, it is now transferred to this account for safe protection. Since employees can also make additional voluntary contributions, it significantly helps in building a robust retirement fund. You can directly select and manage various financial products within the account, enabling active pursuit of returns rather than just sticking to deposits.
Many young professionals are initially shocked to see their severance pay deposited into this account when they change jobs. However, this is a beneficial mechanism designed by the government to ensure that our precious retirement funds are not spent all at once but are accumulated as a pension. Seeing seniors struggle due to insufficient funds after retirement makes the need for early preparation feel urgent. It is very easy to open an account by visiting a bank branch or using a mobile app, so there is no reason to delay. Turning on your smartphone right now and opening an account in your name is the first step toward successful asset management.
The IRP is an essential tax-saving account for safely accumulating severance pay and growing retirement assets.
2. Annual Tax Deduction Limits and the 9 Million KRW Trap

To avoid unnecessary taxes when managing both Pension Savings and IRP accounts, you must accurately understand the tax deduction limit structure. Pension Savings accounts are eligible for tax deductions on contributions of up to 6 million KRW on their own. When combined with personal contributions to the IRP, the total annual limit is set at a maximum of 9 million KRW. For example, if you have filled the 6 million KRW limit in Pension Savings, you must contribute an additional 3 million KRW to the IRP to fully utilize the 9 million KRW cap. Employees with a total annual income of 55 million KRW or less can receive a high deduction rate of 16.5%, resulting in a maximum refund of 1.485 million KRW.
I often see employees who lose out on refund benefits because they do not understand this structure, forcing money into Pension Savings while neglecting the IRP. Conversely, severance pay transferred to the IRP account or employer-funded Defined Contribution (DC) amounts are not considered personal contributions and are therefore excluded from the tax deduction limit calculation. Therefore, you need the wisdom to carefully assess your annual income level and contributions made so far, topping up only the shortfall. It is far more advantageous to make contributions in small increments now rather than regretting it during the year-end tax settlement season in late December. This smart method of maximizing tax benefits is the most reliable financial strategy available to employees.
Combining Pension Savings (up to 6 million KRW) and IRP contributions allows for a maximum annual contribution of 9 million KRW, yielding a refund of up to 1.485 million KRW.
3. Methods of Receiving Severance Pay and Exceptions for Early Withdrawal

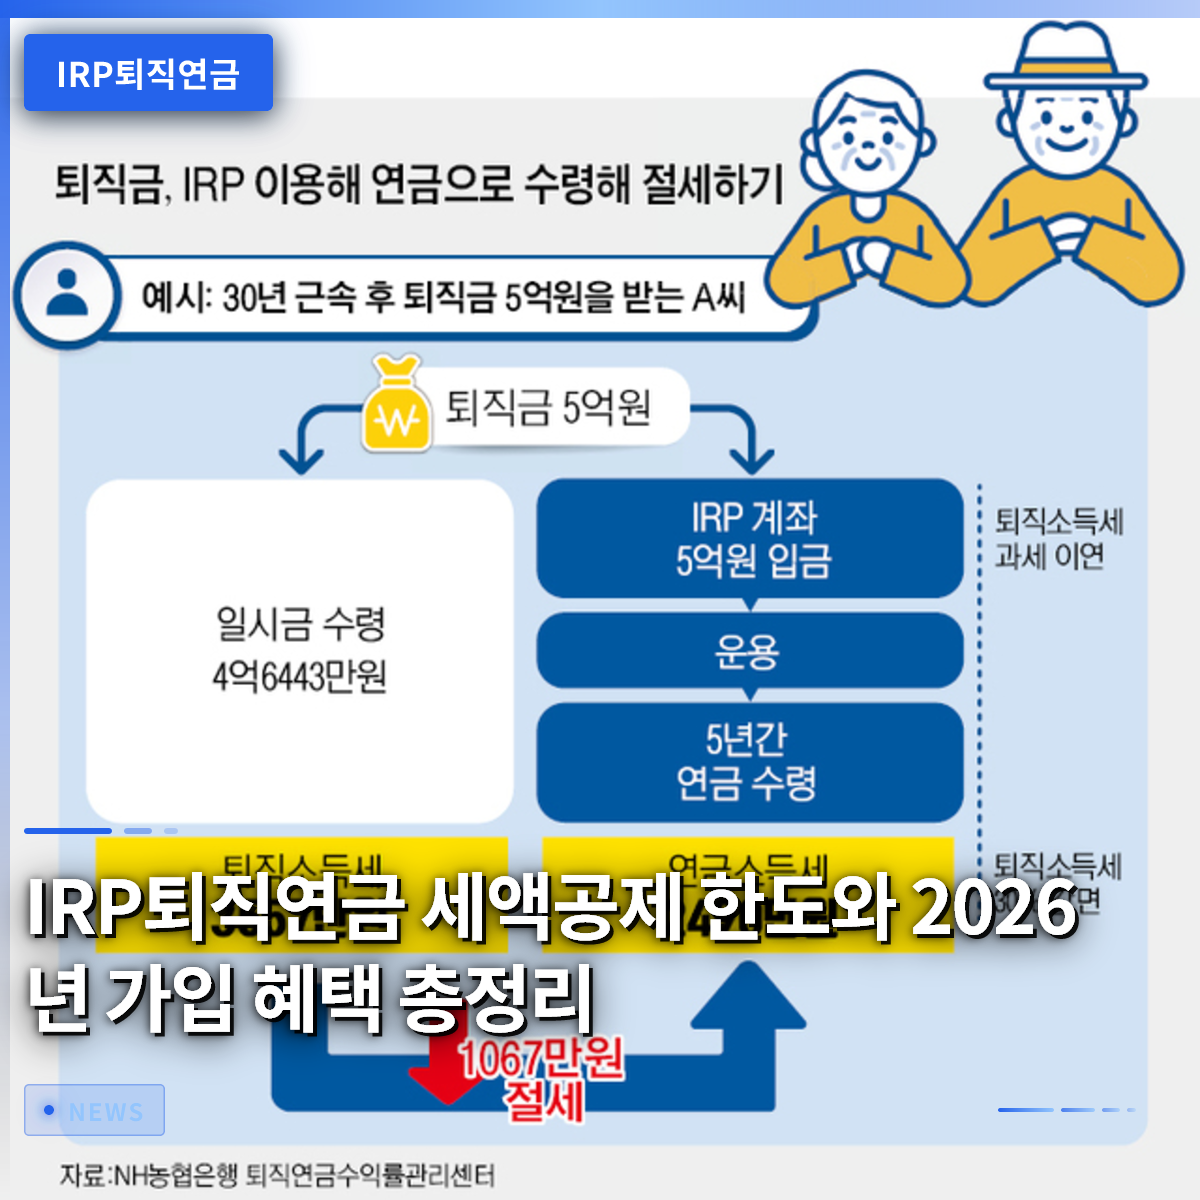
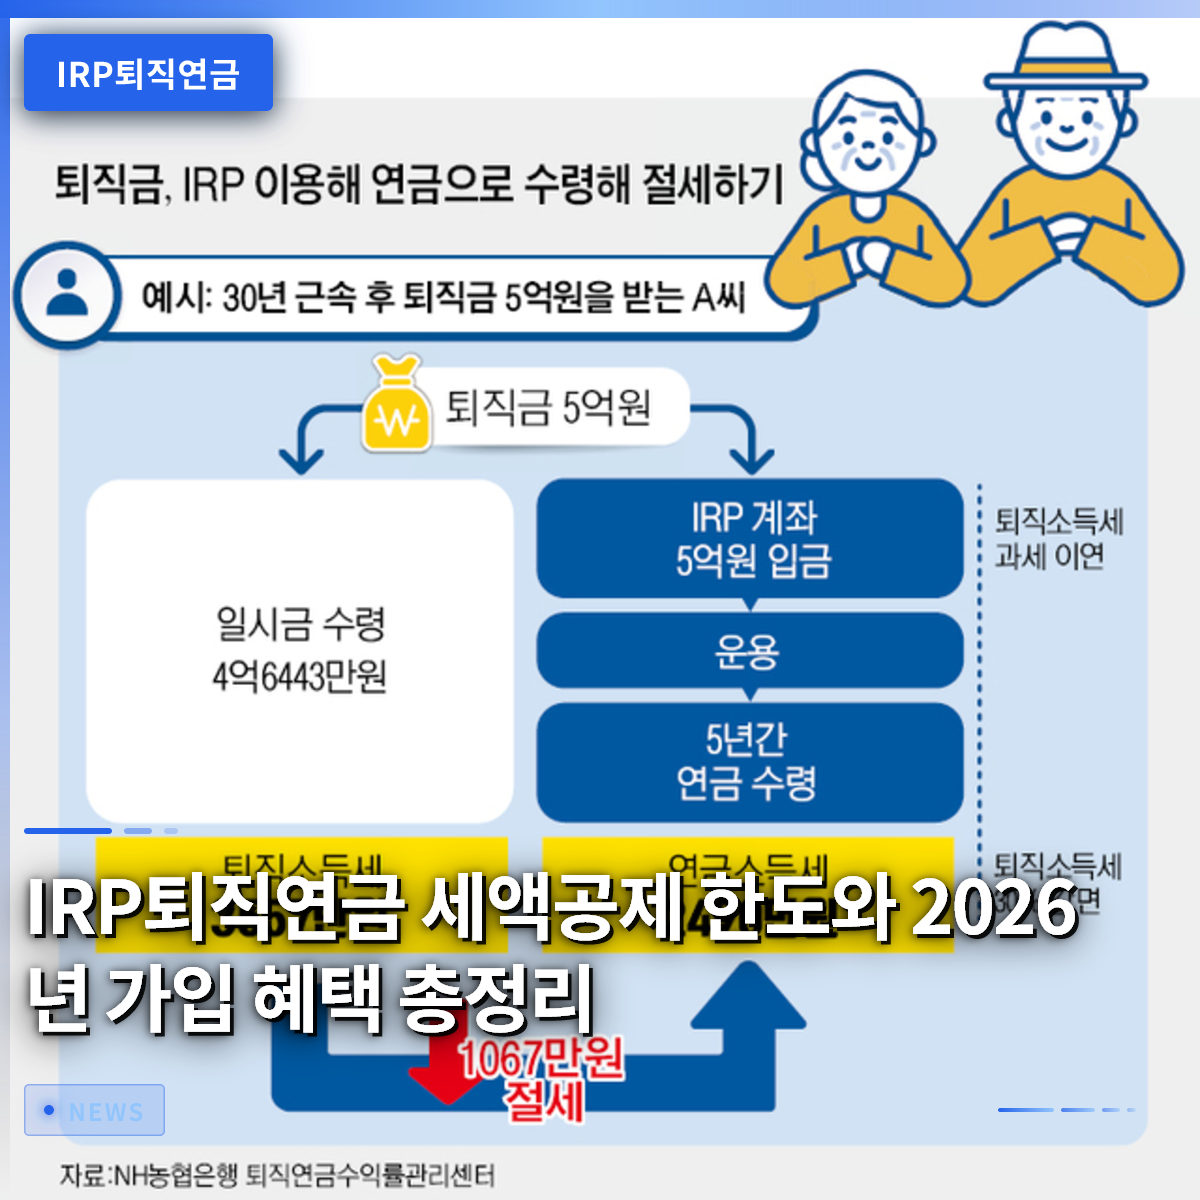
When leaving a company and receiving severance pay, it is transferred to the IRP account by principle, and you should later receive it as a pension or a lump sum. If you withdraw it immediately as cash, you must pay the full severance income tax. However, if you receive it in pension form, you can enjoy a tax reduction of up to 30%. Exceptions for early withdrawal are permitted in specific cases, such as when a non-homeowner purchases a house or needs to pay a deposit for a lease, or when medical expenses are required for long-term care for oneself or a family member. If such special circumstances arise, you can apply to the financial institution with the necessary supporting documents to access your funds first.
Recalling a specific case where a colleague overcame a major hurdle by using the early withdrawal system to buy their first home makes it easy to appreciate this system. If you arbitrarily close the account because you suddenly need a large sum of money before retirement, you face the severe penalty of having to return all the tax deduction benefits you previously received. Therefore, rather than closing the account, you should carefully consider the eligibility criteria for early withdrawal and make a cautious decision only when absolutely unavoidable. Since severance pay is a sturdy shield protecting our future, it is wisest to keep it intact and avoid touching it as much as possible. If you are planning to change jobs or retire in the future, I hope you will research the receipt methods in advance to wisely avoid a tax bomb.
Receiving severance pay via IRP and taking it out as a pension saves taxes; early withdrawal is only possible under strict exception conditions.
4. Setting Default Options and Tips for Active Asset Management
If you simply deposit money into the account and leave it without selecting any products, your assets will effectively suffer losses as they fail to keep up with inflation. To prevent this, the government and financial sector have introduced the Default Option system, which automatically invests your funds in a pre-designated portfolio even if you do not issue specific instructions. This is a system already common in pension-advanced countries like the US and Australia, providing a great way for busy employees to easily manage their returns. You must carefully select and register products that match your investment style, ranging from principal-and-interest guaranteed products to performance-linked funds.
Relying solely on deposit interest is risky given the recent inflationary pressure, so it is advisable to mix in Exchange-Traded Funds (ETFs) or equity products, accepting some risk. In fact, savvy investors around me strictly maintain a 70:30 ratio between safe and risky assets within their IRP accounts to steadily generate returns. You should regularly check your asset status in real-time via the smartphone app and periodically switch to preferred products. Since retirement pensions are the most important foundation determining your life after retirement, you need to manage them actively rather than neglecting them. I recommend logging into your retirement pension app today to immediately check if your Default Option is properly set.
Actively utilizing Default Options and combining various investment products is key to maximizing retirement pension returns.
5. Financial Sector Events and Points to Note When Enrolling
Recently, many commercial and regional banks are running generous promotions to encourage new IRP enrollees and customers managing their assets. For example, financial institutions like BNK Bank are offering mobile gift cards to customers who open new accounts or manage investment products like funds and ETFs until the end of the year. Utilizing these opportunities allows you to enjoy small but pleasant additional benefits while simultaneously starting your retirement preparation. However, since event participation conditions and specific criteria for eligible amounts may vary slightly by financial institution, you must read the announcements in advance.
When enrolling in financial products, it is far more important to carefully examine the fee structure you will bear than to be distracted by gifts or gift cards. Opening an account non-face-to-face often results in waived or significantly discounted asset management fees compared to opening one at a branch. Therefore, it is advantageous to actively choose the non-face-to-face enrollment method via smartphone apps rather than visiting a branch. Additionally, remember the fear of miscellaneous income tax and tax deduction clawbacks that occur upon early termination, and plan to hold the account until at least your retirement age. I hope you will become a smart financial consumer, not missing out on small benefits while securing the massive tax-saving effects.
Utilize enrollment events from various financial companies, but carefully compare fees and non-face-to-face benefits before enrolling.
6. Starting Retirement Preparation: Drawing a Future with IRP
Our life after retirement is longer and more substantial than we think, and securing the funds to support it can only succeed if prepared steadily from a young age. The habit of consistently filling the 9 million KRW limit every year and frugally collecting tax deduction benefits puts enormous wings on asset formation. Imagining facing a well-filled pension account as retirement approaches gives you no reason not to act now. As the financial environment becomes more complex and the structure shifts toward individuals taking responsibility for their own retirement, the importance of retirement pensions will grow daily. You must act now to check your account status, fill any contribution shortfalls, or purchase appropriate investment products. I hope you will start managing your retirement pension immediately today, envisioning the smiling face of yourself enjoying a comfortable and leisurely retirement in the future.
Consistent IRP contributions and active asset management complete a prosperous and stable life after retirement.
Frequently Asked Questions
=