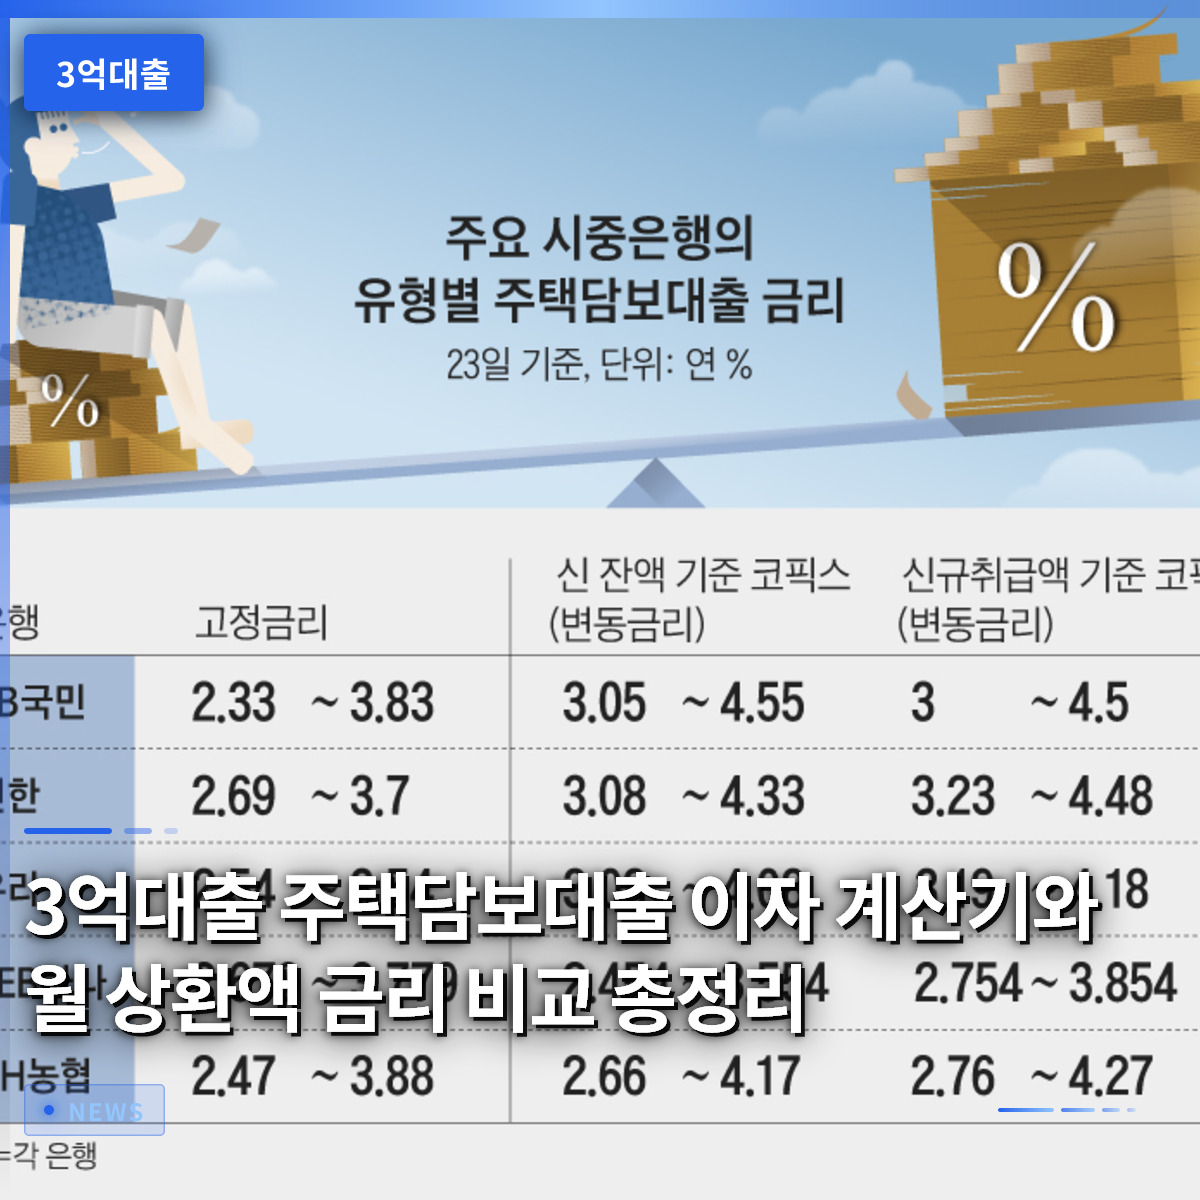
When borrowing 300 million KRW for a mortgage, rising interest rates can cause monthly interest payments to snowball, making thorough financial planning essential. People looking to buy their own home or secure a jeonse (long-term lease) in Seoul typically need to borrow a lump sum of around 300 million KRW. In a volatile interest rate environment, focusing solely on monthly interest can lead to significant financial strain. In fact, if interest rates rise to around 8%, the monthly interest on a 300 million KRW loan alone exceeds 2 million KRW. Today, we will take a detailed look at the interest rate conditions and the truth behind monthly repayment amounts that you must know when taking out a 300 million KRW loan.
=
300 Million KRW Mortgage: Interest Calculator, Monthly Payment, and Interest Rate Comparison Guide
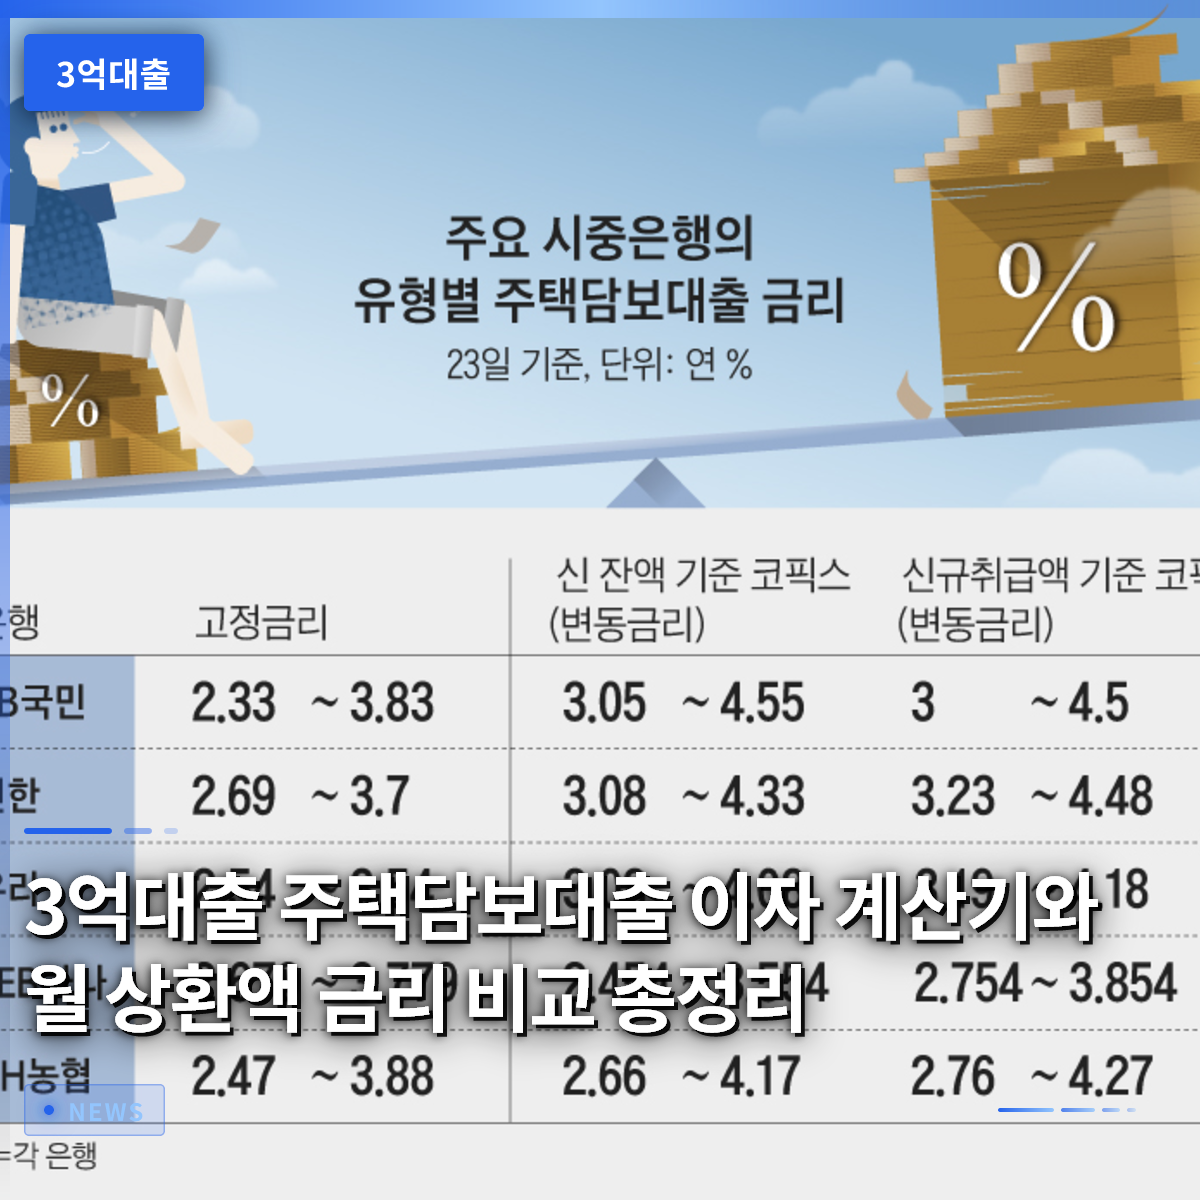
1. How Much Do You Pay Monthly on a 300 Million KRW Mortgage Over 30 Years?

If you take out a 300 million KRW loan with a 30-year term, you will pay approximately 1.5 million KRW per month in combined principal and interest. Many people easily judge that they can afford this amount based solely on the monthly payment. However, considering the 30-year loan term, one realizes that the total amount paid in interest alone is enormous. After diligently repaying the principal and interest for 30 years, the total repayment amount will significantly exceed the principal, easily surpassing 500 million KRW.
The money borrowed to achieve the dream of owning a home ultimately returns as a massive cost paid to the bank. If the money deducted from your account each month accounts for half of your income, it will significantly disrupt your daily life. Therefore, before executing a 300 million KRW loan, you must coldly assess whether it is within your manageable range by comparing it with your monthly income.
For a 30-year 300 million KRW loan, the monthly payment is around 1.5 million KRW, but the total repayment exceeds 500 million KRW, requiring thorough preparation.
2. The Fear of Soaring Rates: What Happens in an 8% Annual Interest Rate Era
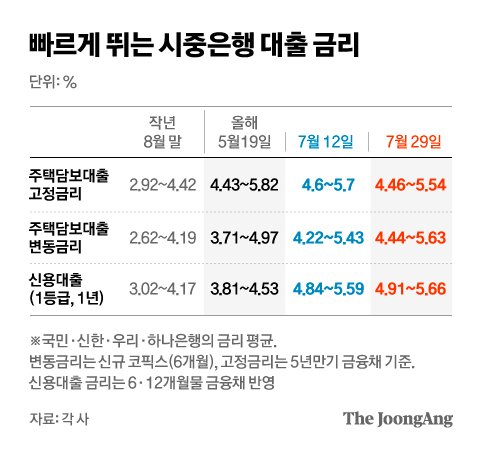
When interest rates are on the rise, those with a loan balance of 300 million KRW must prepare for an interest rate bomb. Even a 0.25 percentage point increase in interest rates can cause the monthly interest deducted from your account to swell by several hundred thousand KRW. If interest rates soar to near 8% in a worst-case scenario, the pure interest alone (excluding principal repayment) reaches 2 million KRW per month. Calculated annually, this results in an inescapable pain of 24 million KRW in interest costs alone.
If your salary remains the same while interest increases, your household’s savings capacity will hit rock bottom, forcing you to cut consumption. You may have felt safe when you took out the loan because rates were low, but market conditions can change rapidly at any time. Those who chose variable rates find themselves in a situation where they must swallow their tears and pay interest every month during periods of rising rates. Wisdom is needed to carefully compare the difference between variable and fixed rates to defend against interest rate fluctuation risks.
If interest rates rise to 8%, the annual interest burden on a 300 million KRW loan reaches 24 million KRW, dealing a fatal blow to household finances.
3. The Crossroads of Choice: Variable vs. Hybrid Interest Rates
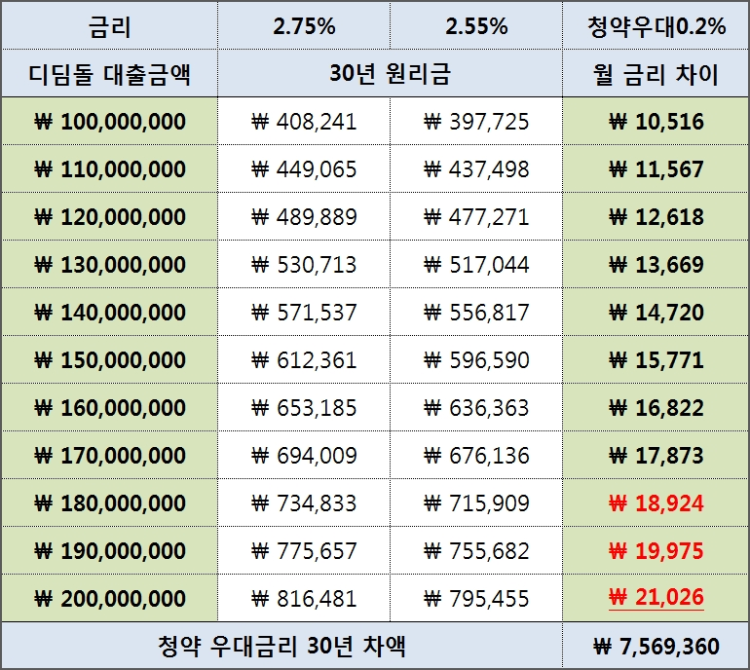
Seven out of ten people taking out mortgages still choose variable interest rates, requiring special caution. Variable rates have the advantage of appearing relatively low initially, reducing immediate interest burdens. However, it is a double-edged sword that requires paying a harsh price when benchmark rates surge in the future.
On the other hand, fixed or hybrid rates keep the interest rate fixed for a certain period, providing peace of mind from the fear of future rate hikes. The longer the loan term, such as 30 years, the more unimaginable the shock from interest rate fluctuations becomes. Experts advise choosing a product after closely observing future economic indicators and the trend of benchmark rates. You must make a careful decision to avoid saving a few cents now only to face a massive interest rate bomb in the future.
Variable rates offer lower initial interest but carry high risks during rate hikes, so careful selection is essential for long-term loans.
4. Special Loans for Newborns and Policy Funds: How to Utilize the 300 Million KRW Limit
By utilizing various government-supported policy loan products, you can secure a 300 million KRW loan at much lower interest rates than commercial banks. As housing purchase funding limits have been adjusted in recent years, actual demanders must accurately grasp the changed criteria. Relying on old data regarding past limits of 500 million or 300 million KRW when planning finances is likely to lead to trouble.
By applying special interest rates for products like the Stepping Stone loan for purchases, you can secure funds at interest rates ranging from the high 1% to the 4% range. Compared to general mortgages, this is a golden opportunity to save tens of millions of KRW in interest costs. It is most important to carefully check if you qualify and prepare the necessary documents. Since government support requirements change frequently, you must develop the habit of directly verifying the latest information.
Utilizing government special loan products allows you to secure 300 million KRW at lower rates than commercial banks, significantly reducing interest burdens.
5. Reality Check: 300 Million KRW Jeonse vs. Purchase, Which Choice Is Wise?
When considering owning a home, many people find themselves deeply torn between a 300 million KRW jeonse and a 300 million KRW apartment purchase. In the case of jeonse, you utilize a jeonse loan to secure the 300 million KRW deposit, incurring monthly interest costs. On the other hand, when purchasing a home, you add a 300 million KRW mortgage to your own capital to acquire a fully owned real estate asset.
Simply comparing the 300 million KRW jeonse deposit with the purchase price is a shortcut to missing the trends in the real estate market. Jeonse has the drawback that while you get the deposit back when the contract ends, you cannot enjoy the benefits of rising home prices. Conversely, if real estate prices fall during a purchase, you suffer the pain of asset value depreciation simultaneously with principal and interest repayments. You must make a careful judgment by comprehensively considering your economic situation and future housing stability.
Jeonse and purchases each have pros and cons, so when purchasing with a 300 million KRW loan, you must also consider fluctuations in asset value.
6. Final Advice for a Successful 300 Million KRW Loan Financial Plan
A loan is not simply an act of borrowing money but a heavy responsibility of pulling future income into the present. Before executing a 300 million KRW loan, you must thoroughly calculate your repayment capacity and the ratio of principal and interest to your income. Borrowing the maximum limit without thinking just because the bank offers it can lead to major financial trouble during periods of rising interest rates.
Since no one can accurately predict future economic conditions, you must always prepare for the worst-case scenario. A strategy of gradually reducing the principal through early repayment whenever surplus funds are available is the shortcut to saving on interest. Rather than sacrificing your daily life for excessive loans, you should safely increase your assets within a manageable range. Based on the content reviewed today, we hope you will start a wise financial life without regret.
A 300 million KRW loan should be managed safely by preparing for the worst-case interest rate scenario and establishing an early repayment strategy.
Frequently Asked Questions
=