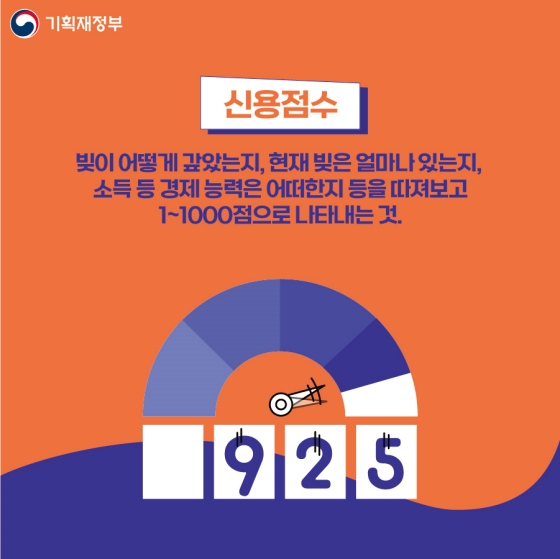
To quickly boost your credit score, you should simultaneously clear delinquency records, lower your credit card utilization rate, and repay small loans. Recently, loan companies have started allocating funds only to borrowers with scores of 800 or higher, offering favorable terms to prime customers. With the expansion of AI-based credit evaluations, it is increasingly pointed out that score management has become more important than product development. This article guides you through six actionable strategies step by step.
6 Practical Ways to Boost Your Credit Score in 2026 – Easy for Beginners
1. How to Clear Delinquency Records?

If you have delinquency records, first check your personal credit information with the Credit Information Corporation to verify any errors. If errors are found, submit a correction application. If the delinquency is legitimate, you must build a repayment record with no delinquencies for at least three months. Remember that if a delinquency exceeds 90 days, it takes a minimum of six months to recover your score. Key point: Accurate checking and correction procedures are the first step toward score recovery.
2. Tips for Lowering Your Credit Card Utilization Rate

Your score increases the most when your credit card utilization rate is below 30% of your limit. You can reduce your monthly payment amount while keeping your existing limit, or switch to automatic transfers to avoid using the card right before the billing date. While increasing your limit lowers the ratio, excessive limit increases can have a negative impact during re-evaluation. Key point: Maintaining a utilization rate below 30% is the most effective way to boost your score.
3. Score Boosting Strategy Using Small Loans
Set up small installment loans for a short period of 1–2 years and repay them via automatic transfer on a fixed date each month. This diversifies your credit activity and raises your score. It is safe to keep the loan amount below 10% of your annual income. After repaying the loan, pay off the balance in full. To maintain the loan record, it is advisable to avoid credit inquiries for about a year. Key point: Short-term small loans contribute to score increases by expanding credit activity.
4. AI and Token-Based Credit Score Services: Precautions
Recently, some fintech companies have started providing tokenized credit scores based on working hours and commute data. Since the scoring methods for these services may lack transparency, be sure to verify the provider’s certification and personal information processing policies before using them. Additionally, AI scores are operated separately from traditional credit evaluations, so you must manage both your existing score and the new AI score. Key point: Use new services as supplementary tools only after verification.
5. Conditions for Becoming a Prime Customer for Loan Companies
Loan companies recently offer lower interest rates and higher limits to borrowers with scores of 800 or higher. To become a prime customer, you must maintain credit activity for over two years without delinquencies and keep your credit card and loan ratios at appropriate levels. Since markup interest rate criteria vary by loan company, inquire directly about the application of markup rates before signing a contract. Key point: Consistent repayment and proper ratio management are the core of being a prime customer.
6. Checklist to Start Right Now
1) Check your personal credit information online today. 2) If you have delinquency records, proceed with a correction application. 3) Adjust your credit card utilization rate to below 30%. 4) Plan for a 1–2 year small loan. 5) Use AI and token services only after verification. Implementing these five steps can lead to a score increase within 3–6 months. Key point: These five actionable steps starting today are the key to score recovery.