Personal pension savings are the most reliable way to secure your retirement funds while simultaneously enjoying tax deduction benefits. Recently, many young people are struggling to save properly for retirement due to student loan debts and housing costs, prompting the government to introduce various support measures. For employees, it has become an essential financial product that must be joined to receive tax refunds during the annual year-end tax settlement. If you are paying the full amount of taxes while others around you are collecting hundreds of thousands of won in refunds every year, the difference lies in this specific account. In this article, we will detail the exact concept of personal pension savings, the structure of tax benefits, and smart ways to join.
=
Essential Reasons to Join a Personal Pension Savings Plan and a Complete Guide to Tax Deduction Limits
1. What is Personal Pension Savings?

Personal pension savings is a financial product where the government provides tax incentives to encourage long-term savings, allowing individuals to voluntarily prepare for their old age. It can be opened through banks, securities firms, or insurance companies, and you can manage various financial products within the account according to your investment preferences. While it previously focused mainly on earning interest or dividends, it has evolved recently to include diversified investments in various products to grow assets.
If you consistently contribute funds from a young age, you can receive a stable monthly living expense in the form of a pension when you reach retirement age. Recent statistics show that the importance of retirement funds is growing daily, making it advantageous for younger generations to prepare in advance. Starting small contributions as soon as you begin earning income from your job is the shortcut to building significant assets in the long run.
Personal pension savings is a long-term savings product that allows you to enjoy both voluntary retirement fund preparation and tax benefits.
2. Tax Deduction Benefits and Limit Structure

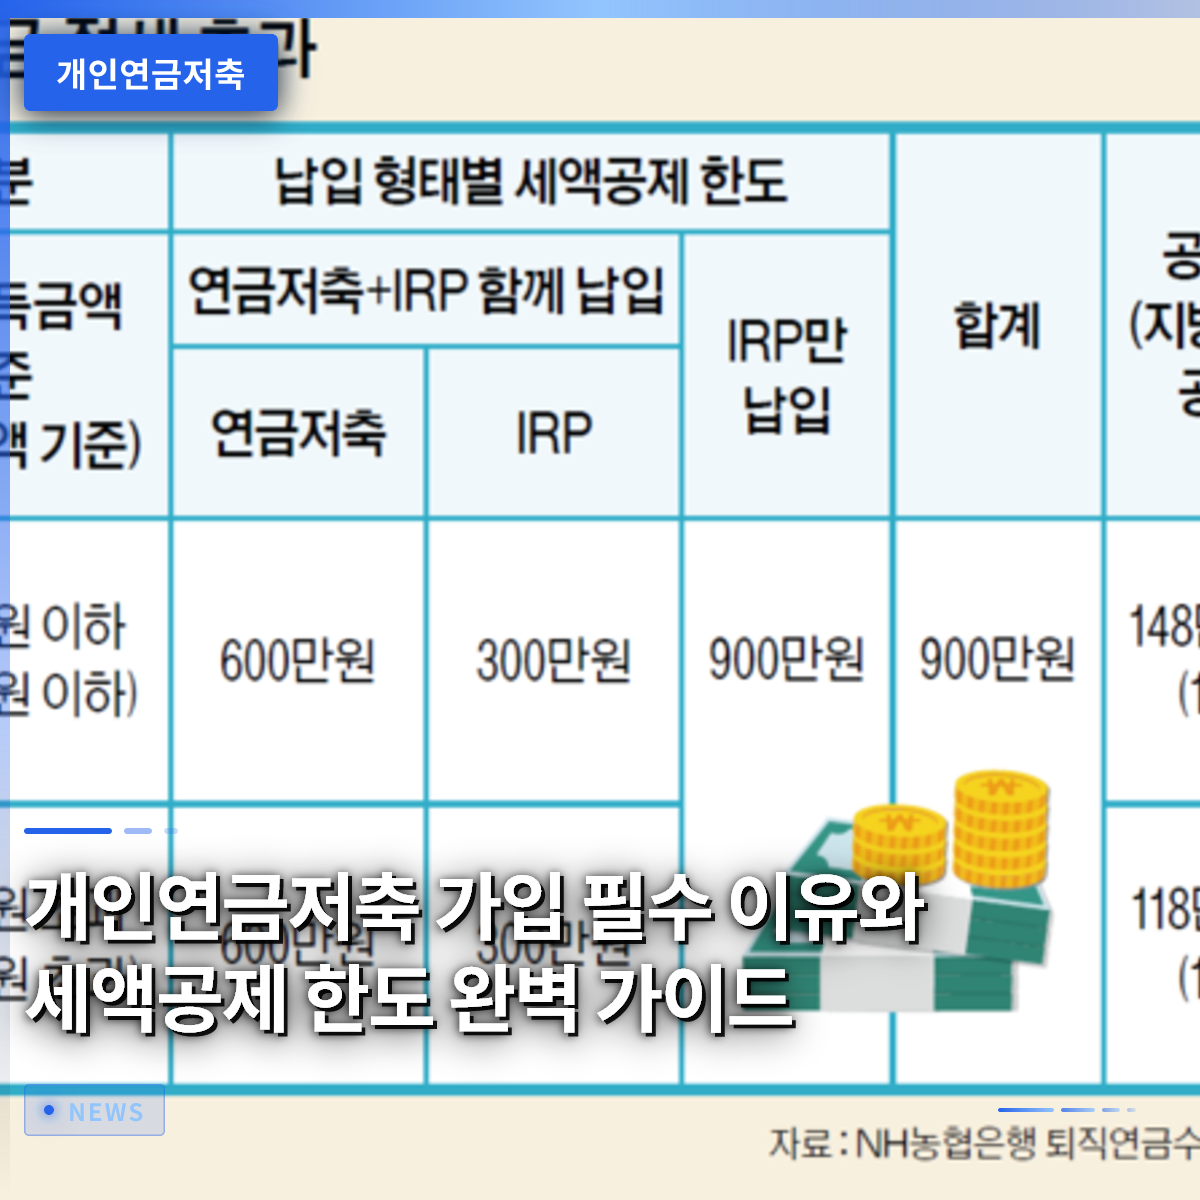
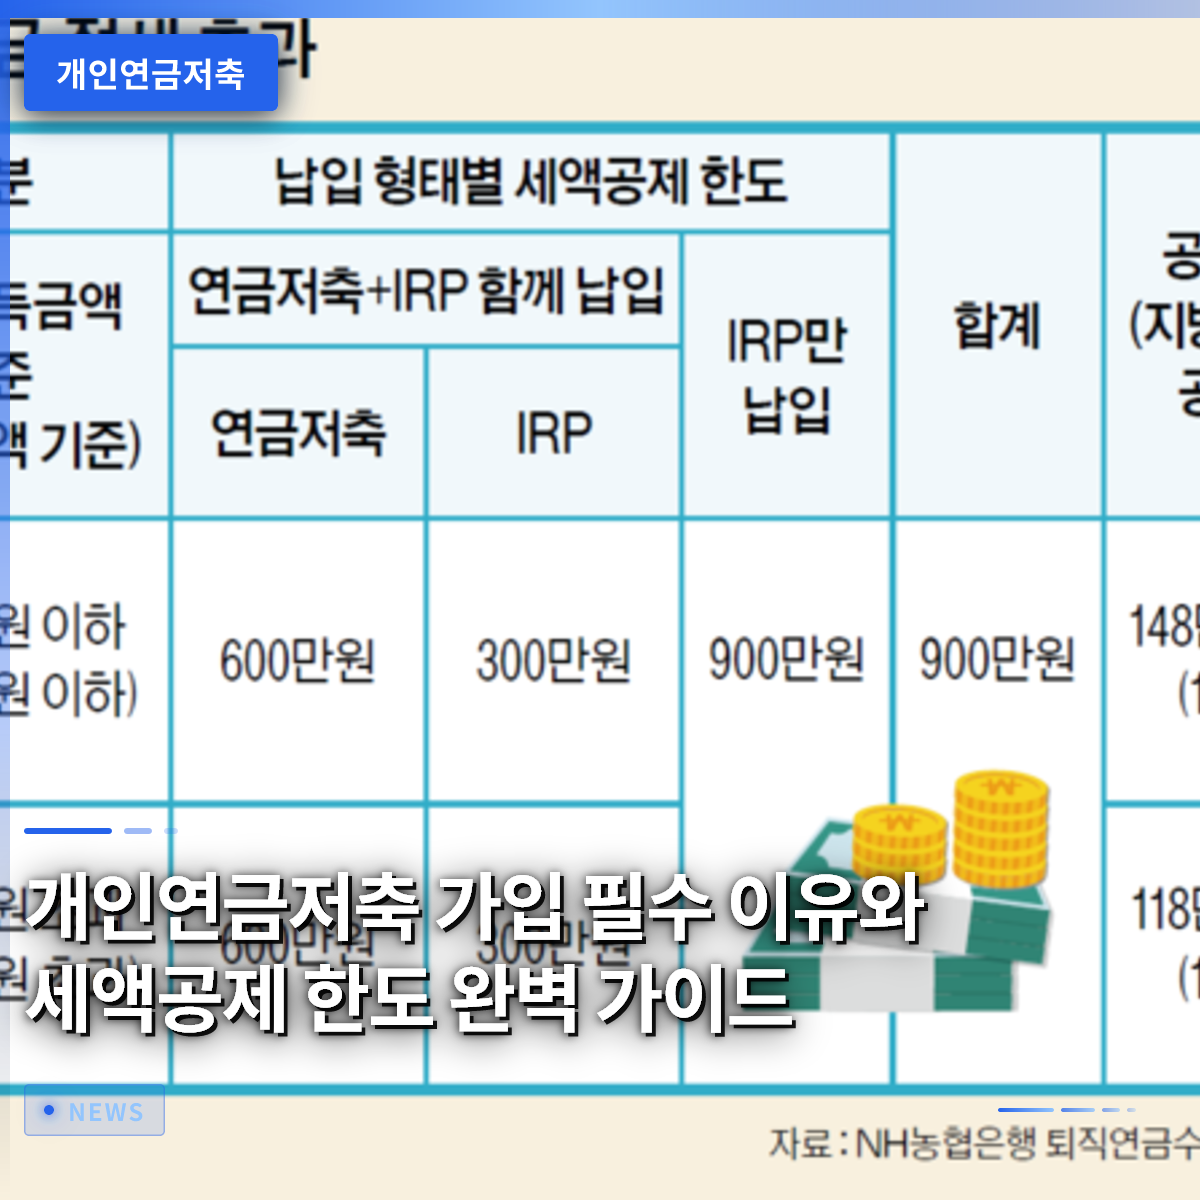
The biggest reason to join a pension savings plan is undoubtedly the powerful tax deduction benefit provided during the year-end tax settlement. The annual contribution limit eligible for tax deduction is up to 6 million won for pension savings alone, and this increases to a maximum of 9 million won when combined with an Individual Pension Account (IRA). You can receive a high deduction rate ranging from 13.2% to 16.5%, depending on your annual total income level.
For example, if you max out the annual limit of 9 million won, you can receive a refund of over 1.48 million won during the year-end tax settlement, depending on your income bracket. This offers a return rate that is incomparable to standard deposit products. By managing your finances to fill this limit when you receive a bonus or have surplus funds, you can significantly reduce your tax burden.
You can receive high tax deductions by contributing up to 6 million won for pension savings alone, or up to 9 million won when combined with an Individual Pension Account.
3. Utilizing Linkage with Other Savings Systems
While managing personal pension savings independently is good, linking it with other government-supported asset management systems doubles the effect. When the maturity of your Comprehensive Asset Management Account (CAMA), which was opened for tax-exempt benefits, arrives, you can immediately transfer those funds to a pension savings account. Transferring matured funds to a pension account allows you to receive additional tax deduction benefits, maximizing the tax-saving effect.
You can also link and manage assets in a similar way when youth savings or various government-supported financial products reach maturity. Concentrating funds scattered across multiple financial channels into a pension account makes long-term asset maintenance and management much easier. Experts advise utilizing this organic transfer structure rather than keeping individual products separate to grow retirement assets stably.
Transferring matured Comprehensive Asset Management Account funds to pension savings allows for efficient asset management along with additional tax deductions.
4. Asset Management Methods by Investment Preference
In the past, the focus was solely on stability, managing funds mainly through interest. However, it is now the trend to combine direct investments through securities accounts. You can increase your return rate by including various exchange-traded funds (ETFs), bonds, or equity products in your portfolio according to your investment preferences. For example, by appropriately allocating products that provide stable dividends and products from industries expected to grow, you can grow your assets while defending against inflation.
For younger subscribers, a strategy of investing a relatively high proportion in growth-oriented assets to aim for long-term compound interest effects is effective. Conversely, subscribers nearing retirement should increase the proportion of safe assets with low principal loss risk to focus on preserving assets. It is essential to periodically review and adjust your portfolio according to your age and financial situation.
Using a securities account allows you to construct a portfolio with various exchange-traded funds to pursue returns suited to your preference.
5. Precautions and Countermeasures for Early Termination
Since personal pension savings is a long-term product, easily terminating it midway because you need a lump sum can result in significant losses. If you terminate the contract early, you must return all the tax deduction benefits received so far, and additional income tax will be imposed. You may experience the painful reality of the money you saved diligently coming back as a tax bomb, so you must carefully assess your ability to pay before joining.
If you are in a situation where you truly need funds unavoidably, it is wiser to withdraw only a portion of the amount within the account or look into loan systems rather than terminating the account. Also, if long-term contributions feel burdensome, you should not set an overly ambitious monthly contribution amount from the start; instead, start with a small amount and gradually increase it. Since the sweetness of tax benefits comes with the strict condition of long-term maintenance, perseverance and patience are more important than anything else for this product.
Since you must return the tax deductions received if you terminate early, you should only contribute an amount you can afford according to your income situation.
6. Recommendations for Successful Retirement Preparation
Life after retirement is longer than expected and requires substantial funds, so if you do not prepare thoroughly from now, you will face significant difficulties. Although you may have many immediate expenses such as student loans or housing costs, you should deposit money into your pension account with the mindset of saving a few cups of coffee each month. As time passes, the magic of compound interest will work, and you will see with your own eyes that a much larger lump sum is created than you imagined.
It is essential to constantly check the direction of government tax reforms and trends in the financial market while consistently managing your pension portfolio. We hope you will enjoy the joy of retirement preparation, which may have seemed overwhelming, transforming into a sturdy support through systematic pension savings. We recommend opening your pension account and starting your first contribution immediately through a nearby financial institution or mobile app.
You should open a pension account immediately, trusting in consistent contributions and the long-term compound interest effect, to prepare for a secure retirement.
Frequently Asked Questions
=