Major mega insurance agencies in South Korea are abruptly abolishing the settlement allowance system, which was once a core weapon for recruiting agents, after being directly hit by the so-called 1200% rule regulation. In the past, agencies could easily hand over lump sums ranging from several million to tens of millions of won as allowances to scout experienced agents, but the situation has now changed completely. This shift is due to strengthened regulations requiring that settlement allowances be included within the first-year commission limit, prompting the field to scramble for survival strategies. For instance, even if an agency secures a contract with a monthly premium of 1 million won, the total amount payable in the first year is capped at 12 million won, making it impossible to provide separate allowances. As the institutional intent to curb excessive scouting competition takes root, the agency industry is facing a massive upheaval. In this article, we will take a detailed look at how this regulation is shaking up the insurance sales field.
=
[Exclusive] Wave of Settlement Allowance Abolition at Mega Insurance Agencies Amid 1200% Rule Aftermath
1. The Nature and Background of the 1200% Rule
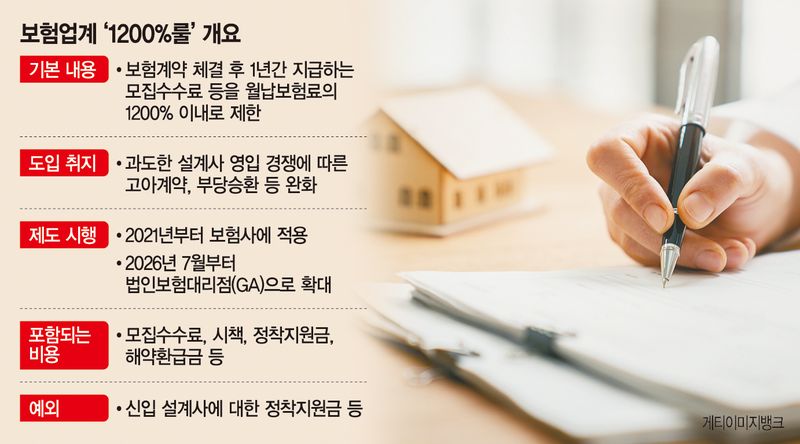
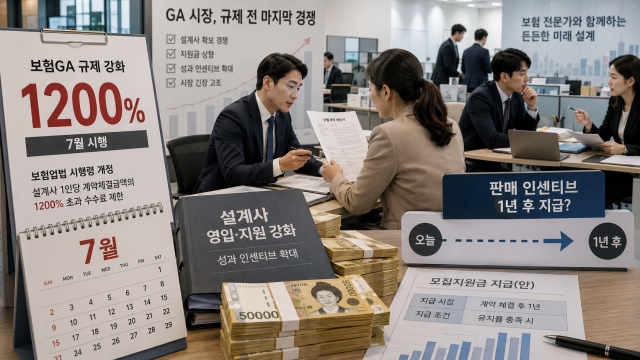
The 1200% rule, which has recently become the hottest topic in the domestic insurance industry, is a stringent regulatory system that limits the total recruitment commissions paid within the first year after an insurance contract is signed to no more than 12 times the monthly premium. In the past, some agencies excessively distributed upfront payments while aggressively poaching agents, which ultimately led to serious side effects such as incomplete sales and orphaned contracts lacking proper management. To cool down this overheated market and establish a healthy sales culture, financial authorities began applying this rule to insurance company headquarters starting in 2021. Then, from July this year, the scope of application was fully expanded to corporate insurance agencies (IA) with numerous affiliated agents, plunging the entire industry into significant confusion. The core of this rule is that not only the basic recruitment commission paid to agents but also various incentives, surrender values, and allowances to support new settlements are all included in the limit calculation. Consequently, agencies find themselves at a crossroads where they must completely abandon their previous sales methods of luring talented experienced agents with massive funds. As the regulatory scope expanded to include agencies, top-tier companies have quickly moved to avoid legal penalties and demonstrate soundness. The reason large agencies are voluntarily eliminating allowances, even without additional directives from the authorities, is that the penalties for violations are too severe. This rule is not merely a recommendation but carries strong legal binding force to correct market order, so agency executives must comply with it without exception. If they violate this rule by circumventing payments through irregular methods and are caught, they may face massive fines or business suspension. In this harsh atmosphere, agencies have come to face the cold reality that they can no longer expand their size using past methods. As a result, this regulation is acting as a decisive turning point that completely changes the landscape of the insurance agent sales market.
The expansion of the regulation limiting first-year commissions to 12 times the premium to agencies has completely blocked the past practice of paying large allowances.
2. The Reality of Settlement Allowance Abolition at Mega Agencies
Mega corporate insurance agencies such as Inka Financial Services, GA Korea, and Toss Insurance, which have thousands of affiliated agents, immediately abolished the settlement allowance system after the regulation took effect in July this year. These large-scale agencies quickly reorganized their systems as they could no longer provide the millions of won in settlement funds that were previously essential for recruiting experienced agents. A field source noted that while top agents at large agencies secure significant monthly premium volumes, the regulation has eliminated the loophole that previously allowed for allowances of tens of millions of won. This change is resulting in the resolution of the unfair allowance gap that existed between exclusive agents belonging to insurance companies (who were already subject to the rule) and agents belonging to agencies. Agencies are going through a critical period where they must put down their most powerful weapon, the allowance, and seek new breakthroughs for survival. However, not all agencies have uniformly and completely abolished the system; some companies are employing flexible strategies tailored to their circumstances. For example, Hanwha Life Financial Services has not completely abolished the settlement allowance system but has significantly reduced the portion allocated to experienced agents and restructured its policy to focus on new agents who are not subject to the regulation. As a subsidiary that had voluntarily adhered to the rules from the start, it avoided a major shock in the broader framework but made significant changes to the specific methods of fund execution. Nevertheless, the massive trend across the industry has firmly solidified toward reducing or completely abolishing allowances. Agency headquarters that previously lured agents with allowances are now completely revising their scouting strategies by offering other welfare benefits or sales convenience instead. With the disappearance of the practice of moving agencies in expectation of large cash payments, the industry-wide job-hopping market is also showing signs of freezing over.
Mega agencies with thousands of employees are abolishing allowances one after another, with a trend toward fine-tuning policies to focus on new hires rather than experienced staff.
3. Blocking Irregular Payments and the Financial Authority’s Strict Response Policy
Among some agencies, there have been considerations of cleverly bypassing the 12-month anniversary period to pay allowances after the 13th month or circumventing payments by providing funds in the form of loans. However, financial authorities have repeatedly declared a firm policy of keeping a close eye on such irregular and circumstantial commission payment practices, tracking them to the end and responding strictly. Since the original intent of the system is to fundamentally block excessive scouting competition and prevent incomplete sales, any attempt to circumvent it becomes an immediate target for sanctions. In fact, if agencies are caught exploiting loopholes in the regulations to use irregular methods, even the cancellation of their agency registration may be discussed, so field executives are devoting all their efforts to managing legal risks. The authorities’ tough stance sends a clear signal that tricks will not work in the market, playing a role in quickly correcting industry order. From the perspective of individual agents, even if a company provides allowances through back channels, it is not welcomed because it increases income uncertainty in the long term. In the past, so-called “grasshopper-style” sales, where agents received all rewards in the first month of a contract and then moved to another company, were prevalent, but such behavior is now impossible. As the market is restructured so that proper income is guaranteed only by maintaining contracts for the long term, agents are also improving their professional quality. The financial authorities’ meticulous surveillance network forces agencies to move away from outdated sales practices and compete solely on the quality of customer-centric, substantive insurance services. While the blade of this regulation delivers a major shock to the industry in the short term, it will serve as a positive stepping stone to enhance the credibility of the entire insurance industry in the long term. Ultimately, the era of pursuing short-term profits through irregular methods has come to a complete close, and transparent and fair competition has become the only path to survival.
With the authorities warning of strict responses to irregular circumvention methods such as 13th-month payments or loans, trick-based sales have been completely blocked.
4. Pivot to New Hire Cultivation and the Paradox of Regulation
As recruiting experienced agents through allowances has become virtually impossible, major agencies are turning their attention to a strategy of directly discovering and cultivating new agents. This is because there is an exception clause allowing newly hired agents to be exempt from the strict application of the 1200% rule for the first year after joining. Instead of luring successful agents from other companies with large sums of money, agencies have shifted their direction to nurturing talent themselves to solidify the fundamental strength of their organizations. Additionally, they have begun investing the massive funds previously poured into expensive talent scouting wars into building the latest digital sales infrastructure or introducing efficient systems. These changes are acting as a positive stimulus, forcing agencies to compete on technological capability and the quality of educational programs rather than financial muscle. However, behind these changes lie unavoidable side effects and the paradox of regulation, drawing deep sighs from the industry. With the disappearance of the sturdy support of settlement allowances, concerns are growing that experienced agents may massively leave agency organizations or even exit the industry altogether. In a situation where income ceilings are clearly defined, agents lose the motivation to work harder, which directly leads to decreased productivity. Since cultivating new hires also requires enormous time and cost, it is a daunting task for small and medium-sized agencies that must maintain their sales organizations immediately. Caught in the double bind of blocked experienced hiring and difficult new hire cultivation, the agency industry is facing a massive wave of labor shortages. Consequently, there are continuous points raised that regulations, while well-intentioned, fail to keep up with the pace of the field and may actually dampen market vitality.
With experienced hiring blocked, agencies are turning to new hire cultivation, but side effects such as the departure of skilled personnel and hiring difficulties are also growing simultaneously.
5. The Upcoming 4-Year Installment System and a Bigger Shockwave
Before the aftermath of the 1200% rule has even subsided, the industry is preparing to face another massive storm: the 4-year installment system, which will be introduced sequentially starting next year. The core of this system is the government’s strong will to spread out recruitment commissions, previously paid in bulk based on early sales performance, over a period of four years. As commissions are distributed over time, agents’ initial income will inevitably decrease noticeably, which will be a fatal blow to agents relying on insurance sales for their livelihood. Moreover, the installment period is scheduled to be significantly expanded to a maximum of seven years by 2029, so the reduction in agents’ initial income is expected to be beyond imagination. If the existing 1200% rule and this installment system overlap, there is a high risk that the entire industry will fall into a slump, contrary to the original intent of encouraging agents to maintain long-term contracts. When commissions are split over a long period, agents who are busy just making ends meet today are likely to suffer severe financial hardship and leave the insurance sales field. From the agencies’ perspective, with the disappearance of economic means to prevent the departure of affiliated agents, they must worry about extreme situations where maintaining the organization itself becomes impossible. Experts unanimously warn that even mega agencies with economies of scale will have no choice but to carry out structural adjustments to survive under the pressure of dual regulations. Ultimately, the major surgery on the commission system is shaking the income structure of the insurance agent profession to its roots, causing a massive earthquake across the labor market. In the midst of such rapid changes, both agents and agencies must break free from the illusion of high income and find a new formula for survival in order to survive.
With the introduction of the 4-year installment system next year overlapping with existing regulations, agents’ initial income is expected to plummet, accelerating labor outflow across the industry.
6. Changes in the Insurance Sales Ecosystem and Future Outlook
The abolition of settlement allowances by mega agencies and the successive strengthening of regulations will ultimately become a massive turning point that completely changes how insurance agents work and their survival strategies. The era of “migratory bird” sales, where agents moved between companies relying on large upfront allowances and flashy scouting conditions, has now forever disappeared into history. In the future insurance sales market, survival will be determined not by a battle of massive financial resources, but by how systematic the education system is and whether the company inspires trust in customers. Since agencies can no longer use the strategy of buying people with money, they must attract talent by highlighting differentiated welfare systems and a transparent, fair organizational culture. Individual agents, too, must transform into professional financial experts who maintain long-term contracts through thorough customer management, rather than being preoccupied with short-term performance, in order to survive. While the government’s strong regulatory drive brings side effects such as severe hiring difficulties and income reduction to the industry in the short term, it will serve as a foundation for creating a healthy market in the long term. A structural reform in which weak sales organizations naturally fall behind and only agencies with solid fundamentals survive is proceeding breathlessly even at this very moment. We hope that readers will accurately read this massive trend in the insurance market and wisely check the direction of change in their affiliated companies or their own sales strategies. Only those who cultivate their own expertise without being shaken by the waves of regulation will be able to smile to the end in the fierce financial market ahead. It is a time when the wisdom to leap to the next level by using the waves of upcoming change as new opportunities, rather than fearing them, is more urgently needed than ever.
The era of allowance-centric scouting is over, and survival strategies based on organizational culture and professionalism must be established going forward.
Frequently Asked Questions
=