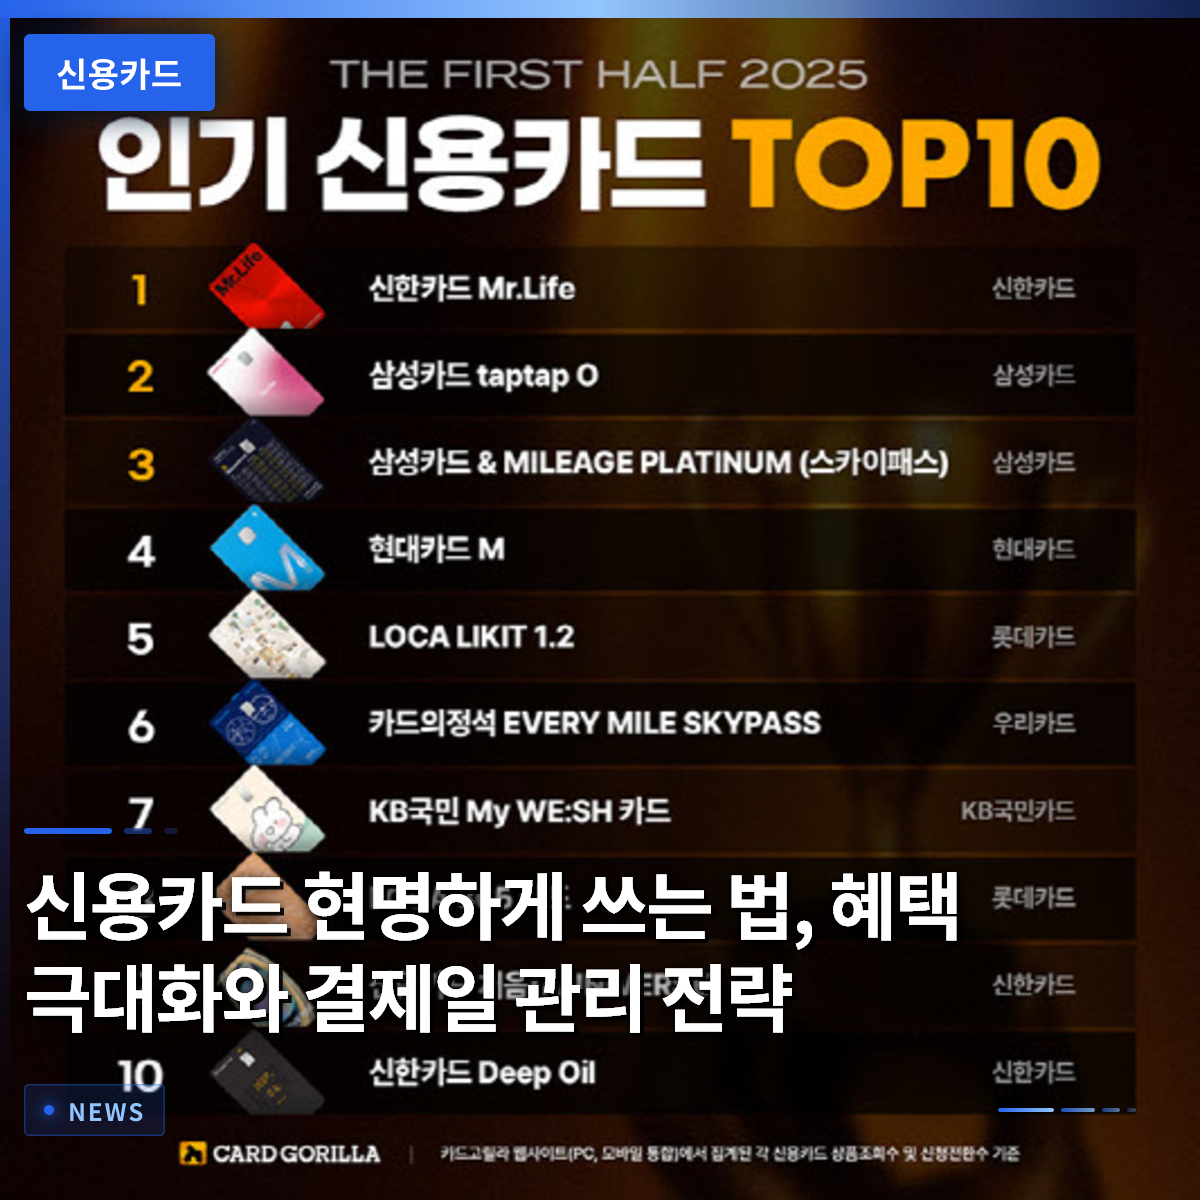
The wisest way to use a credit card is not to blindly choose products with the highest discount rates, but to select benefits that align with your actual living expense structure. If you rely solely on the “maximum monthly discount” advertised by card companies, you may end up increasing unnecessary spending and ultimately losing money. For example, if an employee who spends 500,000 won per month forces themselves to make excessive purchases to meet a 1,000,000 won spending requirement, the amount spent will exceed the discount received. Therefore, in this article, we will carefully examine everything you need to know when choosing a credit card, from how to calculate the “picking rate” to tips for managing payment dates during holiday breaks. We will go through various payment-related details that are often overlooked in daily life to help you build a more robust household budget. You can learn specific know-how to shift from vague, intuition-based spending habits to a method of reducing monthly expenses efficiently.
=
How to Use Credit Cards Wisely: Strategies for Maximizing Benefits and Managing Payment Dates
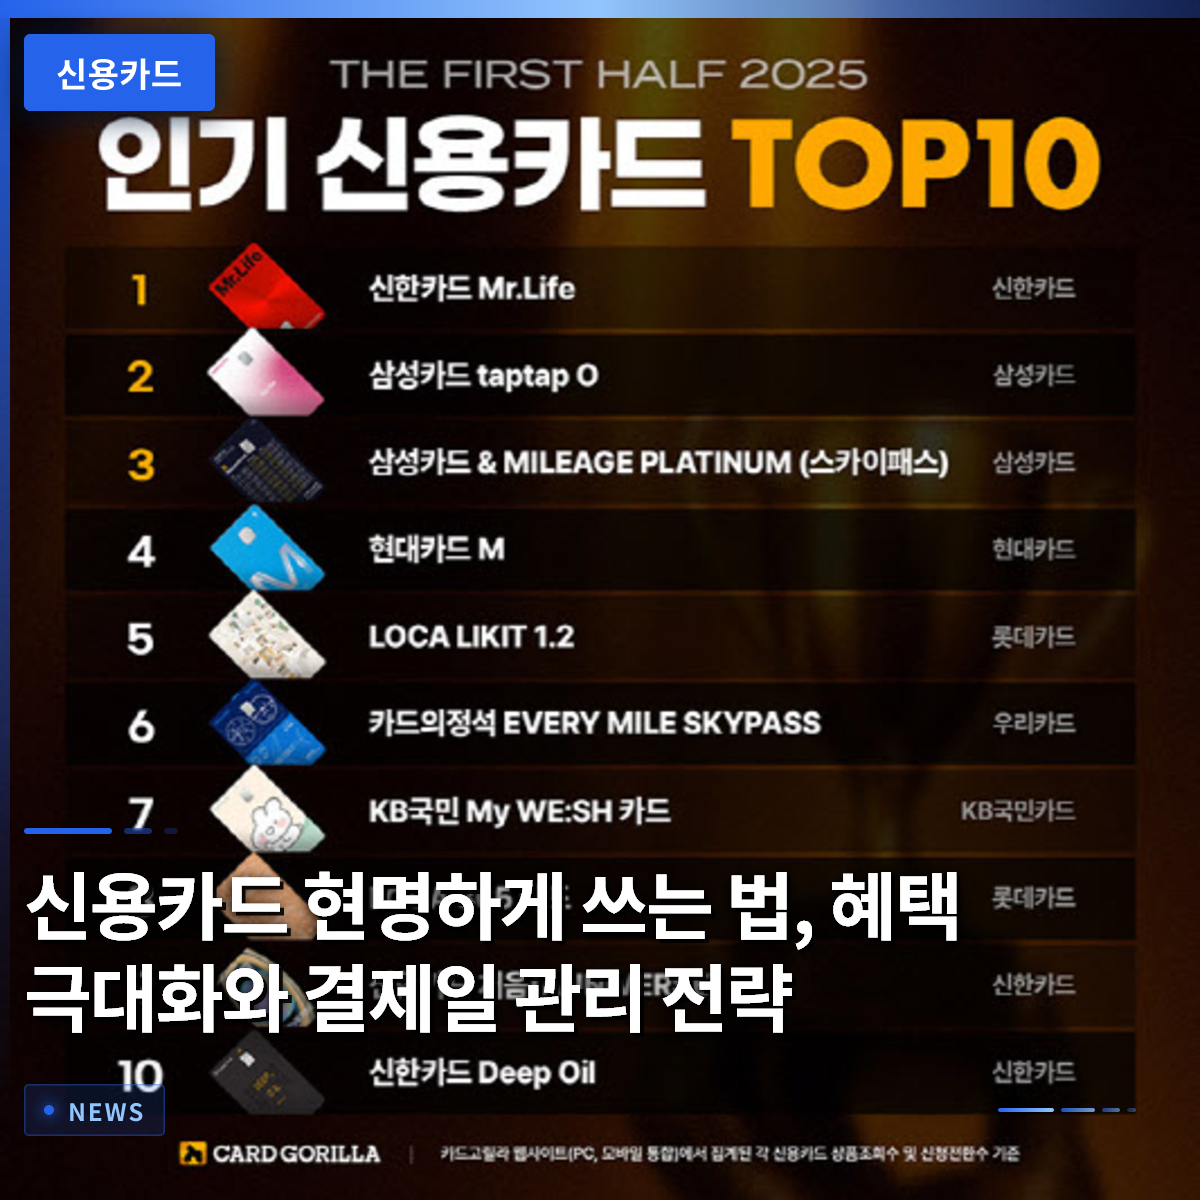
1. The Truth About Comparing Credit Card Benefits and Calculating the Picking Rate

The most common mistake consumers make when applying for a credit card is being swayed by the card company’s advertising slogans. Behind the flashy claim of a “maximum monthly discount of 50,000 won” lies a strict previous month’s spending requirement that must be met. If a product demands a spending level that is excessive compared to your actual usage, a flat-rate discount card might actually be more beneficial. The key metric you must calculate in this situation is the “picking rate,” which is the ratio of the money you get back to the money you spend. To calculate the picking rate accurately, divide the total benefits received in a month by the total amount charged to that card and express it as a percentage. Generally, a card is considered well-used if this figure exceeds 2%, while anything below 3% lacks significant appeal. For instance, if you spend 300,000 won and receive a 5,500 won discount, your picking rate is exactly 2%, making it an excellent choice. On the other hand, if you spend 1,000,000 won and only get 10,000 won back, the rate is less than 1%, meaning it is a card you should immediately remove from your wallet.
The picking rate, calculated based on your actual spending amount rather than the maximum benefit advertised by the card company, is the core criterion for selecting a card.
2. The Secret Behind Credit Card Payment Dates Falling on Holidays and Weekends

During long holidays like Chuseok (Korean Thanksgiving) or Seollal (Lunar New Year), employees often worry about insufficient balances causing late payments when their credit card bills are due. However, according to regulations from the Financial Services Commission and card companies, bills due during a holiday period are automatically debited on the first business day after the holiday ends, without incurring late fees. For example, if your payment date falls within a holiday break, there is no need to panic; simply ensure your account balance is sufficient on the first regular weekday after the break. This automatic debit grace period applies not only to credit cards but also to bank loan repayments and insurance premium payments, providing relief for many consumers. However, do not let your guard down completely; if your balance is insufficient at the time of the automatic debit immediately after the holiday, it will be recorded as a late payment. If you do not want to experience the shock of finding an insufficient balance on your way to work right after a holiday, it is best to check your schedule and balance in advance. This consideration from financial authorities acts as a sturdy barrier preventing consumers from suffering disadvantages due to weekends or public holidays.
Credit card bills due during a holiday are automatically debited on the first business day after the holiday without late fees, so it is safe as long as you ensure your balance is sufficient in advance.
3. Strategic Allocation of Credit and Debit Cards for Year-End Tax Settlement
As the year-end tax settlement season approaches, when you receive a refund on the taxes paid throughout the year, the division of roles between credit and debit cards becomes crucial. The government encourages workers to use credit cards, which offer relatively better benefits, for up to 25% of their total annual income. For amounts exceeding 25% of total income, the standard for tax savings is to focus on using debit cards or cash receipts, which have a much higher deduction rate. For example, an employee with an annual salary of 50 million won would benefit from using a credit card for points and discounts on spending up to 12.5 million won. Once this threshold is exceeded, you must switch to a debit card to maximize your income deduction limit. Many people mistakenly believe that debit cards are always better and use them exclusively from the start, thereby missing out on valuable credit card discounts. Conversely, if you only use credit cards, the lower deduction rate beyond the threshold can result in a smaller refund than expected, leading to disappointment.
To maximize your year-end tax refund, enjoy credit card benefits for spending up to 25% of your total income, and use debit cards for any amount exceeding that threshold.
4. The Risks of Buying Gift Vouchers with Credit Cards and Indiscriminate Spending to Meet Requirements
Some savvy consumers occasionally purchase large quantities of gift vouchers with their credit cards to meet previous month’s spending requirements or accumulate points. However, gift voucher purchases differ from general consumption and involve many tricky variables, such as payment method restrictions at the point of sale and identity verification processes. Many people are disappointed when they buy vouchers assuming they have ample remaining credit limit, only to receive a notification from the card company that the purchase will not count toward their spending requirements. While using gift vouchers to meet spending requirements was common in the past, card companies have recently strengthened their monitoring systems, excluding most such purchases from spending criteria. Repeated abnormal payment patterns can even lead to card suspension or credit limit reductions, so extreme caution is required. Trying to gain a slight benefit through such methods can backfire, restricting your card usage and making even everyday living expense payments inconvenient. Therefore, rather than struggling to meet requirements through circumstantial methods, it is safer to use a card that matches your actual consumption patterns, such as dining out or public transportation.
Meeting credit card spending requirements through gift voucher purchases is facing stricter enforcement recently, so it is wise to earn benefits through normal consumption.
5. Credit Card Spending as a Benchmark for Tax Audits and Income Verification
The National Tax Service operates various computerized systems to verify whether an individual’s income declaration matches their actual standard of living. It analyzes the total annual consumption spending from credit cards and cash receipts in conjunction with property increases and acquisition records of real estate or vehicles over the past few years. If there is a significant discrepancy between the estimated total income calculated this way and the income declared by the individual, they may immediately be selected as a target for a tax audit. As cases of failing to properly report sales from selling goods through social media markets or group buying have increased, the tax authorities’ surveillance net has become tighter. Cash transactions or unverified transactions are prone to falling into blind spots because they do not leave standardized records like credit card receipts or tax invoices. However, the moment consumers pay for such transactions with a credit card or issue a cash receipt, the related information is recorded directly in the National Tax Service’s computer network. Ultimately, transparent credit card usage records serve as an important standard for proving one’s consumption lifestyle while preventing tax evasion.
Annual consumption spending from credit cards and cash receipts is directly reflected in the National Tax Service’s income verification system, making transparent reporting essential.
6. Completing Your Credit Card Strategy with Overseas Travel Payments and Mileage Accumulation
More people are registering global credit cards, such as Visa, in advance before traveling abroad to save on currency exchange fees. By setting up passport identity verification and payment passwords before departure, you can complete payments safely at local stores without worrying about card malfunctions. You no longer need to carry a heavy wallet full of cash; a single smartphone app allows you to pay at all stores, significantly improving the quality of your trip. Additionally, mileage-accumulation cards are popular among frequent flyers and offer great value from a long-term perspective. When converting to airline miles, such as those from Korean Air, the accumulation rates for flight miles and credit card partnership miles differ, so you should carefully calculate and accumulate them. As the Fair Trade Commission recommends gradually increasing mileage usage, well-accumulated miles become a valuable asset. Going forward, it is necessary to adopt smart consumption habits that consider not just unconditional discounts but also the safety of overseas payments and airline mileage accumulation.
Registering your card in advance for overseas travel prevents payment errors, and consistently accumulating partnership miles allows you to enjoy practical benefits.
Frequently Asked Questions
=