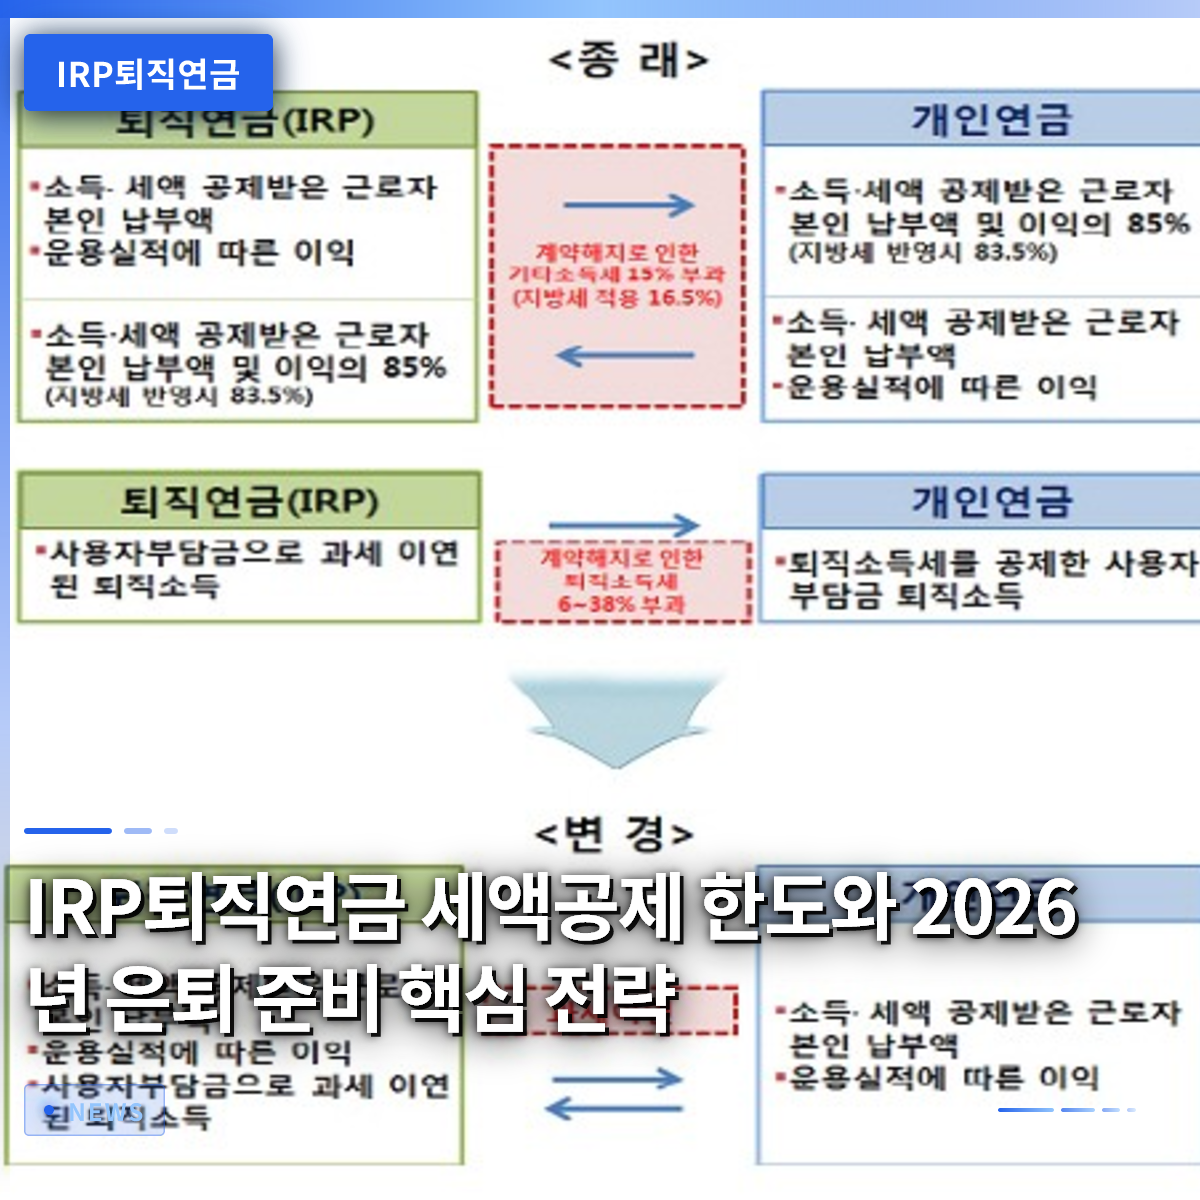
Actively utilizing an Individual Retirement Pension (IRP) account can earn you a tax deduction of up to 9 million KRW during your year-end tax settlement, making it an essential task for any employee. Even if you own a home worth 3 billion KRW, life after retirement can feel uncertain if you lack immediate cash flow. While many employees feel overwhelmed by the prospect of retirement, the core of retirement planning actually depends on how you secure your cash flow. In fact, many experts strongly recommend receiving your severance pay in installments through an IRP account rather than taking it all at once. According to current tax law revisions in 2026, if you receive your severance pay as a pension, you only pay 70% of the severance income tax if your actual years of service are 10 or fewer, and you can enjoy even greater tax reductions if you exceed 20 years. In this article, we will explore the various benefits of IRP retirement pensions that we often overlook and discuss specific ways to utilize them.
=
IRP Retirement Pension Tax Deduction Limits and Key Strategies for 2026 Retirement Planning
1. Pension Account Tax Deduction Limits

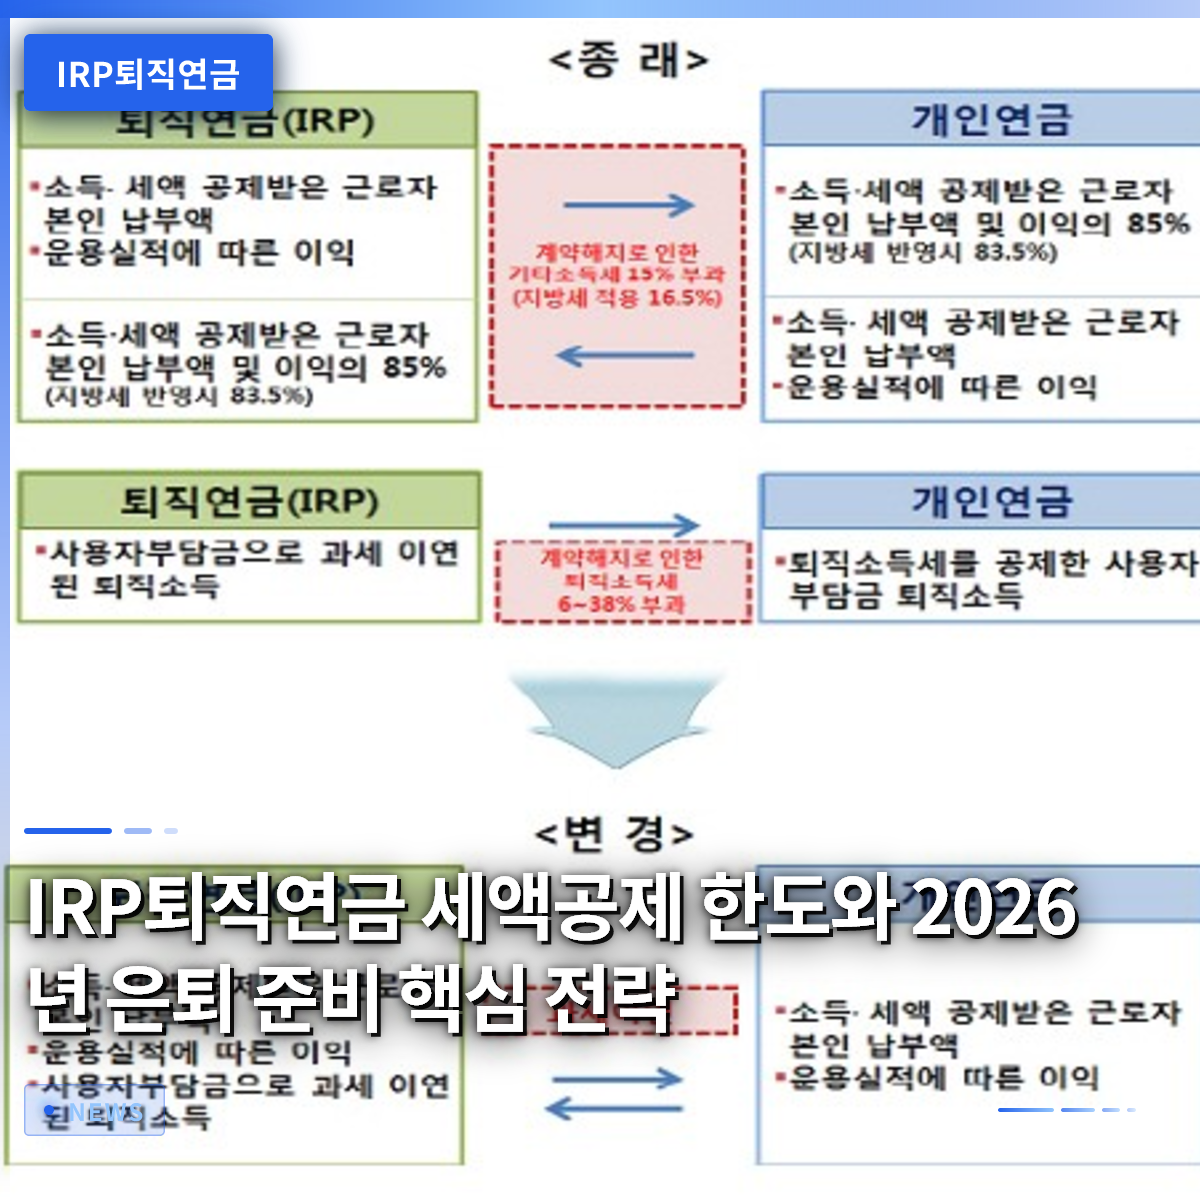
By combining pension savings and IRP retirement pensions, you can fully enjoy tax deduction benefits of up to 9 million KRW annually. Many employees search for various deduction products to get a tax refund during the year-end settlement season each year, yet they often fail to max out their pension account limits. According to the National Tax Service, the tax-deductible contribution limit for a pension savings account alone is set at 6 million KRW. However, when you add contributions to an IRP retirement pension account, the total combined limit for all pension accounts increases to 9 million KRW. The applicable tax deduction rate varies depending on whether your total annual income is below or exceeds 55 million KRW, so it is important to accurately check your income bracket.
Mr. Kim, a salaried employee, contributed only 6 million KRW to his pension savings account last year and stopped there. However, this year, he additionally contributed 3 million KRW to his IRP retirement pension, fully utilizing the total limit of 9 million KRW. This significantly increases the refund amount received during year-end settlement, making the process of saving a little each month more enjoyable. When he shared this fact with his colleagues, many of them regretted not having done the same last year. Pension accounts are not just a means to prepare for old age; they are an excellent tax-saving tool that keeps employees’ wallets full every year. Therefore, you should develop the habit of slightly reducing fixed monthly expenses or topping up your IRP retirement pension account with surplus funds whenever you receive a bonus.
Combining pension savings and IRP retirement pensions allows you to receive tax deduction benefits of up to 9 million KRW annually.
2. Receiving Severance Pay as a Pension Instead of a Lump Sum

It is far more advantageous to transfer your severance pay to an IRP retirement pension account and receive it as a pension in installments rather than taking it as a lump sum and consuming it. The hefty severance pay you receive when leaving a company may feel reassuring as a large sum of money in the short term, but it can easily run out quickly if spent without a plan. To maintain a stable life after retirement, it is crucial to create a consistent monthly cash flow into your account. According to 2026 standards, if you receive your severance pay as a pension and your actual years of service are 10 or fewer, only 70% of the severance income tax is applied. If the receipt period exceeds 10 years but is within 20 years, the reduction rate increases further, significantly lowering your tax burden.
You often see acquaintances who immediately buy a new car or use their severance pay for their children’s wedding expenses upon receiving it. However, these individuals often find themselves struggling to find new jobs a few years later due to a lack of living expenses. On the other hand, people who deposit their severance pay entirely into an IRP retirement pension and receive it as a monthly pension not only save on taxes but also significantly reduce the risk of retirement bankruptcy. In addition to tax reduction benefits, the remaining severance assets continue to generate interest in the financial market, resulting in excellent asset growth. Therefore, when facing the major life transition of retirement, it is wise to resist the temptation of a lump-sum payout and choose the pension receipt method.
Receiving severance pay as a pension through an IRP retirement pension can reduce severance income tax by up to 70% or more.
3. Diversified Asset Allocation and Utilization of Government Bonds

Within an IRP retirement pension account, you can increase your rate of return by utilizing not only deposits but also individual investor government bonds and various financial products. Many people mistakenly believe that retirement pensions simply require depositing money into principal-and-interest guaranteed bank deposit products. However, recent financial market data shows a steady increase in fund inflows to individual investor government bond subscriptions through Defined Contribution (DC) plans or IRP retirement pension accounts. Investing in safe assets like government bonds while securing appropriate returns has made them very popular among those in their 50s and 60s preparing for retirement.
Mr. Park, a 50-year-old employee just a few years away from retirement, had relied solely on bank deposits until he was disappointed by low interest rates and completely revised his portfolio. By appropriately mixing government bonds and funds with proven track records within his IRP retirement pension account, his overall rate of return improved significantly compared to before. For those worried about losing their principal while chasing high returns, government bond products guaranteed by the state can be the most reliable alternative. Developing the habit of diversifying and investing assets little by little each month allows you to protect your assets safely even amidst sudden economic fluctuations. Even without complex financial knowledge, anyone can easily grow a substantial retirement asset with just a little attention.
Utilizing government bonds and various products in an IRP retirement pension account allows you to achieve both stability and profitability.
4. Adoption of Latest Automated Investment Technologies
Currently, in 2026, you can manage your IRP retirement pension more easily through robo-advisors and automated trading systems offered by securities firms. Securities firms are continuously launching innovative services that automatically handle asset allocation tailored to customers’ investment tendencies by combining artificial intelligence technology. Users do not need to worry about which products to buy or sell; AI analyzes market conditions and constructs the optimal portfolio. For employees who are too busy to frequently check their accounts, these automated investment systems are a blessing in the desert.
Mr. Lee, an employee who had neglected his retirement pension account due to a busy work schedule, felt much more at ease after recently connecting to a securities firm’s AI asset management service. By simply entering his investment tendency, the system automatically diversifies investments into high-quality domestic and international assets, requiring no separate management effort. In fact, many financial institutions are competing to attract retirement pension customers by lowering fees and providing convenient mobile interfaces. Thanks to these technological advancements, even people who were previously uninterested in wealth management can now receive systematic asset management at an expert level. We are now in an era where advanced systems reliably grow your retirement funds without you having to do the legwork yourself.
Using AI-based automated investment systems allows busy employees to easily manage their IRP retirement pensions.
5. Additional Contributions and Utilizing ISA Maturity
Transferring ISA maturity funds to an IRP retirement pension or pension savings account can provide additional tax benefits and opportunities to manage large sums of money. When your Individual Savings Account (ISA) reaches maturity, it is far more advantageous to transfer the funds directly to a pension account rather than simply withdrawing them to a regular checking account. Since you can also receive additional tax deduction benefits during the transfer process, financial experts never miss this opportunity. It is also a good method to share these hidden financial tips one by one while checking your asset status with your parents during holidays or long weekends.
Mrs. Jeong, a housewife, was worried as the maturity date of her account, which she had diligently funded for several years, approached. However, following the guidance of a bank employee, she transferred the entire amount to a pension account. As a result, she was able to safely manage the large sum of money and also received additional deduction benefits, resulting in a much larger tax refund than expected during year-end settlement. When she told people around her about this method, they were amazed, saying they didn’t know they could utilize account maturity management in this way. Financial life after retirement becomes completely different depending on how much information you know and put into practice. The habit of accumulating spare change or maturity funds in a pension account serves as the most reliable insurance for your future self.
Transferring ISA maturity funds to an IRP retirement pension allows for efficient management of large sums of money along with additional tax benefits.
6. Practical Strategies for Retirement Preparation
If you want a successful retirement, the most important thing is the practical ability to open an IRP retirement pension account immediately and make consistent monthly contributions. As retirement approaches, the importance of cash flow increases, and completing the three-tier pension structure is the only shortcut to preventing retirement bankruptcy. By actively utilizing personal pensions and IRPs in addition to the National Pension and retirement pensions, you can reliably earn the stable living expenses you desire for a lifetime. In the rapidly changing economic environment of 2026, those who start their retirement planning one step ahead of others will ultimately be the ones who smile.
Right now, please turn on your smartphone app, check your retirement pension account, and see how much of the tax deduction limit remains. The process of saving a little each month to fund your pension account may seem troublesome at first, but it creates a huge difference a few years down the line. Retirement is not a story of the distant future but a reality that all of us must face, so thorough preparation is happiness itself. Based on the various tax-saving benefits and investment strategies learned today, we hope you will beautifully design your precious retirement assets starting now. A small bit of attention and one practical step can completely change your lifelong asset management.
You should immediately check your IRP retirement pension account and make consistent contributions to complete a solid, lifelong cash flow.
Frequently Asked Questions
=