If you don’t want to lock your money in a fixed-term deposit because you plan to use it soon, but you also don’t want to leave it in a regular checking account where the interest is negligible, a parking account is the most sensible alternative. With the base interest rate rising consecutively recently, commercial banks and savings banks are competitively raising interest rates not only for fixed deposits and savings accounts but also for demand deposit accounts, significantly broadening consumers’ options. If you are waiting for a stock investment opportunity or need to temporarily hold a lump sum, it is advantageous to accurately understand the characteristics of these products before signing up. In fact, the number of people looking for banking products to invest holiday bonuses or spare cash in the short term has surged. In this article, we will carefully examine everything from the current interest rate levels of popular products in the market to methods for safely protecting your principal.
=
Parking Account Interest Rate Comparison and Usage: The Best Way to Put Your Money to Work Immediately
1. Differences Between Parking Accounts and Regular Checking Accounts
Parking accounts are fundamentally different from regular checking accounts because they pay interest even if you park your money for just one day, much like briefly parking a car. While standard bank accounts offer almost no interest regardless of the balance, these products have the advantage of calculating and paying interest on a daily basis. It is perfect for holding funds that will stay for a week to a month, such as while waiting for the right timing to trade stocks or before paying the final balance on a real estate contract. In the past, these accounts were merely a means of storing money, but recently, due to fierce competition among financial institutions, they offer interest rates ranging from 3% to as high as 7% per annum. The biggest appeal is that you can expect returns comparable to fixed-term deposits while enjoying the freedom to deposit and withdraw funds at any time without complex conditions. Mr. Kim, an office worker, immediately transfers his surplus funds (after deducting living expenses) to this account as soon as he receives his salary, earning a decent interest income every month.
Unlike regular accounts, parking accounts accrue interest even for a one-day deposit, making them an optimal tool for short-term fund management.
2. Trends in Interest Rate Changes Due to Base Rate Hikes

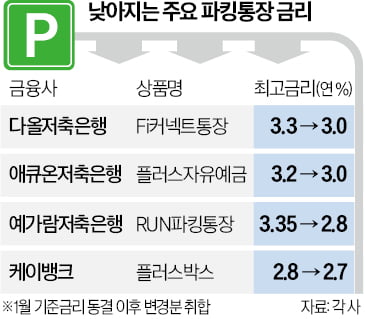
As the Bank of Korea has consecutively raised the base interest rate, overall market interest rates are showing a steep upward trend. It is not just loan rates that are rising; there is a clear phenomenon where interest rates for deposits, savings accounts, and demand deposit products are also rising in tandem. In this market environment, financial institutions are competitively raising parking account interest rates to secure lending and deposit customers. Interest rates that were in the 1% range just a few years ago now exceed 3% as a baseline, and special promotional products can even surpass 5%. Among office workers interested in wealth management, it has become essential to share these interest rate fluctuations in real-time and move to the most favorable conditions. The popularity of products that allow you to safely hold cash while earning interest income increases the more unstable the economic situation becomes.
Due to consecutive base rate hikes, interest rates for demand deposit accounts have risen significantly, and competition among financial institutions is fierce.
3. Carefully Checking Limits and Preferential Conditions
Caution is needed because you cannot receive the high interest rate on unlimited amounts, even for products advertising high rates. Most banks and savings banks apply high interest rates only to balances below a certain amount and assign relatively lower rates to any excess. For example, they may offer benefits of over 4% per annum for amounts up to 2 million or 3 million won, but rates drop to standard deposit levels for amounts exceeding that. Additionally, preferential interest rates are often applied only if you sign up through a specific partner’s app or meet salary transfer performance criteria. Mrs. Park, a housewife, regretted receiving less interest than expected due to limit restrictions after signing up based solely on the advertising copy. Therefore, you must develop the habit of checking whether the amount of funds you plan to deposit falls within the preferential limit before signing up.
You must check the high-interest rate limits and preferential conditions in advance to prevent unexpected interest losses.
4. Ensuring Safety Through the Deposit Insurance System
No matter how high the interest rate is, a product is never a good choice if you cannot fully recover your principal. In addition to commercial banks, products sold by savings banks are also safely protected up to 50 million won per person (including principal and a certain amount of interest) under the Deposit Insurance Act. Recently, many parking accounts offered by savings banks present extraordinary interest rates, causing anxiety for some people. However, since designated national institutions guarantee the principal and interest in case of financial institution bankruptcy, you can safely entrust amounts under 50 million won. If your surplus funds exceed 50 million won, it is wise to diversify your deposits across multiple institutions rather than putting everything into one. You must manage your assets with a clear understanding of these safety mechanisms to protect your valuable assets from potential financial accidents.
Deposit insurance applies up to 50 million won per person, so you should increase safety through diversified deposits.
5. Strategy for 100% Utilization of Holiday Bonuses and Spare Cash
Ahead of holidays like Chuseok (Korean Thanksgiving) or Seollal (Lunar New Year), financial institutions pour out special deposit products to attract customers. There is nothing better than a holiday special parking account for temporarily locking up bonuses received from long-term employment or money gifts from relatives. If you are hesitating to sign up for a fixed-term deposit because you don’t know when you might need emergency funds, it is advantageous to keep the money in this product and withdraw it as needed. In fact, many consumers deposit money for a short period ranging from one week to one or two months during the holiday season, earning a decent side income. The core of wealth management is to keep money working, even for just one extra day, so funds should be flexibly allocated according to their nature. You can taste a small success in wealth management simply by moving your Chuseok bonus from a regular checking account to a high-interest demand deposit account.
Keeping short-term spare cash, such as holiday bonuses, in a demand deposit account allows you to catch both flexibility and interest.
6. Future Outlook and Action Guidelines for Using Parking Accounts
Going forward, the terms of demand deposit products will continue to change according to market interest rate volatility, and competition among financial institutions is expected to become even fiercer. For those trying to wisely hold cash while waiting for investment opportunities, parking accounts will remain an indispensable financial tool. Developing the discernment to find the most favorable conditions among numerous product options is a core competency in modern financial life. Today, search for the latest interest rate information from your main bank or a savings bank and move your dormant funds to a place where they work harder. It is important to act now because even small interest differences can accumulate into a significant asset over a long period. Wise asset management does not start with grand stock investments but with the very small action of changing just one account.
Since the role of parking accounts in short-term fund management will remain important, active information seeking and execution are necessary.
Frequently Asked Questions
=