A parking account is a deposit product that allows free deposits and withdrawals, earning interest even if funds are held for just one day. It is the most suitable financial product for managing short-term funds that you don’t need immediately but don’t want to lock away either. With recent increases in the base interest rate, commercial banks and savings banks are aggressively competing to offer various high-interest parking account products, meaning you can secure much more favorable terms with a little effort. Last year, Mr. Kim, an office worker, left his holiday bonus in a regular demand deposit account and was disappointed to receive only a few tens of won in interest. If he had transferred the money to a high-interest parking account or a Comprehensive Asset Management Account (CAMA) at the time, he would have earned enough interest to treat himself to a few chickens. In this article, we will carefully compare parking account interest rates across various financial institutions and explore practical methods to maximize your interest earnings.
=
Parking Account Interest Rate Comparison & Recommendations: Essential Strategies for Short-Term Fund Management
1. Definition and Basic Operating Principles of Parking Accounts
Like parking a car temporarily, parking accounts allow you to deposit and withdraw funds at any time, eliminating the need to worry about early withdrawal penalties common with regular deposits. While standard salary or demand deposit accounts offer near-zero interest rates of around 0.1% annually, parking accounts have the remarkable advantage of calculating and paying interest on a daily basis. For example, if you deposit money in the morning for an urgent need and withdraw it in the evening, the daily calculated interest earned during that period is credited directly to your account. This is why office workers can safely store holiday bonuses or emergency funds worth millions of won while still expecting modest interest income. Thanks to this structure, parking accounts have become extremely popular as a temporary holding place for idle funds before investing in complex financial products.
Many people view parking accounts simply as demand deposit accounts with slightly higher interest, but they also serve as a shield for protecting your money wisely. When the stock market is too volatile to enter immediately and real estate lacks liquidity, parking accounts become the safest alternative. Since you can complete everything from account opening to management with just a few taps on a banking app, they are perfect for those who dislike complex procedures.
Parking accounts are financial products optimized for short-term fund storage, offering the flexibility of frequent deposits and withdrawals along with daily interest accrual.
2. Recent Interest Rate Hikes and Parking Account Trends

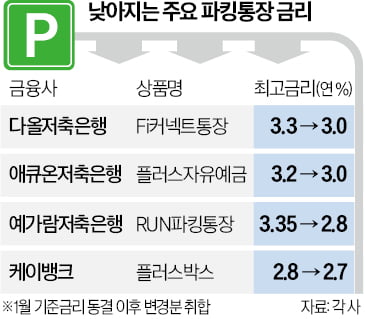
As the Bank of Korea’s base interest rate has been raised consecutively, competition for deposits among commercial banks and savings banks has become fiercer than ever. Banks are continuously raising parking account interest rates to secure customer deposits, with some products offering exceptional terms of up to 7% or 8% annually. Last year, Mr. Park, who deposited his savings in a savings bank, was delighted to see his account balance grow due to unexpectedly high interest rates, finding great joy in checking his interest monthly. The value of products that allow you to safely earn interest shines brightest when financial market volatility is high.
Of course, the high maximum interest rates touted in media reports and advertisements often come with hidden conditions, requiring a cool-headed assessment. Most high-interest parking accounts have deposit limits, and any balance exceeding that limit is subject to a significantly lower base interest rate. For instance, if you deposit 100 million won in an account advertised at a maximum of 8% annually, the high rate may only apply to the first 300,000 won, while the remainder earns just 0.1% annually, leading to disappointment. Therefore, it is wise to carefully examine the limit conditions that match your fund size rather than opening an account based solely on surface numbers.
While parking account interest rates have risen due to base rate hikes, you must always verify the deposit limits to which high interest rates apply.
3. The Trap of Limits Hidden Behind Surface Interest Rates
If you browse internet communities or wealth management cafes, you will easily find posts from people who switched to parking accounts based solely on the highest advertised interest rates, only to be frustrated by the surprisingly low actual interest received. This is because behind the flashy marketing slogans of banks, there are often stringent preferential conditions or extremely low deposit limits. Mrs. Lee, a housewife, was attracted by the phrase “up to 4% annually” and moved all her money from her existing account, but the interest she received after a month was much less than expected. Upon closer inspection, she found that earning the preferential rate required specific card usage records or meeting salary transfer conditions.
To avoid such disappointments, it is essential to accurately compare your total available funds with the preferential interest conditions offered by the bank. If your funds are very small (under 300,000 won), products with low limits but exceptionally high interest rates are advantageous. However, if you have funds in the tens of millions of won, choosing a product with a generous limit is more beneficial. If you find it troublesome to meet complex conditions, selecting a major commercial bank’s primary parking account with a solid base interest rate and relatively generous limits is a peace-of-mind option. Rather than blindly following recommendations, you need to critically reflect on your actual financial consumption patterns to make a choice.
Chasing only high interest rates can reduce effectiveness due to low interest rates on amounts exceeding limits or stringent preferential conditions.
4. Comparison with Comprehensive Asset Management Accounts (CAMA) and Selection Criteria
When managing short-term funds, the Comprehensive Asset Management Account (CAMA) offered by securities firms is often cited as the other major pillar alongside parking accounts. While bank parking accounts are safely protected up to 50 million won in principal and interest under the Deposit Insurance Act, some CAMAs may not be covered by deposit insurance depending on the product type, requiring caution. Mr. Choi, a university student preparing for stock investment, expressed satisfaction with the convenience of his securities account, noting that he could watch his interest grow daily, which he found more convenient than a bank. However, for conservative investors who prioritize safety, parking accounts at commercial banks or savings banks, which are state-guaranteed, provide much greater peace of mind.
Since these two products differ in the entity managing the funds and their operational methods, you should wisely allocate your funds according to your investment style and goals. The standard approach is to keep emergency funds or living expenses, which you may need at any time, in a safety-guaranteed parking account, while keeping idle funds waiting for stock trading opportunities in a securities account. Recently, securities firms have also been actively competing to attract customers by offering competitive rates for idle funds, making it enjoyable to frequently compare interest rate conditions on both sides. Rather than putting everything into one, a strategy of diversifying deposits according to the nature of the funds is the shortcut to reducing risk and maximizing returns.
Parking accounts excel in the safety of deposit insurance, while CAMAs offer advantages in stock linkage and convenience; choose based on your specific purpose.
5. Practical Strategies for Utilizing Holiday Bonuses and Idle Funds
As holiday seasons like Chuseok or Lunar New Year approach, office workers’ accounts see a temporary lump sum formed by the deposit of bonuses and allowances. Leaving this money in a regular demand deposit account at your primary bank only benefits the bank, so you should immediately transfer it to a high-interest parking account. Mr. Jeong, an office worker, immediately deposited his holiday bonus into a short-term high-interest account and withdrew only what he needed, earning significantly more interest income than usual. This habit of keeping money working, even for short periods, accumulates to become the secret to growing assets faster than others.
When managing idle funds, you should develop a comprehensive strategy that utilizes not only parking accounts but also accounts that offer tax benefits. It is wise to send funds needed for just a few days to a parking account and diversify funds intended to be held for over a year into products with excellent tax-saving effects. Actively utilizing special products or event interest rate benefits offered by financial companies around holidays can help you earn an additional 0.5% in interest compared to others. Small interest differences accumulate to create significant asset gaps later on, so you must stay interested in financial information and act diligently.
Do not leave holiday bonuses or short-term idle funds untouched; immediately transfer them to a parking account to maximize daily interest benefits.
6. Final Recommendations for Successful Fund Management
To survive in a financial market characterized by rising interest rates and high volatility, you must establish your own fund management principles that are not swayed by hearsay. A parking account is ultimately a means to safely store short-term funds and earn decent interest, not a primary investment for long-term wealth accumulation. As favorable products will continue to change monthly according to policy shifts by financial authorities and trends in market interest rates, consistent attention is required. You should regularly read expert analysis articles and cultivate the discernment to find the optimal account that perfectly matches the size and nature of your funds.
Start today by opening your bank account and carefully checking how much money is lying dormant. Investing just one minute to transfer your account will change the interest figures appearing in your account and significantly increase the joy of saving. Never forget that wise financial life begins not with distant goals, but with the small habit of not letting even a single penny go to waste. We sincerely hope that you will use parking accounts as a reliable companion to safely and robustly grow your valuable assets on your upcoming journey of asset formation.
Parking accounts are an excellent tool for short-term fund management; practice continuous interest rate comparison and wise diversification.
Frequently Asked Questions
=