To manage your pension account wisely, it is crucial to choose a system that aligns with your salary growth rate and investment preferences. Rather than blindly following colleagues who have achieved high returns, you must accurately assess your working conditions and retirement plans to avoid failure. While working life naturally leads to an interest in pension accounts, many people feel overwhelmed when it comes to how to manage them effectively. In this article, we will examine in detail the differences between Defined Benefit (DB) and Defined Contribution (DC) plans, as well as how to utilize the recently improved physical transfer system. To enjoy the satisfaction of watching your pension assets grow steadily, like your monthly salary, you need to solidify your understanding of the system’s fundamentals right now. Instead of complex financial jargon, we will explain everything using everyday examples so that anyone can easily understand.
=
Physical Transfer of Pension Accounts and Account Selection: Everything Employees Need to Know
1. The Exact Differences Between Defined Benefit and Defined Contribution Plans
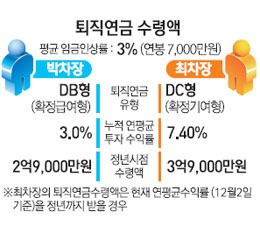
The most confusing aspect for employees is comparing the pros and cons of Defined Benefit (DB) and Defined Contribution (DC) plans. A DB plan is similar to the traditional severance pay system, where the employee receives an amount calculated by multiplying their average salary over the last three months by their years of service. Therefore, for employees whose salaries rise steadily every year, a DB plan offers a much more favorable structure. On the other hand, a DC plan is a system where the company deposits at least one-twelfth of the total annual payroll into the employee’s individual account, and the participant manages the investments directly. If you are an employee interested in investing or during a period of stock market growth, you can expect higher returns by investing directly in equity products or index funds through a DC plan. For example, Mr. Kim, a junior staff member who joined the company at the same time as others, maintains a DB plan because his salary rises sharply in his role, while Manager Lee chose a DC plan because he prefers to select and hold specific stock or bond products himself. By carefully comparing your salary increase rate and investment style, you can make a choice without regret. Finding a balance between the company’s support method and your own asset management ability is the first step in preparing for retirement.
Employees with high salary growth rates benefit from Defined Benefit plans, while those who prefer direct investing are better suited for Defined Contribution plans.
2. Utilizing the Recently Introduced Physical Transfer System for Pensions
In the past, transferring a pension account to another financial institution was cumbersome because existing products had to be fully liquidated into cash. This process often resulted in early termination fees or losses due to missing the optimal selling timing. However, the physical transfer system has now become established, allowing you to switch financial institutions while keeping your held products intact, making the process much more convenient. If you are dissatisfied with the mobile app or customer service of your current financial institution, you can easily move to another. Once you decide to transfer, you first need to open an account at the new financial institution, either in person or non-face-to-face, and then submit a transfer application. This typically takes about three business days, so it is advisable to calculate the period during which your funds will be tied up in advance. However, for Defined Contribution (DC) participants, there is a restriction that they can only move within the “fence” of financial institutions that have a group contract with their employer. Therefore, to reduce confusion, you must accurately understand the difference between Individual Pension Plans (IRP), which allow free movement, and DC plans.
Using the physical transfer system allows you to easily move to your desired financial institution without liquidating your products.
3. Setting an Appropriate Ratio of Safe and Risky Assets

Since a pension account holds valuable retirement funds, maintaining stability is more important than aggressive investing. According to relevant regulations, a certain percentage of the total accumulated funds must be allocated to safe assets. Recently, hybrid products that meet the mandatory safe asset ratio while allowing investors to benefit from the growth of major U.S. stock markets have gained significant attention. Young employees with a long time until retirement should maintain an appropriate equity allocation to defend against long-term inflation. Conversely, employees close to retirement should focus on protecting their assets by increasing the proportion of principal-and-interest guaranteed products or government bond-linked products. In reality, Mr. Park, a department head who carefully adjusted his asset ratios, maintained composure and recorded stable returns even when the market fluctuated significantly. On the other hand, Mr. Choi, a junior staff member who left his account unmanaged without a plan, suffered from unnecessary fees and returns that fell below the inflation rate. It is necessary to diligently review your portfolio regularly and adjust your asset allocation according to market conditions.
You should periodically adjust the ratio of safe and risky assets according to your retirement timeline and investment style.
4. Maximizing Tax Deductions and Low-Rate Taxation Benefits
When preparing for retirement, the final profit or loss varies greatly depending on how well you utilize tax benefits. Depositing funds into an Individual Pension Plan (IRP) account allows you to enjoy valuable tax deductions during year-end tax settlement. While interest earned in a regular account is subject to a significant interest income tax, profits generated within a pension account have their taxation deferred until they are received as a pension. Even when receiving the pension after retirement, a much lower pension income tax rate is applied compared to general tax rates, significantly reducing the tax burden. Purchasing government bonds for individual investors linked to a pension account is an excellent alternative that offers both stability and tax benefits. When discussing year-end tax settlements with acquaintances, it is common to see some people getting refunds of several hundred thousand won while others end up paying more tax. A significant part of this difference stems from how actively they utilized their pension accounts. Even if you cannot max out the annual contribution limit every year, consistently adding funds whenever you have surplus cash is the shortcut to tax savings.