U.S. Treasuries, long considered a safe haven in the global economy, are seeing their status waver as they face neglect from foreign central banks and governments. Recent data indicates that the share of U.S. Treasuries held by the foreign public sector has fallen to its lowest level since 1993, signaling a massive structural shift. Bonds that were once fiercely competed for by governments worldwide to bolster their foreign exchange reserves have now lost much of their allure. While the U.S. government continues to issue massive amounts of debt to cover fiscal deficits, the primary buyers have completely shifted from the public sector to private speculative funds. This article will examine the specific background behind this phenomenon and its potential ripple effects on global financial markets. We will focus on the core content to help readers easily understand the complex flows of international finance.
=
Shifts in the U.S. Treasury Market: Losing Appeal to Foreign Central Banks and Governments
1. The Exodus of the Foreign Public Sector and the Plunge in Holding Shares
A review of the latest funding flow statistics released by the U.S. Department of the Treasury reveals a consistent downward trend in Treasury holdings by foreign central banks and governments since the start of the year. As of last July, the market value of bonds held by these entities had plummeted to $3.77 trillion, a level roughly comparable to that of 2012. Considering that the total U.S. Treasury balance nearly tripled during the same period and cumulative inflation reached 48%, actual interest has decreased significantly. During the financial crisis, the foreign public sector accounted for over 38% of the total marketable Treasury market, but this figure has now plummeted to 12.8%. This represents the lowest level in history since 1993, indicating a complete change in intergovernmental trust and asset valuation. Central banks, observing the U.S. government’s reckless fiscal management and uncertain interest rate policies, are no longer blindly buying Treasuries. Total foreign holdings, combining both public and private sectors, are also failing to escape a declining trend, hitting structural limits as of July. Compared to past crisis scenarios where the U.S. government issued massive new debt in the short term and the central bank bought it in bulk, the current decline in foreign dependence is very distinct. While long-term bonds make up the majority of holdings and short-term bonds fill the rest, the exit of the core buyers has left a vacuum that translates directly into risk exposure. The U.S. is now in a position where it must rely on private financial capital rather than the wallets of traditional allied governments to absorb its national debt. This change is interpreted not merely as a statistical fluctuation but as a significant signal hinting at how the international monetary order will be restructured in the future.
The share of U.S. Treasuries held by foreign central banks and governments has fallen to its lowest level since 1993, indicating a sharp decline in traditional demand.
2. The Rise of Opaque Overseas Financial Hubs and Hedge Funds
Filling the void left by the public sector are assets of U.S. hedge funds and corporations registered in overseas financial hubs, which are difficult to view as purely foreign capital. The figures classified as foreign private holdings include massive speculative transactions by U.S. capital that has established entities offshore. Notably, the Cayman Islands are a preferred region for hedge funds that favor “basis trades”—buying bonds using high leverage and selling futures. The scale of bonds manipulated in the market through such methods reaches the trillions of dollars, strongly characterized by short-term speculative funds. In the past, such massive leveraged funds caused significant shocks to the market, giving central banks a scare, but the current scale is incomparable to those times. The seat that should guarantee the stability of the Treasury market is now filled with the speculative funds of highly volatile hedge funds. Major U.S. corporations also frequently accumulate massive cash in overseas entities, such as in Ireland, to save on taxes and then reinvest it in U.S. Treasuries. Past congressional investigations also put these offshore fund management structures of famous companies under scrutiny, with pharmaceutical and technology companies joining the trend. Because the statistical aggregation method is based on the country of entity registration rather than the actual source of funds, it creates an optical illusion where U.S. capital is counted indirectly. The combined Treasury holdings of seven major overseas financial hubs easily exceed one-third of total foreign holdings, acting as a massive reservoir. Traditional financial hubs like London and Brussels, along with regions with tax haven characteristics, have become the main bases supporting U.S. debt.
Foreign private holdings largely include funds from U.S. corporations seeking tax avoidance and hedge funds engaging in high-risk leveraged trades.
3. Japan’s Yen Defense and Large-Scale Treasury Sales
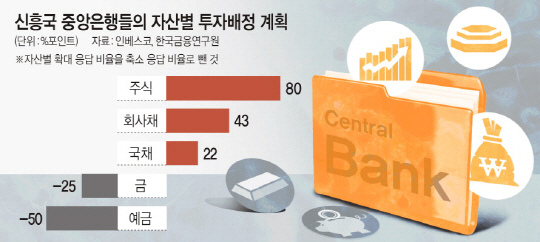
Japan sold off a large portion of its U.S. Treasuries while intervening in the foreign exchange market to prevent a sharp decline in the value of the yen. It had to execute operations to sell dollars and buy yen to support the rapidly falling exchange rate, and to secure the necessary cash, it liquidated its Treasuries. This sale of Treasuries by the Japanese government ultimately resulted in significant exchange rate gains, as the bonds had been purchased when the yen was strong. Selling the bonds at the current point, when the yen’s value has dropped significantly, to secure dollars and then convert them back into yen resulted in holding much more capital. Most of the sold bonds were close to maturity and were received at prices close to face value, minimizing principal losses due to rising interest rates. Within Japan, active discussions are ongoing regarding how to utilize the massive profits gained from these Treasury trades. Options ranging from supplementing the national budget to using the funds for specific policy expenditures are on the table, giving this move significance beyond simple asset management. This case proves that Japan, once one of the world’s largest bond holders, can sell U.S. bonds at any time according to its domestic monetary policy needs. From the perspective of the U.S. Treasury, this movement acts as a major burden for absorbing debt, showing that even allies can turn their backs at any time if their economic interests diverge. Japan’s actions are becoming a 21st-century textbook for finance, strongly suggesting to other nations the need for foreign exchange reserve diversification and asset reallocation.
Japan sold large amounts of U.S. Treasuries to intervene in the foreign exchange market to defend against a sharp drop in the yen, securing exchange rate gains.
4. China’s Continuous Reduction and the Exodus of Major Nations
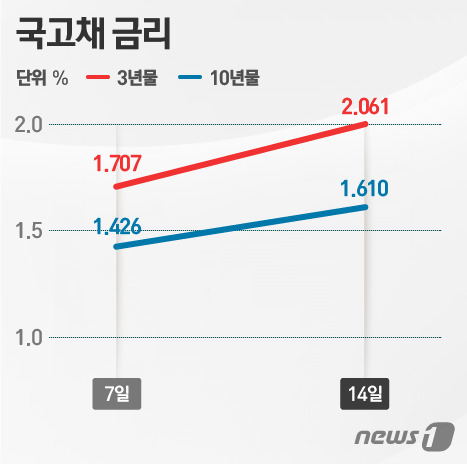
Mainland China and Hong Kong are steadily selling off U.S. Treasuries for several years, moving away from their past massive holding scales and noticeably reducing their share. Even in the last year, significant volumes have disappeared from the market, and the reduction compared to their peak levels has snowballed. China’s share of the outstanding marketable U.S. Treasury balance has dropped to around 3%, making its former status as a bond king hard to find. As geopolitical tensions between the U.S. and China deepen and concerns over asset freezes or sanctions grow, China is lowering its share of dollar assets and turning its eyes to gold or other safe assets. Experts commonly diagnose that this structural selling pressure is not a temporary phenomenon but has established itself as part of a long-term de-dollarization trend. The movements of other major advanced and emerging nations are not vastly different, with countries like Canada and France also showing significant fluctuations and decreases in holdings. In Canada’s case, there were sharp drops in holdings at specific points, with significant data fluctuations caused by both changes in investment strategy and technical factors in statistical aggregation. France, due to the specific nature of its banking system, experiences frequent capital inflows and outflows, and after recording all-time highs, it immediately underwent a significant correction. Countries like Taiwan and Norway are also revising their foreign exchange reserve management strategies, either lowering their dependence on U.S. Treasuries or weighing specific reduction plans. As major global economic actors collectively shift toward reducing the weight of U.S. Treasuries in their portfolios, the U.S.’s solid backing is disappearing.
China has been selling Treasuries for years to avoid geopolitical risks, and other major nations are also trending toward reducing their holding shares.
5. The Enlarged Role and Illusion of Specific Financial Hubs
The total U.S. Treasury holdings of seven major overseas financial hubs where global funds converge exceed $3.28 trillion, accounting for a massive pie of the total. The London financial district in the UK, living up to its reputation as the world’s largest capital market, holds bonds reaching $1 trillion and serves as a center for actual transactions. Following this, Belgium nominally holds a massive amount of Treasuries due to its special status as the home base of Euroclear, Europe’s giant payment system. Regions like the Cayman Islands, Luxembourg, and Ireland also boast bond figures ranging from tens to hundreds of trillions of won, effectively serving as stops for global funds. Switzerland and Singapore are also listed as major hubs collecting money from asset holders and institutional investors to buy U.S. Treasuries. However, the prevailing view is that it is difficult to take the massive holding figures of these financial hubs at face value as a sign of pure national trust. This is because the ultimate owners of accounts registered in these regions are often major U.S. hedge funds or global multinational corporations. By setting up paper companies or offshore entities to save on taxes or avoid regulations and buying bonds in their names, they become the main culprits behind statistical illusions. These are not assets bought by genuine foreign governments or central banks trusting the U.S. economy, but rather resemble short-term speculative capital or corporate retained earnings in disguise. As a result, the U.S. Treasury market has taken on a structure like a sandcastle, sensitive to market liquidity and speculative sentiment rather than being based on the solidity of the real economy.
The massive Treasury holdings of overseas financial hubs like the UK and Belgium are often actually indirect assets of U.S. hedge funds or corporations.
6. Future Outlook for the U.S. Treasury Market and Investor Responses
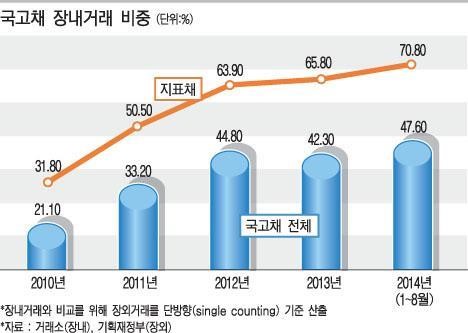
Amidst two massive trends—the exodus of the foreign public sector and the inflow of speculative private capital—the U.S. Treasury market faces higher volatility than ever before. The phenomenon where long-term Treasury yields do not move as expected or the market panics, even when central banks adjust interest rates, stems directly from these structural changes. The U.S. government will continue to issue Treasuries endlessly to cover massive fiscal deficits, but the reliable allied governments that used to absorb this debt stably are increasingly closing their wallets. Instead, the short-term funds of leveraged hedge funds filling that void are like a bomb that could lead to a panic sell-off at any time in a crisis. Individual investors and general corporations must accurately understand these macroeconomic cracks and prepare for sharp fluctuations in bond yields or the possibility of transmission to the stock market. Ultimately, the process of U.S. Treasuries, the synonym for safe assets, losing their past absolute credit can be seen as a precursor to a tectonic shift in the global capital market. The movement of nations to lower their dependence on dollar hegemony and diversify assets will completely change our perspective on the financial market. Between indiscriminately issued debt and central bank policies losing control, investors must read market signals more nimbly. It is time to realize that complex international financial news is not just a list of numbers but a core indicator determining the fate of our assets, and to establish thorough preparation plans. To survive in the coming era of uncertainty, we must cultivate the insight to see through the actual flow of capital, rather than relying solely on traditional common sense.
The Treasury market, left by the public sector, has seen increased volatility due to the growing influence of speculative funds, requiring careful attention from investors.
Frequently Asked Questions
=