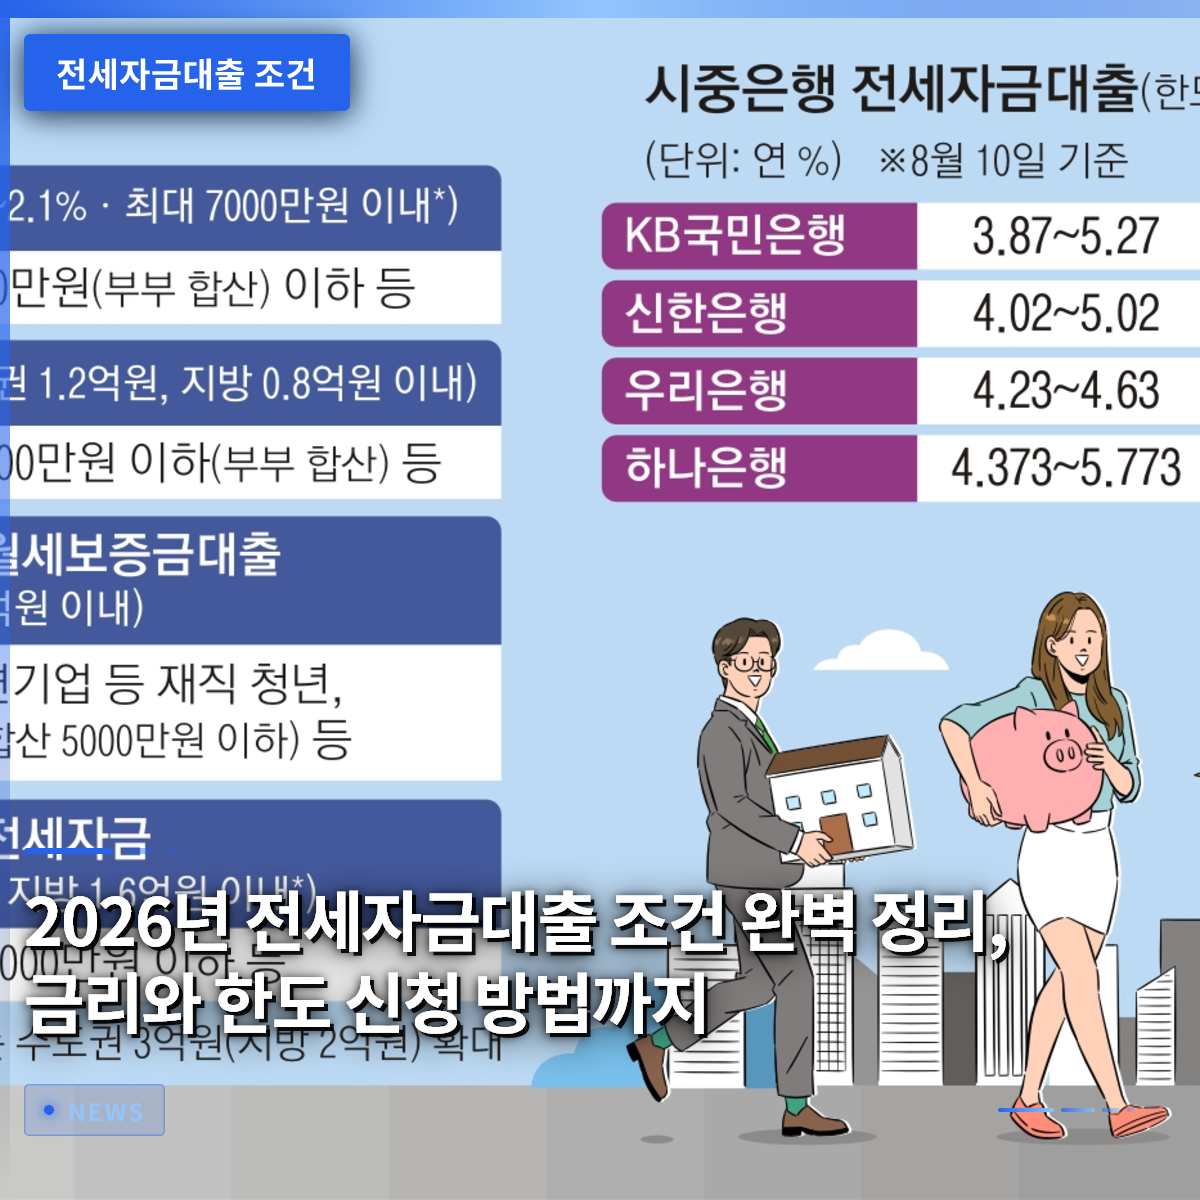
As of 2026, to obtain a Jeonse (lump-sum deposit) loan, you must meet all criteria regarding the home-ownership status of both you and your spouse, income requirements, and the deposit amount and area limits of the target property. Kim Min-su, an office worker who got married last year, nearly lost his deposit because he misunderstood the deposit criteria while house-hunting. Many people think the process ends once they apply for the loan, but in reality, many lose their earnest money because they fail to meet the specific eligibility requirements. This article explains how to clearly understand the practical loan conditions and limits that bank tellers often keep to themselves. If you read to the end, you will find opportunities to protect your valuable deposit and cut your interest burden in half. Let’s break down these complex conditions one by one, clearly and simply.
=
2026 Jeonse (Lump-Sum Deposit) Loan Conditions: A Complete Guide to Interest Rates, Limits, and Application Methods
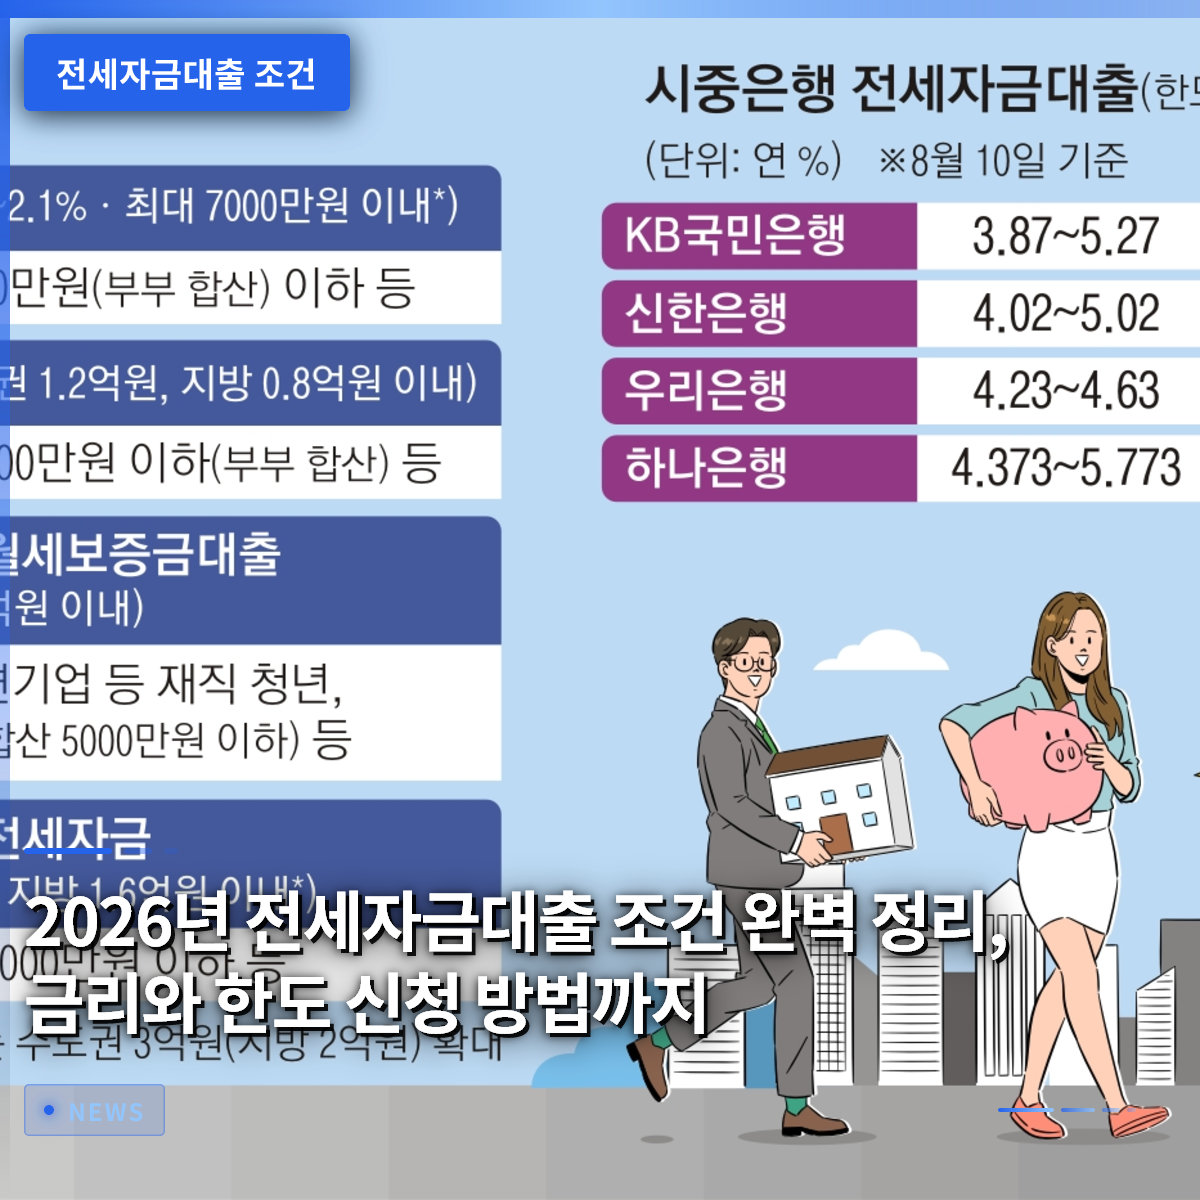
1. Basic Eligibility and Non-Homeowner Criteria
The fundamental principle for applying for a Jeonse loan is that all members of the household must be non-homeowners. If you are a young person living with your parents, you need to carefully check your parents’ home-ownership status, which can be a headache. Even if you owned a home in the past, if you have already sold it, this can work in your favor when calculating your period as a non-homeowner. During the bank’s review process, you must submit resident registration certificates for the head of the household and all members to strictly prove your non-homeowner status. Practically, if you are a couple about to get married, you may receive special benefits if you secure a home within a certain period based on your scheduled wedding date. Some of my friends didn’t know this and ended up paying high interest rates on standard products, only to struggle later when switching to a more suitable one.
Thorough document preparation is the most critical key to determining whether your loan is approved. The certificate of employment and income certificate issued by your company determine your loan limit, so you should obtain and verify them in advance. If you are a freelancer or a business owner, your average income over three years is used as the basis, which is completely different from the calculation method for salaried employees. It is safe to double-check that the documents issued by the National Tax Service’s HomeTax system match the documents submitted to the bank. Occasionally, income is estimated based on National Health Insurance premium payment records, so if you have any delinquent payments, you should resolve them in advance. Do not give up just because you do not meet the conditions; you need the wisdom to restructure your eligibility through family consolidation or separation.
Maintaining non-homeowner status for all household members and providing accurate income proof are the basic prerequisites for loan approval.
2. Property Requirements and Area/Deposit Limits

Eligible properties for the loan must have a floor area of 85 square meters or less and a Jeonse deposit below a certain amount. The deposit cap varies between Seoul, the metropolitan area, and local metropolitan cities, so you must check the criteria for your specific region. Many local government support programs only provide benefits if you reside in a property or officetel with a Jeonse deposit of 300 million KRW or less and a floor area of 85 square meters or less. It often happens that when looking for an old multi-house villa or apartment, the area listed on the registered deed differs from the actual area, causing problems. A wise approach is to directly review the building ledger to carefully check for any illegal expansions.
Remember that banks will outright refuse loans if the lease contract is with a relative. Contracts with parents, children, or their spouses are not recognized as eligible for housing support funds. Additionally, for neighborhood facilities or commercial housing, even if converted for residential use, the likelihood of failing the Jeonse loan review is very high. Before depositing the earnest money as a preliminary deposit, you must definitely include a special clause in the contract, through a licensed real estate agent, confirming the possibility of obtaining a loan. If the landlord has tax delinquencies that could cause issues with returning the deposit, the loan application will also be immediately rejected. Thorough verification of the property’s condition is the first step toward successful funding.
You must choose a property with a floor area of 85 square meters or less that does not exceed the regional deposit cap.
3. Youth and Newlywed-Specific ‘Beotimok’ Products
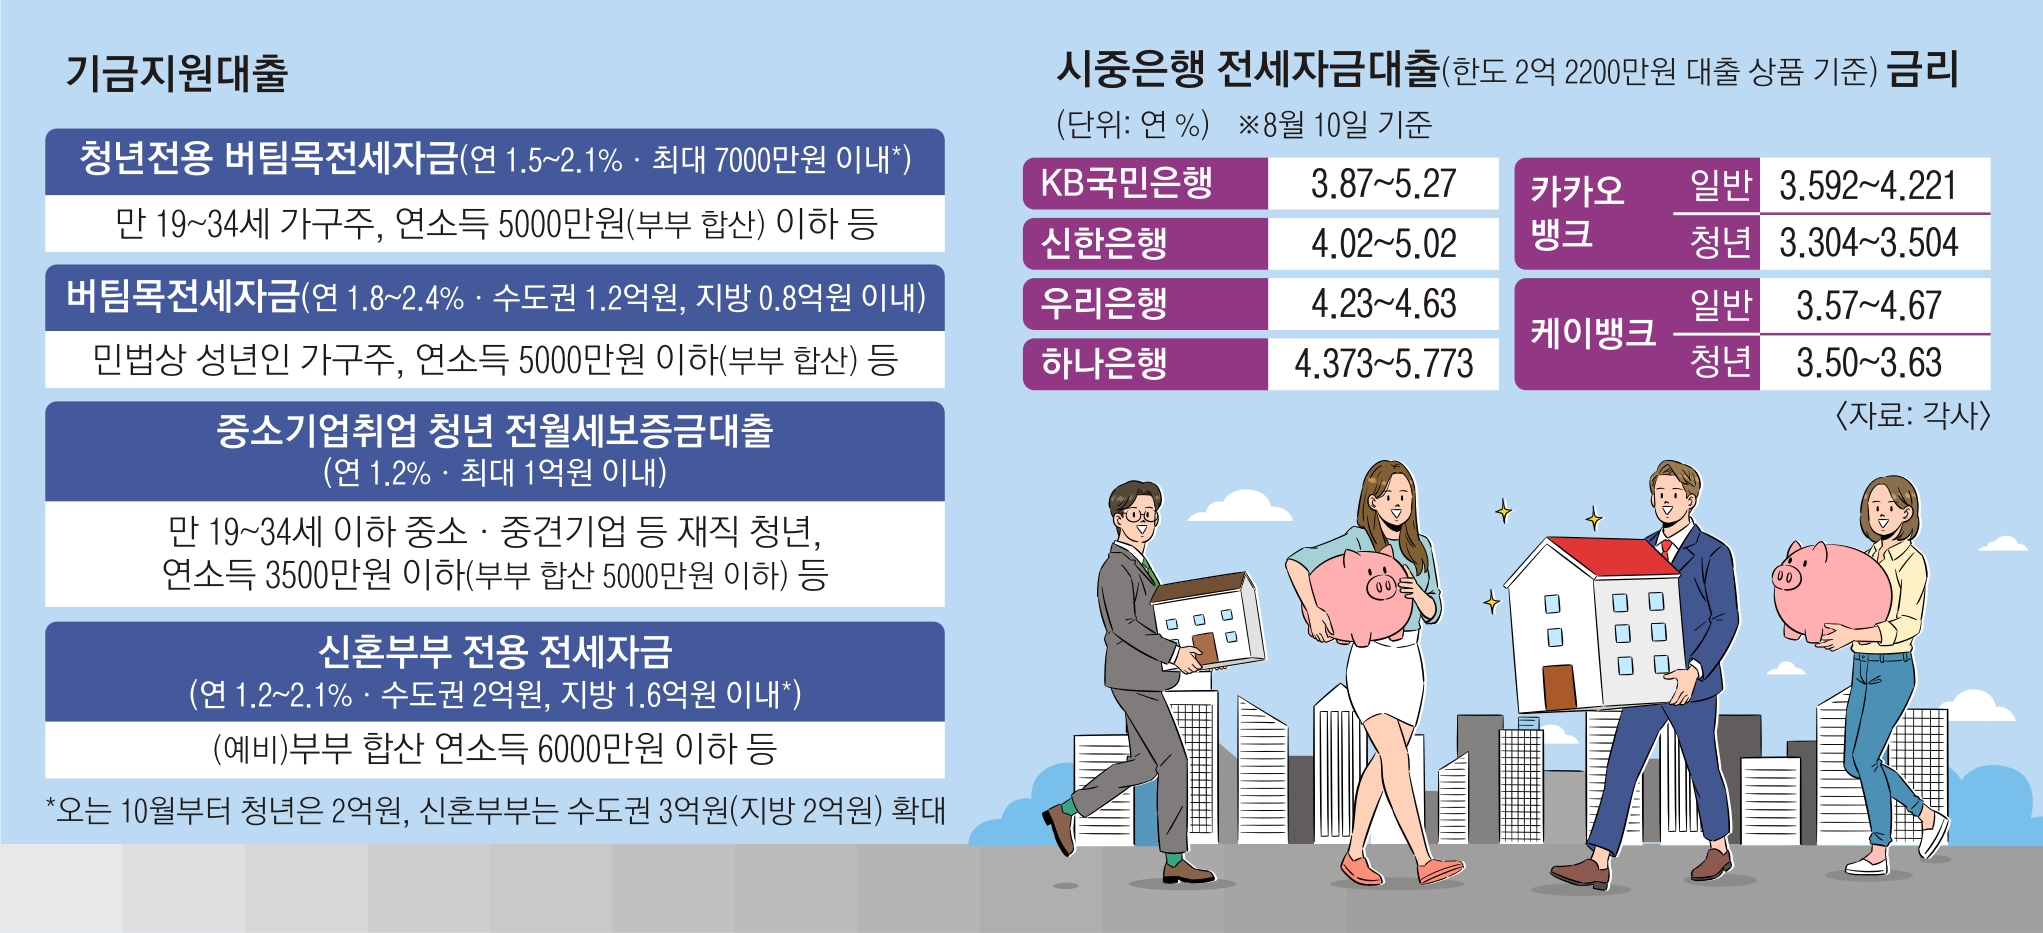
The government-supported ‘Beotimok’ Jeonse loan is very popular because its interest rate is much lower than that of commercial bank products. If you are a young person employed at a small or medium-sized enterprise (SME) or a non-homeowner newlywed couple, you should prioritize these specific policy products over general ones. In fact, a recent graduate I know successfully moved out on their own, paying only half the interest rate of a standard loan by using the Youth Beotimok product. Interest rates are applied differently based on income brackets, and youth employed at SMEs receive additional preferential interest rate benefits, significantly reducing the burden. However, since fund loans have set limits and may close early once the budget is exhausted, it is essential to check the application period in advance.
Accessibility has improved significantly as more products can be applied for easily and non-face-to-face through internet and commercial banks. You can check your estimated limit and interest rate in just a few minutes by opening a smartphone app and entering a few pieces of information. However, if any omissions are found during the document verification process, you will eventually have to visit a branch, so it is better to prepare properly from the start. For youth-specific products, age limits and re-application conditions based on life stages are strict, so you must calculate your age accurately. Your eligibility is not immediately revoked just because your income increases slightly, but you will face a strict review at the time of renewal. Since the detailed guidelines for government support systems are frequently revised, you should make it a habit to check the latest information on official websites.
Youth and newlyweds should utilize government-supported fund products that offer significantly lower interest rates than general loans.
4. Utilizing Local Government Interest Subsidies and Additional Benefits
Many local governments, including Jeonju City, are actively implementing Jeonse loan interest subsidy programs to reduce housing cost burdens. This method directly subsidizes a certain amount of interest monthly to households that have received a bank loan and meet actual residency requirements. Note that overlapping support may be restricted if you are a recipient of basic livelihood or medical benefits, or if you reside in public rental housing. You can find many hidden benefits by carefully reviewing the announcements posted on the websites of your district office or community center every month. If it is difficult to find information on your own, it is also a good idea to contact a housing welfare center directly to get recommendations for support programs suitable for you.
If you miss the application period for an interest subsidy program, you may have to wait a whole year, so it is a good idea to mark the schedule on your calendar in advance. When applying, you must submit documents such as the lease contract, loan transaction confirmation, and resident registration certificate all at once. For local government programs with limited budgets, recipients are selected on a first-come, first-served basis or by lower income order, so you need to act quickly. Receiving the subsidy can bring your actual interest burden close to zero, providing significant relief to your household economy. Benefits from the government and local authorities do not come to those who just sit and wait; you must actively seek them out.
Linking with your local government’s Jeonse loan interest subsidy program can drastically reduce your housing costs.
5. Calculating Loan Limits and Comparing Interest Rates
The maximum limit for a Jeonse loan is restricted to a certain percentage of the rental deposit and is ultimately determined by your individual income and credit score. Since the guarantee certificate from the Seoul Guarantee Insurance (SGI) or the Housing and Urban Bank (HUB) is used as collateral, your repayment capacity is evaluated very strictly. If your credit score is low or you have many existing credit loans, you may not get the desired limit, leading to the abandonment of your move. In such cases, you must first pay off existing overdrafts or small loans to lower your debt ratio. Utilizing comparison platform services that allow you to compare interest rates from multiple banks at a glance makes it easy to choose the financial institution offering the most favorable conditions.
As we enter a period of rising interest rates, more people are visibly struggling with the decision between fixed and variable rates. If a future interest rate cut is anticipated, a strategy of maintaining a variable rate for a certain period and then switching is worth considering. Since each bank has different performance criteria for receiving preferential interest rates, you must carefully check conditions such as salary transfers and credit card usage. Your main bank does not necessarily offer the lowest interest rate, so you must put in the effort to find the optimal conditions. Even after executing the loan, you should not neglect to actively exercise your right to request an interest rate reduction to lower your interest burden.
You must maximize your limit and minimize interest through thorough debt management and comparing interest rates from multiple banks.
6. Jeonse Loan Application Process and Precautions
To smoothly execute a Jeonse loan, you must undergo a pre-review before signing the contract and complete the formal application at least one month before the final payment date. Since the loan amount is transferred directly to the landlord’s account, the licensed real estate agent and the bank officer must coordinate perfectly on the day of the final payment. You must complete the move-in registration and obtain the confirmation date on the day of the final payment to gain the right of opposition and safely protect your valuable deposit. If you delay the confirmation date or move-in registration, a disaster can occur where you receive not a single won of your deposit if the house is later auctioned. When filling out the loan documents, you must ensure that the amounts specified in the lease contract and the contents of the earnest money receipt match exactly, without a single discrepancy.
The more volatile the real estate market, the more likely Jeonse loan regulations and conditions are to change at any time, so you must always keep an eye on the latest news. Sighs from people who proceeded with contracts based solely on the real estate agent’s words, only to have their loans rejected and lose their earnest money, are endless. Make sure to include a safety measure in the contract from the drafting stage: a special clause stating that the full earnest money will be refunded if the loan fails. If visiting a bank is difficult, you can conveniently submit documents and wait for approval on weekends using the non-face-to-face electronic contract system. Only thorough preparation and cool-headed judgment are the only shield to safely protect your assets in the midst of the Jeonse crisis. For the future of housing stability ahead, please calmly review the conditions you have learned today once more.
You must complete the application one month before the final payment date and set special clauses in the lease contract to prevent accidents and execute the loan safely.
Frequently Asked Questions
=