If you receive your National Pension five years early simply because you are short on immediate living expenses, you may face a fatal “pension cliff” where you must accept a permanently reduced pension amount for the rest of your life. The early retirement pension system, which allows you to receive benefits before the designated age, has strict eligibility requirements, such as having a contribution period of at least 10 years and not being engaged in income-generating work. Before hastily submitting an application to bridge the income gap after retirement, you must carefully calculate your actual monthly take-home amount and the break-even point to avoid unfair losses. In this article, we will thoroughly examine the precise conditions for early withdrawal, how to calculate the reduction rate, and precautions for re-employment. Do not be swayed by hearsay from friends and acquaintances; instead, start planning your retirement wisely based on your accurate contribution history.
=
National Pension Early Withdrawal: Conditions, Reduction Rates, and How to Calculate the Break-Even Age
1. What is the Early Retirement Pension?
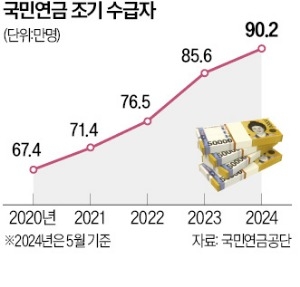
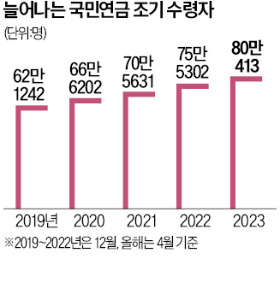
The early retirement pension is a system that allows you to receive public pension benefits up to five years earlier than the designated receipt age. It serves as a lifeline for those who face financial hardship immediately after retirement due to the loss of a primary income source. However, this system is not just about receiving money early; it also carries the serious downside that your monthly pension amount is permanently reduced. In reality, many people who moved to the countryside and had their income cut off often sigh deeply upon seeing their reduced bank balances after applying for early pension receipt at the young age of 59. Therefore, utilizing this system requires the wisdom to objectively compare the economic loss you must bear against the benefits of the cash flow you gain. You must keep in mind that while trying to avoid an income cliff, you might instead fall into an even larger quagmire known as a lifelong pension cliff.
The early retirement pension is a useful system for bridging income gaps, but it has the critical disadvantage of permanently reducing your lifetime pension amount.
2. Strict Application Eligibility and Conditions
There are three strict legal conditions that must be met to apply for the early retirement pension. The first condition is that your total contribution period to the National Pension must be at least 10 years; if you have not met this period, you are ineligible to apply. The second condition is that you must be within five years of your originally designated pension receipt age to submit your documents. The third condition is a strict regulation stating that you must not be engaged in income-generating work or must maintain income below a certain threshold. It is common for people to make unnecessary trips to the office without verifying these conditions. Therefore, the safest method is to first check your accurate contribution history and current income status using a mobile application.
You must meet all three conditions: a contribution period of at least 10 years, being within 5 years of the standard retirement age, and having no income.
3. The Truth About the Up to 30% Reduction Rate

Did you know that for every year you receive your pension early, your original amount is ruthlessly reduced by 6%? If you choose to receive your pension up to five years early, a massive 30% will be permanently deducted from your bank deposits for the rest of your life. For example, a person who would normally receive 1 million KRW per month at the standard age would only receive 700,000 KRW per month if they apply five years early. You might grit your teeth and accept this for one or two years to cover immediate living expenses, but when this accumulates over 10 or 20 years, it results in a huge difference of tens of millions of won. It is a common reality around us where a wife who strongly advised her husband against early withdrawal is left speechless after seeing the notice of the reduced actual take-home amount. Since the reduced pension amount follows you for life at the same reduced rate, even as prices rise, you must make this decision very carefully.
The pension is reduced by 6% for each year of early withdrawal, resulting in a permanent 30% reduction if withdrawn five years early.
4. Calculating the Break-Even Point Compared to Standard Receipt
You must calculate the break-even point between the money you receive immediately from early withdrawal and the larger amount you would receive later under standard conditions. Typically, the total amount received by someone who starts receiving the pension at the standard age overtakes that of the early recipient after approximately 12 to 15 years from the start of early receipt. In other words, if you expect to live significantly longer than the average life expectancy, it is much more beneficial to wait until the standard age to receive the full value. Conversely, if your health is poor or you expect a shorter life expectancy, it may be wiser to receive it early and put cash in your pocket. Rather than being fixated on the idea of feeling like you are losing out, you should make a cold, calculated judgment based on your health status, family history, and post-retirement asset situation. By using an Excel program or the calculator provided by the pension office to crunch the numbers yourself, the most advantageous timing for you will become clear.
It is essential to directly calculate the break-even point between early and standard receipt, considering life expectancy and health status.
5. Re-employment and Income Activity During Early Receipt
Many people worry whether their pension will stop if they unexpectedly find a good job or generate income after starting to receive the early retirement pension. Fortunately, unlike in the past, your pension often does not stop entirely even if you earn income below a certain amount during early receipt. However, if the sum of your pension amount and the labor income earned through re-employment exceeds a certain standard, part of your pension amount may be reduced. Many people who were anxious, thinking their pension would stop the moment they found a job, often sigh with relief once they understand the exact criteria of the system. Therefore, if you are preparing for re-employment or have already started income-generating activities, you must report your accurate income to the office and confirm that you will not face any disadvantages. Since life after retirement is longer than you might think, a flexible asset management strategy that balances pension and labor income is of utmost importance.
Re-employment during early receipt does not stop the pension as long as income standards are not exceeded, but partial reductions based on income should be noted.
6. Alternatives for Successful Retirement Planning
If you want to avoid the painful loss of National Pension reduction, you should cultivate the eye to increase your own income during your pre-retirement working years or utilize various linked systems. There are useful methods such as the recent upward adjustment of the income replacement rate and the deferred payment system, which allows you to extend your contribution period, so it is good to actively use them. Additionally, strengthening your professional skills to secure a good job change or slightly delaying your retirement timing becomes a much more powerful weapon than a simple 10% pension return. Carefully taking advantage of public pension-specific memberships or products offering preferential interest rates from banks is also a small but sure way to grow your retirement assets. Rather than impulsively submitting documents under the pressure of immediate living expenses, seek expert advice and prepare thoroughly through the office’s website. Unwavering economic freedom can only be achieved on the foundation of thorough information and cold calculation.
You should develop a retirement strategy by utilizing various alternatives such as deferred payments or income increases and seeking expert advice.
Frequently Asked Questions
=