Personal pension savings is the most reliable financial tool for preparing a secure retirement while enjoying robust tax benefits during your annual tax settlement. If you have ever felt left behind hearing colleagues receive tax refunds of several hundred thousand won, it is time to open your own account. In fact, simply making consistent monthly contributions can significantly reduce your income tax burden, making it an essential financial product among office workers. When opening an account at a bank or securities firm, it is advantageous to choose securities firm products that allow you to directly select assets such as stocks or bonds. In this article, we will walk through how to maximize your tax deduction limits and tips for managing your account wisely. Let’s take the first solid step toward retirement planning that may have seemed complex, starting today.
=
A Complete Guide to Personal Pension Savings Tax Deduction Limits and Pension Fund Benefits
1. Basic Concepts and Necessity of Personal Pension Savings

Personal pension savings is a representative tax-saving financial product encouraged by the government, helping individuals build their own retirement funds. In youth, concerns about immediate living and housing costs can make retirement feel distant, but the need to secure funds becomes more pressing as time passes. Statistics show that people tend to enjoy a longer period of leisure after retirement than expected, and the National Pension alone may not be sufficient to maintain a basic standard of living. Therefore, additional pension assets prepared according to one’s income capacity are essential, not optional, but a matter of survival. If you develop the habit of making consistent monthly contributions, even in small amounts, you will find that your funds have grown into a substantial lump sum by the time you retire. The quality of life in retirement differs vastly between those who started preparing early in their careers and those who did not. For young professionals or single-person households just starting their investment journey, it is a priority to manage living expenses to secure savings capacity. Setting up automatic transfers of a fixed amount immediately upon receiving your salary can create a forced savings effect. Remember that while friends may appear to enjoy lavish consumption, they might be steadily building retirement assets behind the scenes. What seems like pocket change now can return as significant wealth in 10 or 20 years due to the magic of compound interest. It is wise to set contribution levels that are sustainable according to your economic situation rather than forcing large amounts. Ultimately, this is a structure where the person who persists wins, so the key is to maintain your account consistently without rushing.
Personal pension savings is the most reliable shield protecting your post-retirement life and an essential investment to start immediately.
2. Maximizing Tax Deduction Limits and Tax Savings
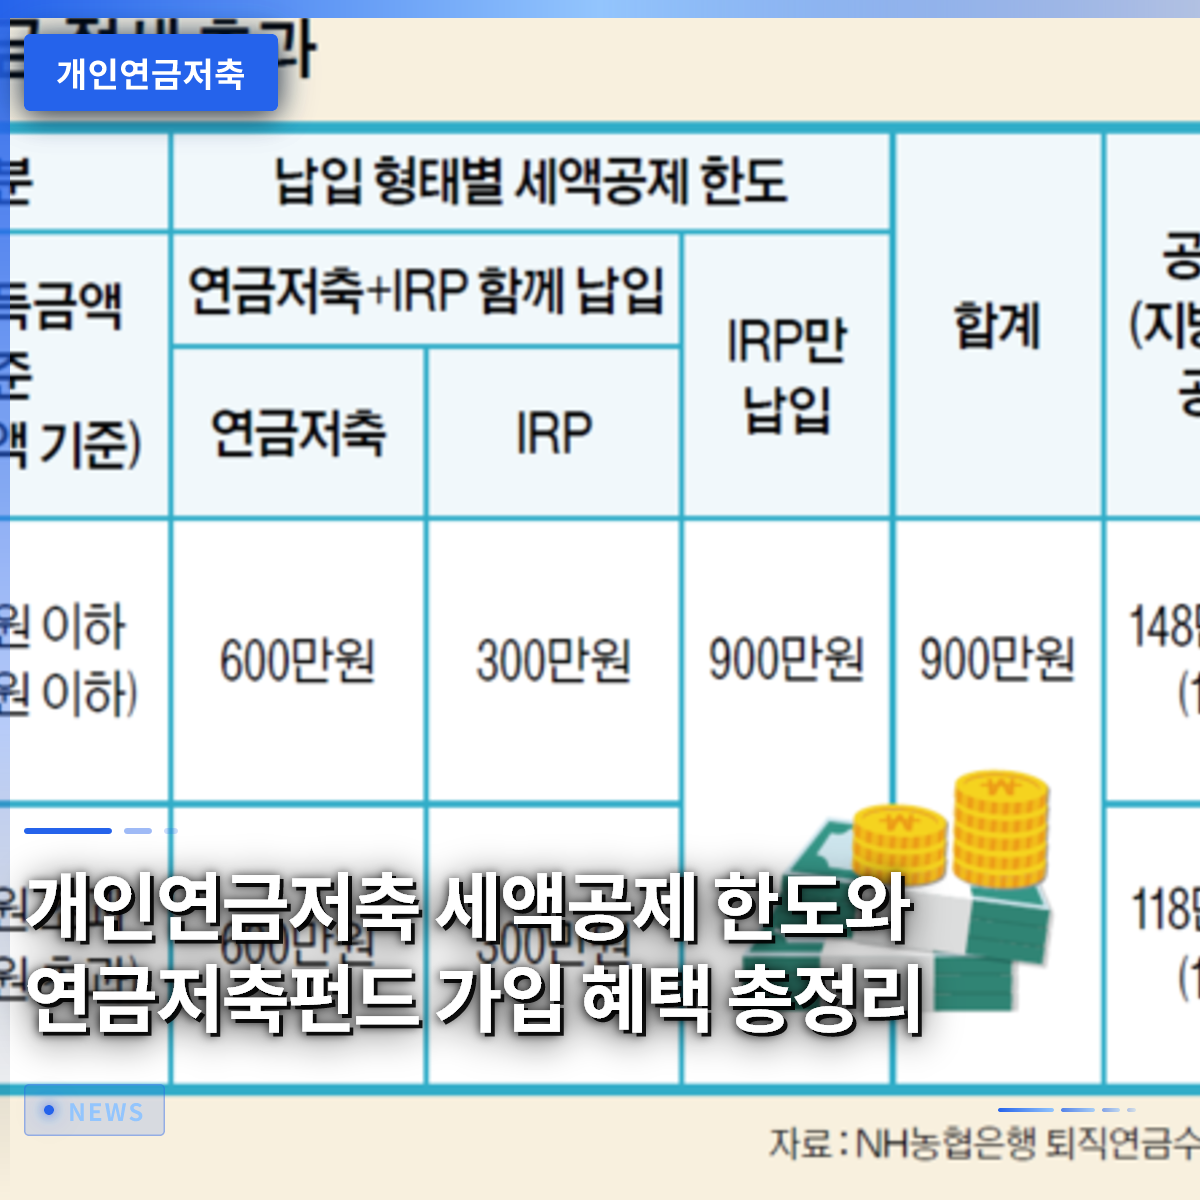
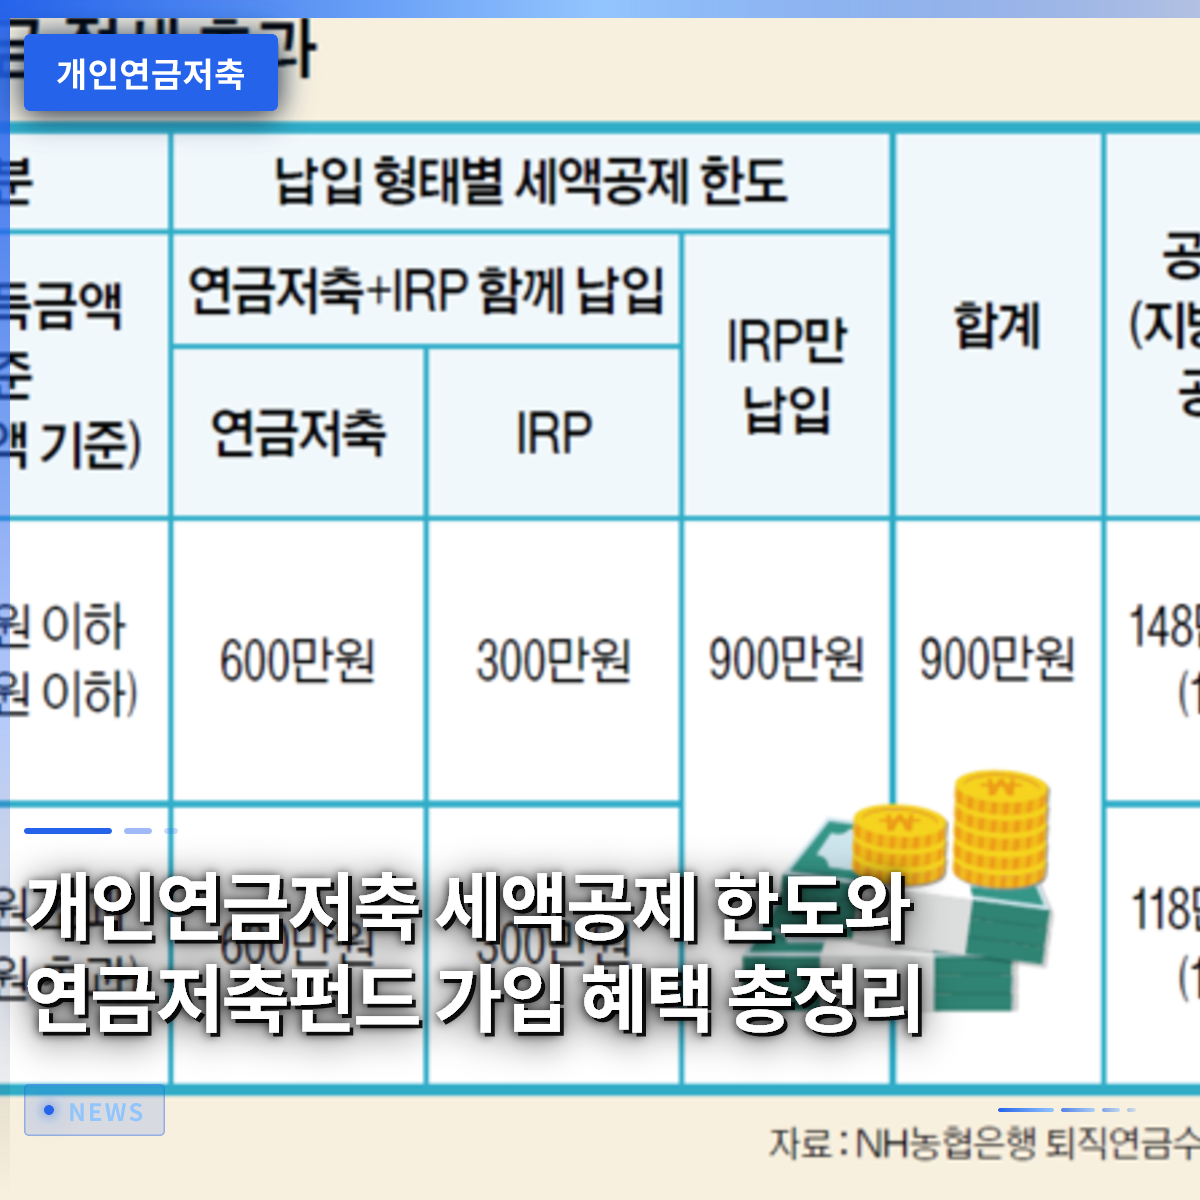
Contributions to pension savings accounts are eligible for tax deductions during the annual tax settlement, making it one of the best tax-saving products for office workers. Currently, under tax law, pension savings alone allows for a maximum deductible contribution limit of 6 million won per year. When combined with an IRP (Individual Retirement Pension) account, the total limit increases to 9 million won. Employees with a total annual salary of 55 million won or less can receive a high deduction rate of 16.5%, resulting in a maximum tax refund of 1.485 million won. Even if your total salary exceeds 55 million won, you can receive a substantial refund through a 13.2% deduction rate, so it is a must for office workers. It is wise to set up automatic monthly transfers to build the foundation for tax benefits throughout the year, rather than rushing to fill the limit at the end of December. As the annual tax settlement season approaches, many office workers hastily make additional contributions to their pension accounts or look for events to increase their refunds. Even if you lack spare cash during the year, making a lump-sum contribution to your pension account when you receive a performance bonus or year-end bonus can help you avoid a tax burden. Utilizing various recurring investment services provided by banks or securities firms allows money to be transferred automatically on your chosen date, accumulating funds without you having to worry. If you reinvest the money received from tax deductions or put it into other savings products, your assets will grow even faster. If you recall the investment adage that saving on taxes is the most certain profit, there is no reason to ignore this account. The person who carefully takes advantage of government benefits wins, so you should check your contribution limit right now.
Pension savings offers tax deductions of up to 6 million won annually, with refund benefits ranging from 13.2% to 16.5%.
3. Differences Between Pension Savings Funds and General Bank Products

Unlike pension savings trusts or insurance products from commercial banks, pension savings funds managed by securities firms offer much more aggressive asset growth. In the past, there was a strong preference for bank products due to principal protection, but with the low-interest-rate environment becoming entrenched, it has become difficult to defend against inflation. Funds or Exchange-Traded Fund (ETF) products purchased through securities firm accounts allow you to ride the growth of the stock market, making them significantly advantageous in terms of long-term returns. By using your monthly contributions to buy ETFs that track domestic and international high-quality companies or indices, you can visually confirm your assets growing steadily. While the lack of principal protection may cause anxiety, given the nature of retirement assets held for over 10 years, a higher proportion of equity assets is necessary to outpace inflation. You may easily see people around you who are afraid of stock investing and bury their money only in bank deposits, but this can be a loss in the long run. Within pension savings funds, you can diversify investments into various global equity or bond assets, naturally lowering risk. If you seek help from asset management experts or utilize AI-based robo-advisor services, your portfolio will be adjusted automatically without you needing to monitor the stock market daily. It is necessary to carefully consider your own investment style and financial goals to finely adjust the ratio between safe and risky assets. Even without complex stock analysis, consistently accumulating stable products that simply track an index is an excellent strategy. Retirement funds are a marathon that must be finished, not a short-distance sprint, so a flexible mindset is essential.
Pension savings funds are accounts that can expect high returns and defend against long-term inflation by utilizing equity ETFs and other assets.
4. Understanding Early Withdrawal and Pension Receipt Rules
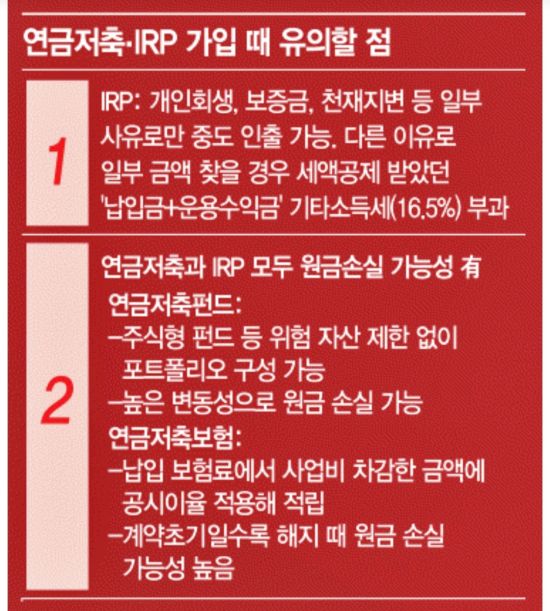
Many people hesitate to join personal pension savings due to the misconception that once money is deposited, it cannot be withdrawn until retirement. Of course, to fully receive tax deduction benefits, you must receive the funds in the form of a pension after age 55, and terminating the account midway requires returning the benefits received. However, there is a system that allows for partial withdrawals without terminating the account in case of an emergency requiring a large sum of money. This applies to reasons stipulated by law, such as purchasing a home for non-homeowners, securing a deposit for a rental, or medical expenses requiring treatment for three months or more for oneself or a family member. In such unavoidable situations, you can secure funds while minimizing tax disadvantages, so you can let go of the worry that the money is strictly locked away. There are also important rules for saving taxes wisely when you start receiving your pension at retirement age. If you receive the pension as a lump sum, it becomes subject to comprehensive income tax, potentially resulting in a heavy tax burden, so it must be received in installments. If you adjust the annual pension amount below a certain threshold, you can pay only a very low pension income tax rate, maximizing the tax-saving effect. The government grants more tax benefits for receiving pensions over a longer period to create a stable cash flow in retirement. Therefore, when planning your post-retirement life, it is wise to calculate in advance the amount of cash entering your account monthly and the tax rate. This is the process of turning the assets you diligently saved in your youth into a reliable source of income that protects you in retirement, similar to a monthly salary.
While pension savings should generally be received as a pension after age 55, early withdrawal is possible under special circumstances.
5. Strategy for Converting ISA Maturity Funds to Pension
Transferring the maturity funds from an Individual Savings Account (ISA), often called a “universal account,” to a pension savings account is known as the ultimate tax-saving strategy. When the contract period of your ISA account, which you have diligently grown with tax-advantaged benefits, ends, do not simply withdraw and spend the money; try transferring it to a pension account. When ISA maturity funds are converted to pension savings or an Individual Retirement Pension (IRP), an additional tax deduction is granted for 10% of the converted amount. This opens up an additional deduction limit of up to 3 million won, allowing you to enjoy a significant tax-saving effect combined with the existing pension savings limit. Office workers who utilize this method take home much higher tax refunds during the annual settlement and grow their assets like a snowball. This linked strategy, recommended by investment experts, becomes the most powerful weapon for young generations in the early stages of asset accumulation. First, you accumulate a lump sum with tax-exempt benefits through an ISA account, and then transfer it entirely to a pension account upon maturity. This not only excludes you from the comprehensive taxation of financial income but also naturally solves your retirement funding needs, achieving a two-for-one effect. Using a securities firm platform makes this asset transfer process very simple, so anyone can easily follow it. Even if you do not know all the complex tax laws, if you remember how to organically link these two accounts, you have already succeeded in half of your investment journey. Please check your calendar for your ISA maturity date right now and plan your pension conversion.
Converting ISA maturity funds to pension savings allows for an additional tax deduction of up to 3 million won, maximizing tax-saving effects.
6. Utilizing the Integrated Pension Portal and Successful Retirement Planning
If you want to grasp and manage all the pension products you have joined at a glance, you should actively utilize the Integrated Pension Portal service operated by the Financial Supervisory Service. From the National Pension to the retirement pension joined at your workplace, and personal pension savings, you can check everything with a single login using a certified digital certificate. It even shows you the estimated amount of pension you will actually receive monthly upon retirement, making it essential for planning your retirement. You can monitor assets scattered across various financial institutions, check if you are preparing well for retirement, and fill in any gaps. Pension assets that were not clearly visible in your youth are clearly visualized through this system, which also helps in boosting motivation. Future financial environments will develop in a direction where artificial intelligence and advanced asset management systems combine to design individual retirements more precisely. Those who identify the most advantageous tax-saving accounts for themselves in line with changing regulations and consistently practice will ultimately achieve financial freedom. We hope you will start with the small action of opening your bank or securities firm app today to check the status of your pension savings account. Small interest and practice will become the most powerful key that determines a comfortable and happy retirement life 10 or 20 years from now. In a complex world, the most certain way to protect and grow your precious assets is to start pension savings now and manage it consistently.
It is important to manage scattered pensions at a glance through the Integrated Pension Portal and complete a systematic retirement design.
Frequently Asked Questions
=