Pension savings insurance is a representative financial product that allows you to steadily accumulate funds for retirement while enjoying annual income tax deductions. Mr. Kim, an office worker, has maintained this product for several years, enjoying the thrill of receiving refunds during his year-end tax settlement while making fixed monthly contributions. However, voices are growing that principal-guaranteed products alone may not be sufficient to guarantee a prosperous future life, considering recent inflation rates. It is also true that seeing people around him switch to fund products from securities firms can make one anxious about the safety of their own account. We must carefully consider whether this product can truly be the only answer to your retirement planning. In this article, we will thoroughly examine the structure and hidden pros and cons of pension savings insurance and provide guidance for wise asset management.
=
Pros and Cons and Return Comparison Analysis You Must Know Before Joining a Pension Savings Insurance
1. Basic Structure and Tax Deduction Benefits of Pension Savings Insurance
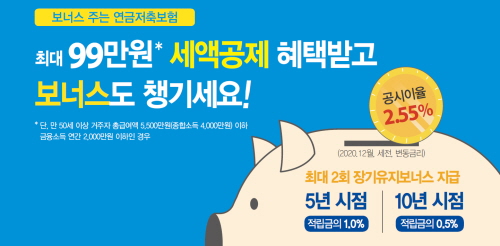
Pension savings insurance is a type of tax-advantaged savings product created by the government to encourage retirement preparation. It is highly popular every year-end tax settlement season because you can receive a tax deduction at a certain rate on the amount contributed annually. Employees with total income below a specific threshold can receive a significant refund within the contribution limit. For example, if you diligently contribute a set amount every month, you will enjoy the tax-saving effect of seeing cash deposited into your bank account in the following year. For this reason, it appears as an attractive option for office workers who want to reduce their immediate tax burden.
However, it is important to remember that strict conditions requiring you to lock in your money for a long period are attached behind these benefits. This is because there are mechanisms that prevent you from withdrawing the principal until you reach retirement age in your senior years. If you cancel the contract midway due to personal reasons, you face the disadvantage of having to return all the tax benefits you have received. Therefore, it is wise to accurately understand your monthly income and expenditure structure and join only at a level you can afford each month. It is most important to avoid setting an excessively large amount that leads to giving up midway.
Pension savings insurance offers high annual tax deduction benefits, but long-term maintenance is essential.
2. The Double-Edged Sword of Stability and Returns
The biggest characteristic and advantage of this product is that the principal is guaranteed. Even if the stock market crashes or the economic situation worsens, the insurance company safely protects the principal you have contributed. It provides the psychological peace of mind to sleep soundly without needing to check stock prices daily. For conservative investors who feel extreme fatigue from volatility, there is no stronger defense than this.
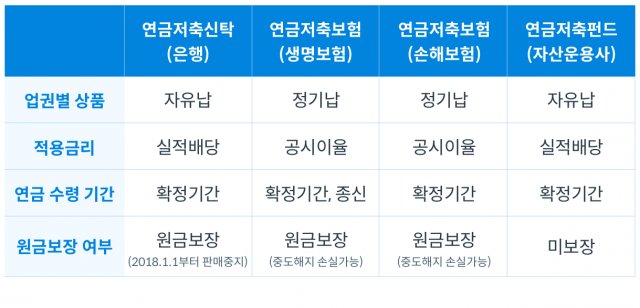
However, there is a fatal weakness: while the principal is guaranteed, the returns are far too low to keep up with inflation. Recent surveys indicate that while fund products from securities firms achieve double-digit returns, insurance-type products remain at very low levels. As time passes, the value of money decreases, and if interest earnings are also minimal, your real purchasing power after retirement may actually decrease. If you leave it alone trusting only in stability, you may face the result of your assets being eroded by the wave of inflation. Therefore, deep consideration is needed on how to catch both rabbits: securing stable principal and growing assets.
While it offers the safety of principal guarantee, low returns become a major disadvantage in the long term.
3. Comparison with Pension Savings Funds and Switching
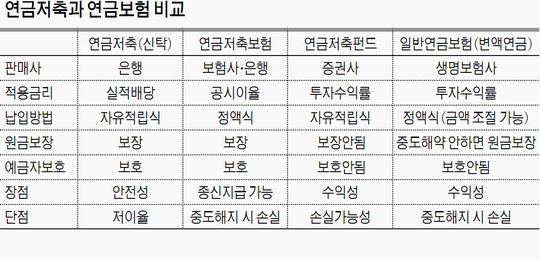
Many people preparing for retirement struggle between insurance products and securities firm products. Products managed by securities firms allow direct investment in stocks or exchange-traded funds (ETFs), enabling aggressive asset growth. On the other hand, insurance companies follow disclosed interest rates or fixed interest rates, clearly lagging in terms of returns. In fact, statistics show that the return gap between the two products can reach dozens of times, leading to a trend of shifting towards funds, particularly among younger generations.
People who joined insurance products long ago often find out about this later and consider transferring their accounts. There is a system that allows you to switch to a securities firm’s product without canceling your existing contract. However, when deciding to switch, you must coldly evaluate your investment style and the remaining time until retirement. If fund investment, which requires you to directly time your trades, is not suitable for you, the stability of insurance might be better. You should make a choice that fits your own investment philosophy rather than blindly following what others say is good.
If you prioritize returns, you may consider moving to funds, but careful judgment is required.
4. The Risk of a Tax Bomb from Early Cancellation
The part you must be most wary of when joining pension savings insurance is the risk of early cancellation. The moment you break the account because you urgently need a lump sum, all the tax deduction benefits you have received become void. The government treats this as miscellaneous income and applies a high tax rate to collect taxes, so the amount deposited into your account is much less than expected. You may experience the frustration of seeing your diligent efforts over more than ten years vanish in an instant.
In reality, many people regret hitting a tax bomb after being forced to cancel their contracts due to difficult household finances. Therefore, you should approach this product only after separately securing a deposit or savings account that can serve as an emergency fund. It is a safety measure to not set your monthly contribution amount too aggressively in preparation for unforeseen circumstances. You must complete this long race with the firm resolve to never cancel midway while maintaining the contract.
Early cancellation can result in significant losses due to the return of tax deductions and the imposition of miscellaneous income tax.
5. The Secret of Pension Income Tax in Old Age
Even when you reach retirement age and finally start receiving monthly pension payments, you must not overlook the tax issue. If you receive it in pension form after age 55, the government imposes a very low pension income tax rate to stabilize your retirement life. This is much more favorable than general income tax rates, allowing you to secure living expenses while significantly reducing the tax burden.
However, the point to note here is that if the annual pension receipt exceeds a certain amount, it may be combined with other income and become subject to comprehensive income tax. If you have many sources of income after retirement, there is also a risk of hitting an unexpected tax bomb. Therefore, smart withdrawal strategies, such as extending the receipt period or adjusting the monthly amount, are necessary. You must familiarize yourself with methods to reduce taxes in advance to prevent unnecessary expenditures in old age.