During periods of continued stock market and interest rate instability, a clear trend emerges where idle funds rapidly flow into safe short-term fund index funds as investors struggle to find suitable investment destinations. The net assets of the SOL Ultra-Short-Term Bond Active fund, launched by Shinhan Asset Management, recently surpassed 1 trillion won, proving this trend. As the direction of the stock market becomes uncertain and interest rate volatility increases, people looking for a place to temporarily park their spare funds are focusing their attention here. In fact, over the past week, massive funds amounting to several trillion won have flowed into top short-term fund products, attracting significant popularity. In this article, we will take a detailed look at the reasons why so many investors choose this product, its specific advantages, and how to utilize it. If you are looking for a financial product that offers free trading and favorable asset defense, please carefully review the content below.
=
Why the SOL Ultra-Short-Term Bond Active ETF Surpassed 1 Trillion Won in Net Assets
1. Market Focus on Short-Term Fund Index Funds
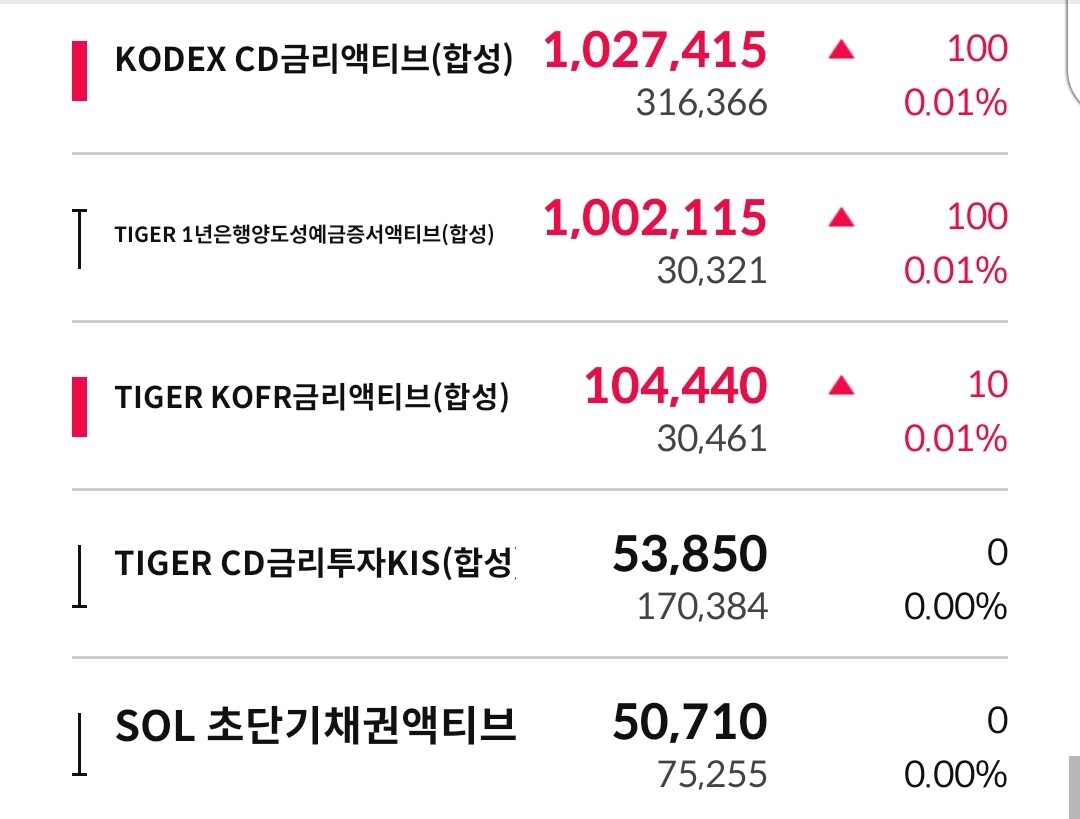
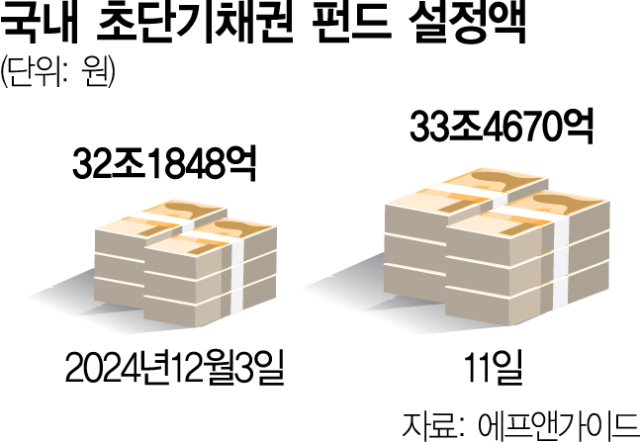
Recently, domestic and international stock markets have failed to establish a clear upward or downward direction, fluctuating daily and deepening investors’ concerns. Entering the stock market directly carries too much risk, yet leaving money in a bank account feels wasteful when considering inflation. Short-term fund index funds have emerged as a central alternative to resolve these concerns. In fact, over the past week, a massive amount of capital exceeding 1.4 trillion won has flowed into just the top ten major short-term fund products. This shows that the demand from individual investors who want to access their money anytime while seeking slightly better returns than bank deposits has exploded. It is also a result of increasing numbers of people seeking alternatives to stocks given that bank deposit and savings rates are unsatisfactory.
The phenomenon of liquidity funds moving en masse to short-term financial products has been observed in the past during interest rate hike periods or stock market slumps. However, the biggest difference this time is that it is in the form of an exchange-traded fund (ETF), which can be bought and sold easily and quickly like stocks on the exchange. Unlike regular time deposits, which require sacrificing promised interest if withdrawn early, this product does not have such drawbacks. Since it can be traded in the market at any time, it boasts excellent liquidity, allowing for immediate cash-out when cash is urgently needed. Mr. Kim, an office worker, recalls the interest loss he suffered from early withdrawal when he had to urgently increase his deposit for a rental lease, and praises the convenience of such products. Thanks to the appeal of managing assets flexibly without tying up money, investor response remains strong.
Demand for freely managing funds amid stock market instability and interest rate volatility is concentrating on short-term fund index funds.
2. The Significance of Shinhan Asset Management’s SOL Ultra-Short-Term Bond Active Surpassing 1 Trillion Won
The news that the SOL Ultra-Short-Term Bond Active product, ambitiously introduced by Shinhan Asset Management, has finally surpassed the 1 trillion won mark in net assets has generated significant buzz in the financial market. The reason this product has been chosen by so many among numerous short-term asset management products is due to its thorough stability and consistent performance. This product primarily invests in safe short-term financial products with proven safety, such as high-quality bonds and commercial papers with a remaining maturity of within 3 months. Because the maturity is very short, it has robust defensive capabilities, meaning bond prices do not fluctuate significantly even if market interest rates change suddenly. The fact that it can protect principal while expecting returns higher than bank deposits in unstable market conditions has captured the hearts of savvy investors.
The figure of 1 trillion won in net assets is strong evidence that the product’s reliability has been verified in the market, going beyond simple scale expansion. As the fund size grows, operational efficiency increases and liquidity management becomes smoother, allowing investors to entrust their money with greater peace of mind. In practice, it gains the robust capacity to handle large-scale redemption requests without instability during fund execution. Mrs. Lee, a housewife, who diversified her spare funds into this product on a friend’s recommendation, shared that she enjoys watching the interest accumulate little by little every day. As many people share their positive experiences and satisfaction, a virtuous cycle is created where the speed of fund inflows accelerates.
The SOL Ultra-Short-Term Bond Active surpassing 1 trillion won in net assets is a result proving its excellent stability and high investor trust.
3. What Assets It Invests In and How It Generates Returns
Examining the specific investment targets and asset management methods of the SOL Ultra-Short-Term Bond Active product makes it easy to understand why its stability is high. This product primarily uses short-term financial assets with excellent credit ratings, such as bonds rated A- or higher and commercial papers rated A2- or higher, as the core of its portfolio. By carefully selecting only assets from issuers with extremely low default risk, it significantly alleviates concerns about principal loss. It adopts a strategy of actively discovering relatively undervalued, high-quality stocks in the market to aim for additional interest income while minimizing risk. It is a structure that creates alpha returns through the meticulous management of professional operators, rather than simply sitting and collecting interest.
Recently, the Korea Risk-Free Benchmark Rate and the 91-day Certificate of Deposit (CD) rate have been fluctuating around 3.1% to 3.2%. Even in this benchmark interest rate environment, this product has demonstrated its competitiveness by recording a solid annualized return of 3.41% over the past three months. Compared to general bank demand deposits or flexible deposit/withdrawal products, it offers noticeably substantial returns. Mr. Park, a business owner, who temporarily parked his company’s short-term operating funds in this product, evaluated it as very satisfying because it yielded much better returns than a regular deposit. The fact that it can secure favorable returns compared to market interest rates while protecting the safety of the principal is the primary reason for this product’s existence.
It primarily invests in high-quality short-term bonds and commercial papers, pursuing stable interest income and performance exceeding market interest rates.
4. The Advantages of Utilizing Retirement Pension Accounts and Individual Asset Management Accounts
One of the most unique differentiators of this product is that it can be fully utilized up to a 100% limit in retirement pension accounts. Many short-term fund products in the market are classified as risky assets, often limiting the investment ratio in retirement pension accounts to 70%. However, since the SOL Ultra-Short-Term Bond Active is classified as a safe asset, the entire accumulated amount in Defined Contribution (DC) and Individual Pension (IRP) accounts can be invested in this product. Mr. Jung, an office worker, said he was relieved after finding this product, as he had been struggling to find a suitable product to fill the safe asset ratio in his retirement pension. For office workers who need to safely grow their retirement assets, it is difficult to find a more reliable and useful option.
In addition to retirement pensions, this product can be freely included and invested in the Individual Asset Management Account (ISA), known as an icon of tax savings. It is a perfect condition for investors who want to maximize tax benefits while safely managing cash assets in a highly volatile market. Because it allows capturing both reduced tax burdens and higher returns, it has become an essential item in the basket of smart investors. Mr. Choi, a young professional, shared that he consistently buys through his ISA every time he receives his salary, and enjoys watching his assets grow steadily. The ability to utilize it in conjunction with various tax-saving accounts is a core factor that further enhances the value of this product.
Classified as a safe asset, it can be utilized up to 100% without limit concerns in retirement pensions and Individual Asset Management Accounts (ISA).
5. The Secret to Reducing Price Fluctuation Burden and Enhancing Trading Convenience
The most feared aspect when investing in equity products or long-term bonds is the price volatility risk where principal decreases when interest rates change. However, since this product primarily holds bonds with a very short remaining maturity of within 3 months, it is barely affected by interest rate hikes or cuts. Even if interest rates rise, the maturity arrives quickly, allowing for a rapid switch to new high-interest bonds, which is advantageous. Conversely, even if interest rates fall, the risk of bond prices dropping sharply is very low, providing peace of mind regardless of when you invest. This is why investors tired of the rollercoaster-like fluctuations of the stock market are flocking to this product as a refuge.
The fact that it can be traded freely and in real-time on the exchange like regular stocks also provides immense convenience to busy modern people. You can turn on your smartphone Home Trading System (HTS) during weekday trading hours and buy or sell as much as you want, ensuring excellent cash liquidity. If you apply for a sale in the morning, cash-out is possible quickly according to established procedures, so you don’t need to rush around when urgent cash is needed. Mr. Han, a freelancer, expressed satisfaction, noting that his income cycle is irregular, but he buys this product whenever he has spare funds and withdraws it immediately when needed. The ability to complete all asset management with just a tap, without complex paperwork or bank visits, is a major appeal.
It minimizes price volatility risk with short maturities and is convenient as it can be traded freely in real-time on the exchange.
6. Future Outlook and Smart Fund Management Strategies
Since the uncertainty of domestic and international economic conditions is likely to persist for the time being, the popularity of safe standby fund products is expected to continue. Amidst diverging market predictions regarding the timing and pace of interest rate cuts, strategies to protect assets are prioritized over reckless investment in risky areas. In this market atmosphere, products like the SOL Ultra-Short-Term Bond Active will play a solid role as a shield protecting portfolio stability. Experts also advise securing a certain percentage of cash assets when constructing an investment portfolio and recommend the use of such short-term bond products. If you want to grow your assets comfortably without being swayed by the market’s capricious movements, this can be an excellent alternative.
In conclusion, if you want to protect your precious funds safely and efficiently amidst the turmoil of the stock market, you should pay attention to short-term fund index funds. This is because it is a realistic and attractive breakthrough that simultaneously complements the frustration of bank deposits and the risks of the stock market. Please check your current asset situation and account types right now and consider appropriate inclusion through retirement pensions or Individual Asset Management Accounts (ISA). Small differences in choices can be the decisive key that determines the safety and return rate of your assets in the long run. We encourage you to continue steady wealth management based on smart financial information and prepare for a prosperous future step by step.
Short-term fund products should be actively utilized to manage cash assets safely and efficiently in an uncertain economic environment.
Frequently Asked Questions
=