Prepayment fees are calculated as the repayment amount × fee rate × remaining days ÷ total loan term. In most cases, you do not have to pay this fee if more than three years have passed since you took out the loan. Even if you repay the same 100 million KRW, the fee can vary significantly depending on whether you are in the early or late stages of the loan. Therefore, it is best to calculate the fee first before deciding whether to refinance.
How to Calculate Prepayment Fees: How Much Will You Pay to Repay 100 Million KRW? Let’s Calculate It Directly
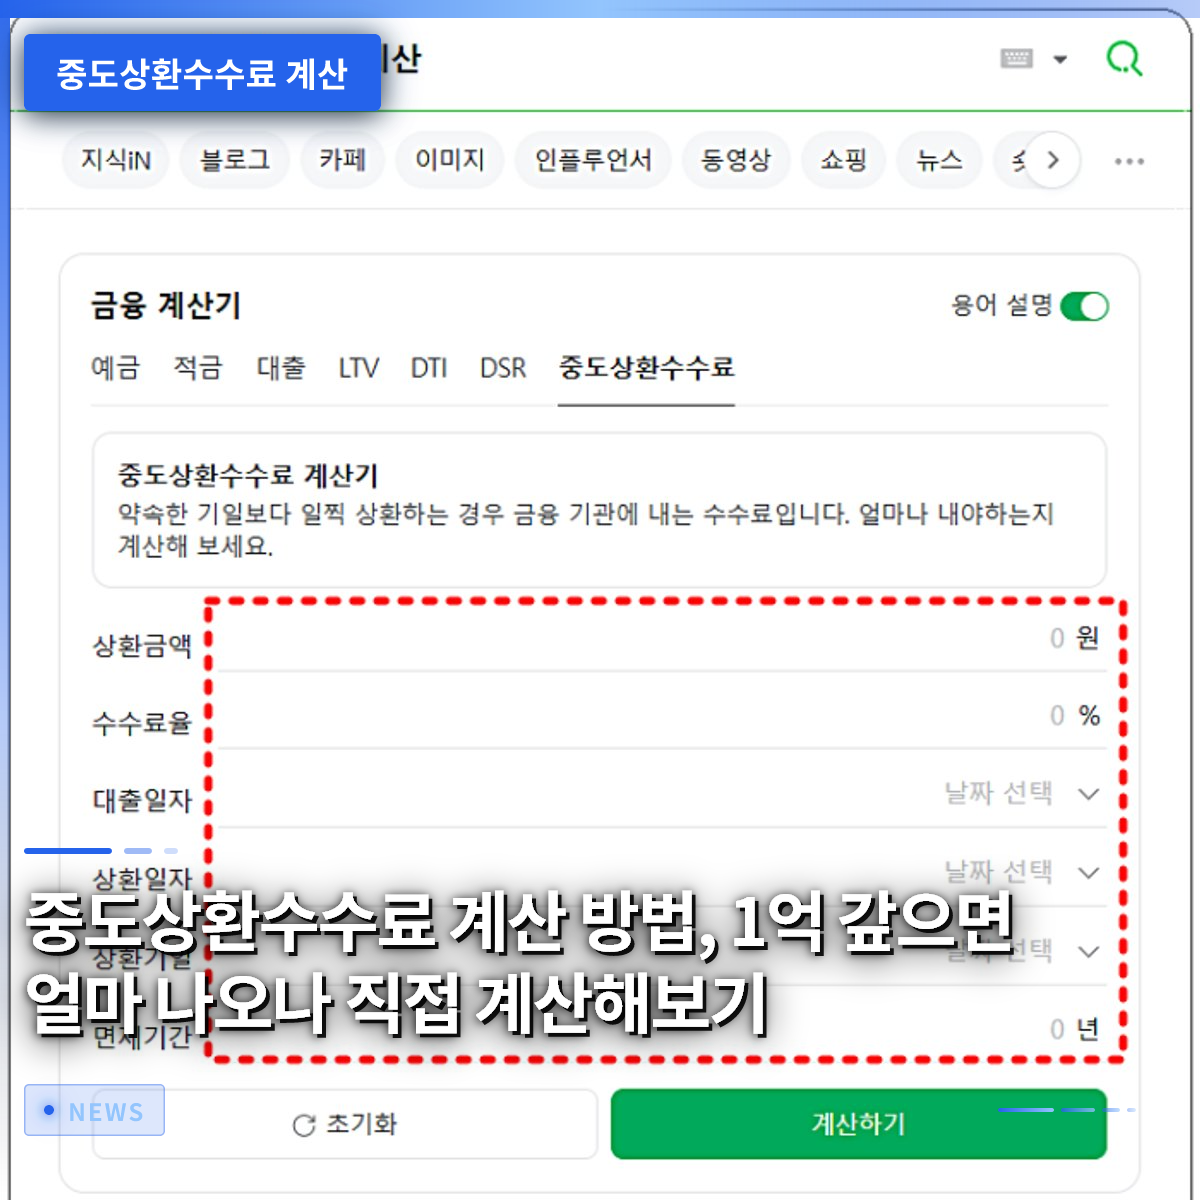
1. How Prepayment Fees Are Calculated

There is only one formula. Multiply the prepayment amount by the fee rate, and then multiply that by the ratio of remaining days in the loan term. The structure is such that the fee decreases as the remaining period gets shorter, so the burden becomes lighter as you approach maturity. Fee rates vary by bank and product. Housing loans typically have rates in the 1% range, while credit loans are often lower, but the exact figure is listed under the “Prepayment Fee” section of your loan agreement or product description. Do not rely on memory; check your specific contract directly.
Use the fee rate exactly as written in your contract, and calculate the ratio of remaining days based on the loan start date.
2. How Much Do You Actually Pay When Repaying 100 Million KRW?

For example, let’s assume you have a loan with a 1.4% fee rate and a 3-year term (1,095 days), and you decide to repay the full 100 million KRW with 1 year (365 days) remaining. 100 million KRW × 1.4% = 1.4 million KRW. Multiplying this by the remaining period ratio of 365/1,095 (which is 1/3) results in approximately 467,000 KRW. Under the same conditions, if you repaid with 2 years remaining, the fee would be 2/3 of 1.4 million KRW, which is approximately 933,000 KRW. Even delaying repayment by just one month can reduce the fee by tens of thousands of won, so adjusting the date is a viable strategy if you are close to maturity. The figures above are hypothetical for illustrative purposes; actual amounts will vary based on your contract terms.
3. There Are Cases Where You Don’t Have to Pay Any Fee
Most products do not charge a fee if more than three years have passed since the loan execution date. Some products allow you to repay a certain percentage of the principal each year without a fee, even if it is within the first three years. Additionally, some financial institutions have specific exemption reasons. Since these conditions vary by product and can change, the most accurate way to know is to ask your bank’s app or customer service center for the “prepayment fee exemption conditions for my loan” before repaying. A single phone call can make a difference of several hundred thousand won.
4. Determine if Refinancing Is Worth It Using the Break-Even Point
When refinancing at a lower interest rate, compare the fee with the interest savings. If the interest rate drops by 0.5 percentage points on a balance of 100 million KRW, your interest payment decreases by approximately 500,000 KRW per year. If the fee is 467,000 KRW, you start seeing a net benefit after about 11 months. Be sure to include potential additional costs for the new loan, such as stamp duty and guarantee fees, in your calculation. If the remaining loan term is shorter than the break-even point, it is better not to refinance.
Fee ÷ Annual Interest Savings = Number of years to break even.
5. Check These Steps in Order Before Repaying
First, find the fee rate and exemption conditions in your loan agreement. Next, use the repayment simulation in your bank’s app or contact customer service to check the exact fee for repaying today. Finally, calculate the break-even point by factoring in the interest rate and additional costs of the new loan. Going through these three steps will help you avoid the situation where you repay and find the fee was higher than expected. If the amount is large, compare the conditions from two or three financial institutions before repaying.