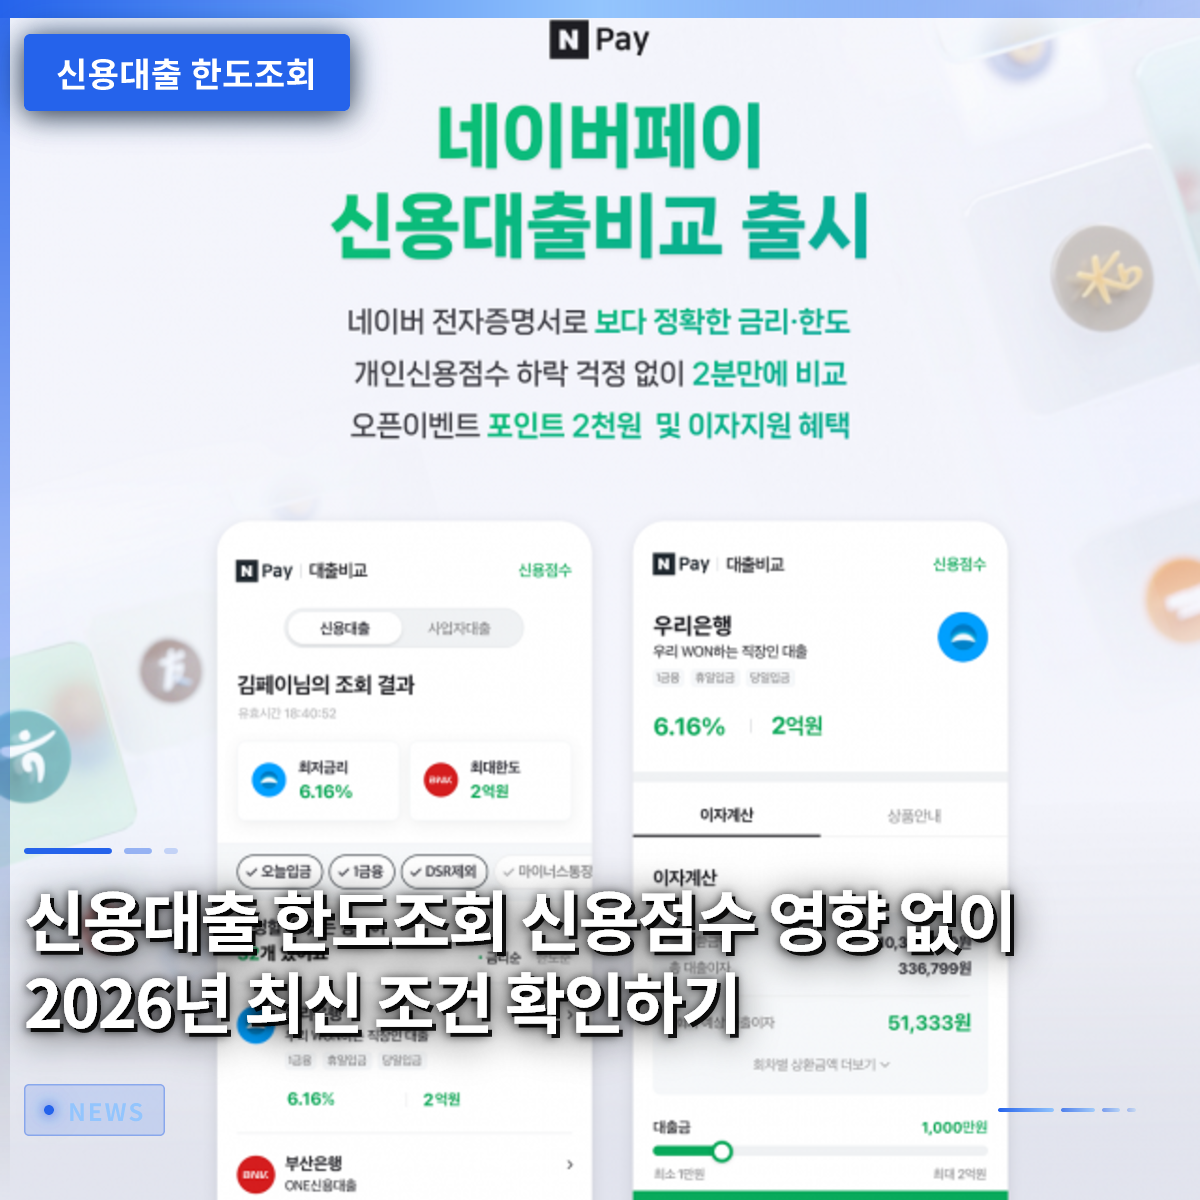
Checking your credit loan limit multiple times does not lower your personal credit score under current financial regulations. In the past, merely inquiring or checking your limit could result in a penalty to your score, but with recent regulatory changes, you can now confidently compare conditions across various financial institutions. For example, Mr. Kim, an office worker who needed a lump sum, compared interest rates and limits through several mobile apps and was relieved to find no change in his credit score. Recently, the avenues for checking your available limit in real-time without submitting documents have expanded through various non-face-to-face platforms like Naver Pay and KakaoBank. However, caution is needed, as indiscriminate inquiries to too many institutions in a short period can negatively impact the review process. This article details the essential information you must know when checking your credit loan limit and tips for maximizing your available limit.
=
Checking Your Credit Loan Limit Without Affecting Your Credit Score: Latest 2026 Conditions
1. The Truth About Credit Loan Limit Checks and Credit Scores
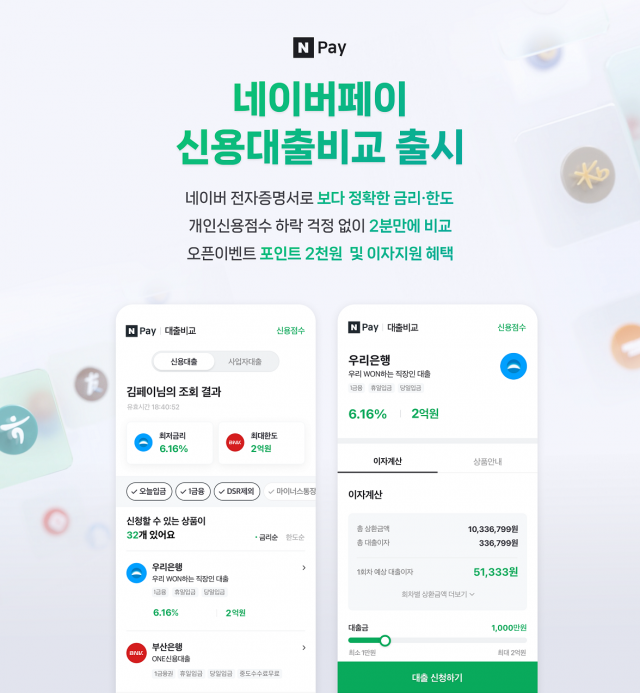
In the past, even the record of inquiring about loan eligibility or checking limits at a financial institution could negatively impact credit evaluations. As a result, many people who needed money were cautious, checking with only one institution to avoid the risk of their score dropping. However, with rational updates to financial regulations, simple limit checks or interest rate comparisons no longer harm your credit score. Comparing conditions from various banks on your smartphone screen is a legitimate right that does not deduct from your credit. Nevertheless, you should avoid excessively frequent inquiries, such as indiscriminate checks dozens of times a day. Some financial institutions’ review systems may halt the approval process if they detect excessive inquiry records in a short period, interpreting it as a sign of urgent financial distress. Therefore, it is wise to focus your inquiries on your primary bank or trusted loan comparison platforms where you have a high likelihood of actually transacting.
Simple credit loan limit checks do not affect your credit score, but excessive repeated inquiries in a short period should be avoided.
2. Latest Non-Face-to-Face Limit Check Methods for 2026
These days, you can check limits from all financial institutions at once with just your smartphone, without needing to visit a branch, take a number, and wait. Accessibility has improved significantly with the activation of loan comparison services like Naver Pay, in addition to internet banks such as Toss Bank and KakaoBank. Even for self-employed individuals, real-time non-face-to-face limit checks are now possible without the need to issue and submit complex documents. For example, Mr. Park, a self-employed business owner who urgently needed operating funds, opened a smartphone app to check his business credit loan limit and confirmed the results within minutes. These mobile check services are often linked with public data from agencies like the Ministry of the Interior and Safety, automating income verification and employment confirmation. Users can directly view their estimated loan limit and interest rate after completing a common certificate or simple authentication, making it very convenient. However, the financial institutions listed and the preferential interest rate conditions applied may vary slightly by platform. Therefore, rather than checking with just one place, utilizing a couple of trusted comparison services is the shortcut to finding the most favorable conditions.
Using smartphone apps and loan comparison platforms allows for real-time non-face-to-face limit checks without document submission.
3. Why Loan Limits Are Decreasing Compared to Before
More people than you might think are shocked to find that their new credit loan limit is significantly lower than what they received in the past. This is because the overall trend in loan supply across the banking sector has become stricter due to strengthened household debt management and the introduction of total volume regulations in recent years. In particular, if you have a high balance on existing loans or if interest rates are rising, the available limit for credit loans naturally decreases. For example, an office worker who had fully used a 50 million won overdraft account last year found that their limit was drastically reduced when they checked again this year, forcing them to give up on moving. Additionally, the impact of the Total Debt Service Ratio (TDSR) regulation, which strictly calculates the ratio of principal and interest payments to income, is significant. If your salary remains the same but your existing card loans or other small loans have increased even slightly, your credit loan limit will inevitably decrease. To maintain your loan limit at its maximum, it is advisable to clear unnecessary small debts in advance and utilize low-interest refinancing programs. It is essential to regularly check that you do not have excessive debt relative to your income level.
Credit loan limits may decrease due to strengthened Total Debt Service Ratio regulations and existing loan balances.
4. Differences Between Overdraft Accounts and Standard Credit Loans
When taking out a credit loan, many people hesitate between the standard method of receiving a lump sum and the method of drawing funds as needed, similar to an overdraft. Overdraft accounts are very useful for urgent funds because you set a limit and only pay interest on the amount actually used. However, a characteristic of overdraft accounts is that the entire set limit is counted as an existing loan, even if you have not actually used any of the money. For example, if you open an overdraft account with a 30 million won limit and do not use a single won, it is still considered as if you have already used 30 million won when applying for other loans. Due to this characteristic, if you plan to take out a larger mortgage or additional credit loans in the future, the overdraft limit can become an obstacle. On the other hand, standard credit loans deposit money directly into your account, so interest accrues on the full amount, but they are evaluated based on the actual balance during other loan reviews. If your funding purpose is short-term and liquidity is important, an overdraft account is advantageous; if you plan to hold and use a lump sum over the long term, a standard loan is better. You should carefully consider your future funding plans and make a prudent decision on which method to choose.
Overdraft accounts count the entire set limit as existing debt even if unused, which can be disadvantageous for additional loans.
5. Essential Preferential Conditions to Lower Interest Rates and Increase Limits
Once you have checked your credit loan limit, you should look into preferential conditions to lower the interest rate as much as possible and maximize your limit. Most banks offer interest rate reductions if you meet criteria such as salary transfer records, automatic payment counts, or primary card usage history. For example, an office worker who previously used another bank as their primary bank transferred their salary account to the new bank and enrolled in a savings product when taking out a loan, receiving a 0.5% interest rate benefit. These small preferential conditions play a decisive role in significantly reducing the monthly interest burden. Additionally, if you have a long tenure or work for a high-quality company, or hold professional qualifications, additional limits may be opened beyond the basic limit. If you are planning to change jobs, it is advantageous to check your limit after securing a certain tenure at your current workplace. When providing income proof, carefully checking that supplementary income documents are not missing is the secret to increasing your limit. You need to make the effort to visit a bank branch for face-to-face counseling or thoroughly check for hidden preferential conditions in non-face-to-face apps.
Actively utilizing preferential conditions such as salary transfers and primary card usage can lower interest rates and secure favorable terms.
6. Wise Loan Management and Future Outlook
The future financial market is expected to evolve toward a direction that evaluates individual repayment capacity in a multi-dimensional way, as artificial intelligence and alternative credit scoring technologies become more advanced. Beyond traditional income indicators, various non-financial data from daily life will be used to provide more benefits to diligent individuals. Therefore, maintaining financial transactions without delinquency and cultivating healthy consumption habits is the most reliable secret to credit management. If you are about to check your credit loan limit because you need a lump sum, do not act out of haste; start by comparing options through various platforms. We hope you will wisely choose the optimal product that suits your conditions, prevent unnecessary interest expenditures, and protect a solid household economy.
In a financial environment where alternative credit scoring technology is developing, thorough credit management in daily life is the key to the most favorable loan conditions.
Frequently Asked Questions
=