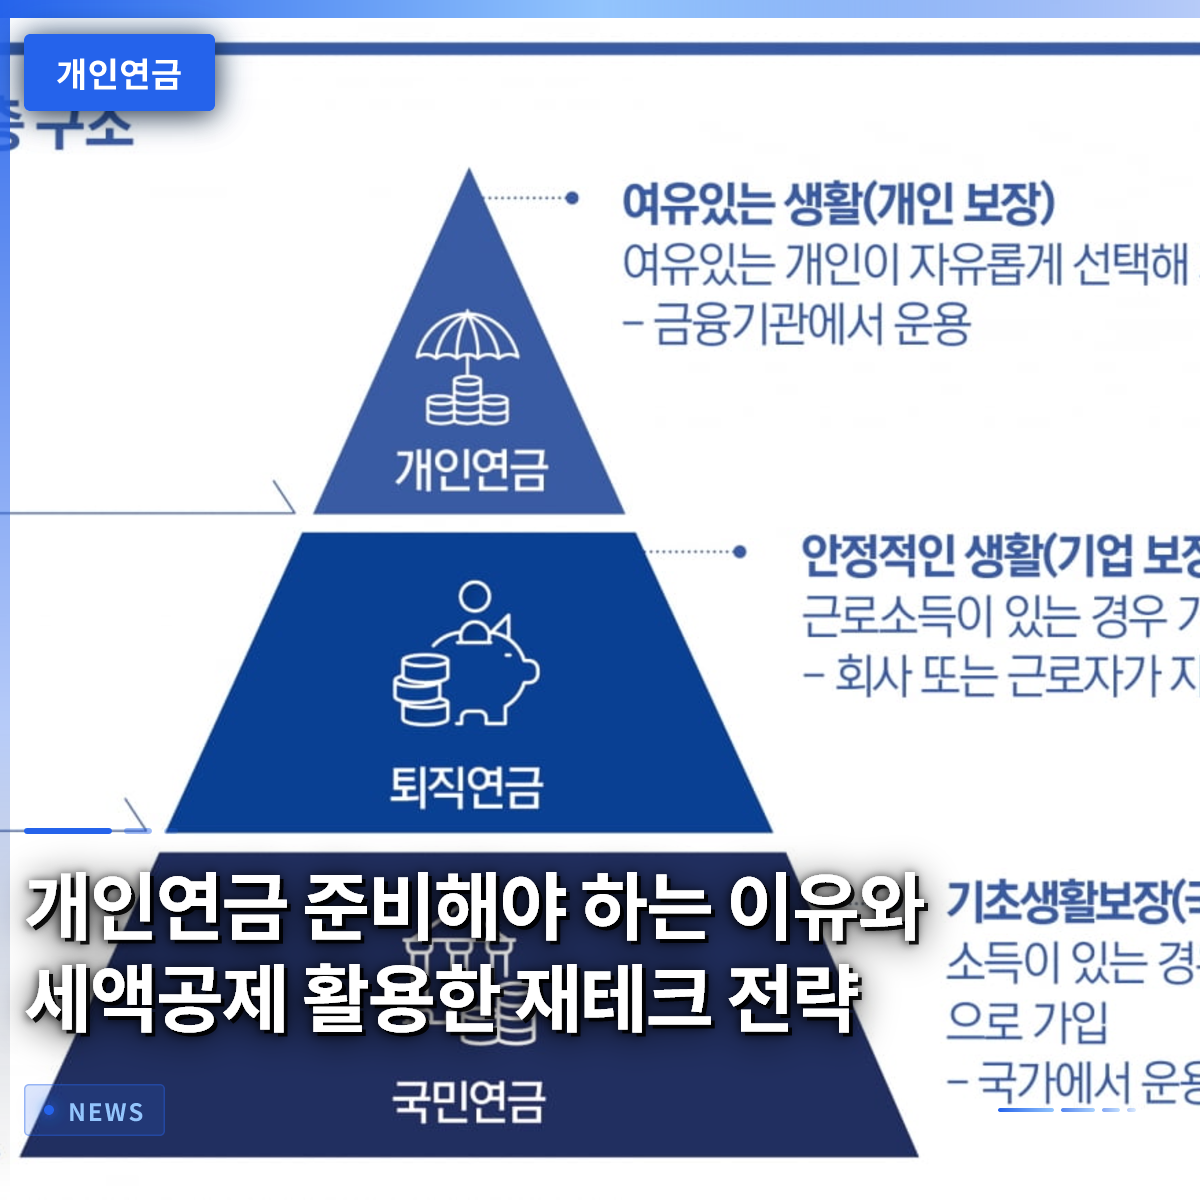
Since the National Pension alone is difficult to sustain for a comfortable retirement, additional asset formation through personal pensions is essential. Recently, private pension enrollment through various financial institutions, such as banks and securities firms, has significantly increased to prepare for life after retirement. For both employees and self-employed individuals, the core of smart wealth management is creating a structure that secures a stable retirement while taking advantage of tax benefits. Seeing acquaintances who have recently retired struggle due to a lack of fixed income makes the importance of early preparation all the more apparent. In this article, we will specifically examine the types of private pensions and how to maximize tax deductions, outlining actionable plans for retirement design. We recommend that readers review their asset status starting today and find suitable products.
=
Why You Need to Prepare a Personal Pension and Wealth Management Strategies Using Tax Deductions
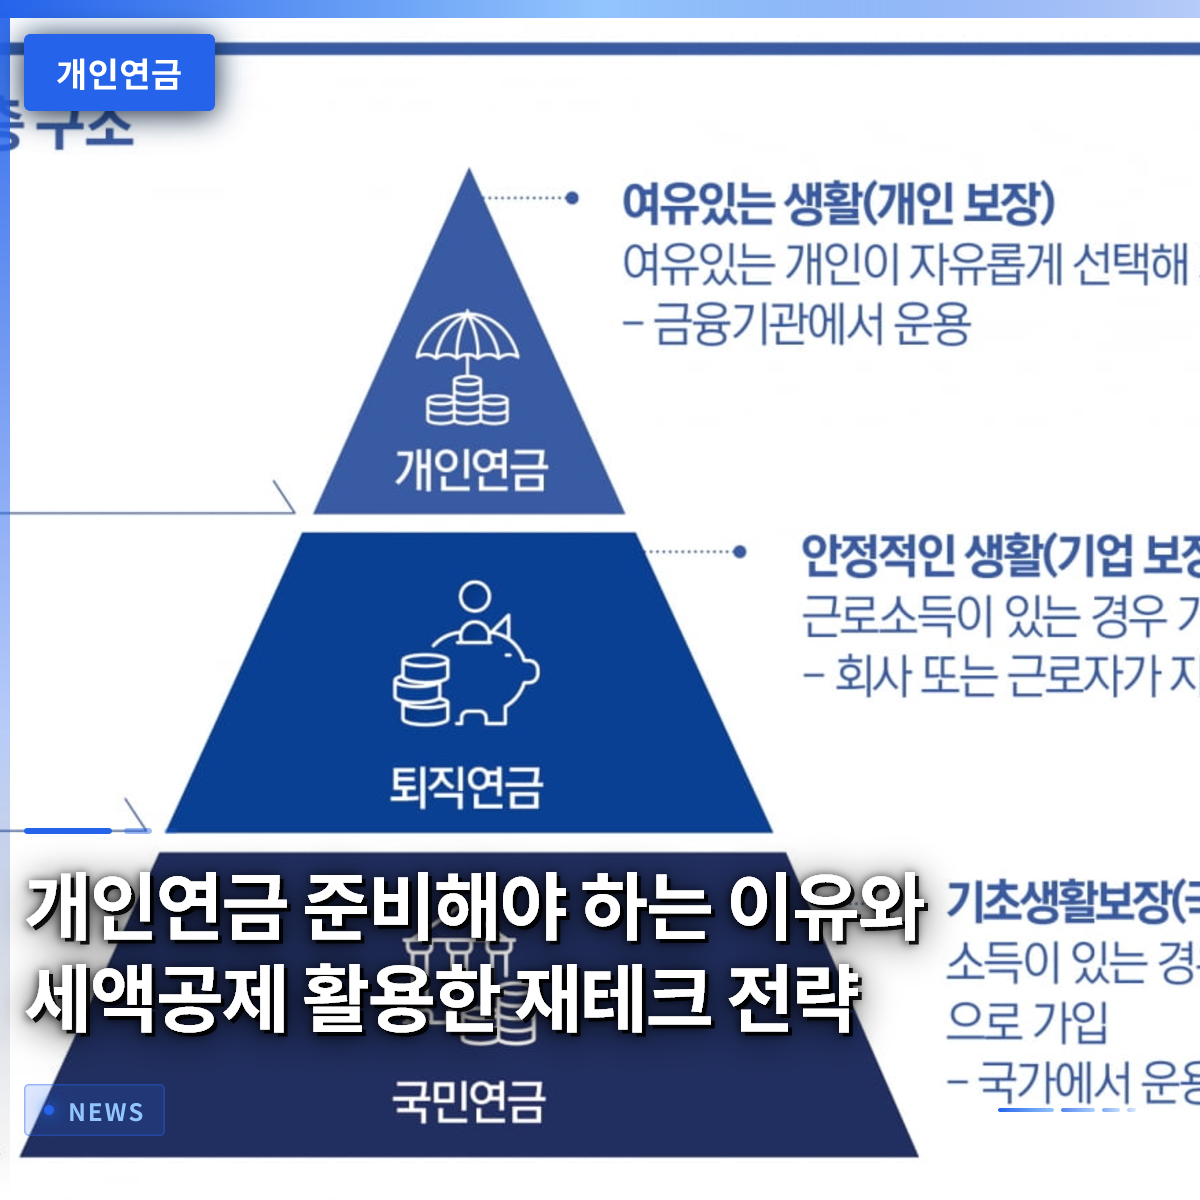
1. The Limitations of the National Pension and the Need for Private Pensions

The National Pension, which we diligently pay into every month, often struggles to keep up with inflation and is frequently insufficient for actual living expenses after retirement. Even looking at data from the Statistics Korea, it is clear that maintaining a dignified life after retirement requires significantly more funds than expected. If one relies entirely on the state-provided pension, they may suffer significant financial blows when unexpected medical bills or expenses arise. Therefore, to fill this economic gap, the proportion of private pensions prepared individually must be gradually increased.
When meeting seniors who are approaching retirement, it is easy to discover that whether they have assets prepared from their younger years completely determines their quality of life in old age. Some enjoy leisurely hobbies thanks to a stable cash flow hitting their accounts every month, while others worry and feel anxious about their monthly living expenses. The decisive key to this difference can be seen as whether they started preparing a private pension early. Therefore, we must focus on setting aside a portion of our current income to build a solid safety net for our future selves.
Since the National Pension is insufficient for retirement living expenses, additional asset formation through private pensions is essential.
2. Representative Private Pension Products: Pension Savings and Individual Retirement Pensions

Representative products that allow you to grow personal assets while simultaneously enjoying tax benefits are Pension Savings and Individual Retirement Pensions. Pension Savings can be enrolled through banks, asset management companies, or insurance companies, and its advantage is that anyone with income, not just employees, can contribute flexibly. On the other hand, the Individual Retirement Pension is a comprehensive asset management account where employees or self-employed individuals can make additional contributions to increase tax deduction limits and invest in various products such as Exchange-Traded Funds (ETFs). Both products offer tax deductions on contributions at a certain rate during year-end tax settlement, establishing themselves as essential wealth management tools among employees.
For example, an employee who consistently contributes up to the annual maximum limit often receives a surprisingly substantial refund during the year-end tax settlement season, providing a significant boost to their household budget. It is common to see colleagues who worry about a “tax bomb” every year, while those who utilize these accounts are actually smiling as they receive tax refunds. However, special caution is required because withdrawing from these accounts midway requires returning the tax benefits received and incurs miscellaneous income tax. Therefore, a wise operating method is to set contributions only with surplus funds that do not need to be used immediately and can be maintained over the long term.
Pension Savings and Individual Retirement Pensions are core financial products that achieve both tax deductions and asset growth.
3. Tax Deduction Benefits and Strategies to Maximize Tax Savings

To prepare for an aging society and encourage citizens to voluntarily secure retirement funds, the government provides generous tax deduction benefits during the annual year-end tax settlement. Although the deduction rate varies according to total income, a certain percentage of the contributed amount is directly deducted from taxes, resulting in a very significant perceived tax-saving effect. For example, if you consistently save a fixed amount each month to reach the annual limit, you can receive a considerable portion of the taxes paid over the year back in cash or have it deducted from your final tax liability. This is akin to receiving a subsidy from the state rather than just saving, making it a valuable opportunity that employees should absolutely not miss.
Listening to friends who are good at wealth management, they maximize tax savings by checking their account balances before the year-end tax settlement season and topping up any shortfalls in one go. Thanks to this meticulous strategy, they show the luxury of receiving a substantial refund to use for vacation expenses, even when others are in a situation where they have to pay more taxes. If we actively acquire and practice this financial knowledge, we can create a virtuous cycle of saving on annual taxes and reinvesting that money into retirement funds. Reducing taxes is exactly the same as generating profit, so it is necessary to accurately grasp the annual limit amount and contribute strategically.
Actively utilizing the year-end tax settlement deduction system allows you to save on taxes while simultaneously accumulating retirement funds, achieving a two-fold benefit.
4. Investment Strategies Utilizing Various Financial Products
Within private pension accounts, you can invest in various assets such as equity products, bond products, and Exchange-Traded Funds (ETFs), rather than simply depositing cash. Recently, many investors are actively holding products that pursue stable dividend yields or track major global indices, even in volatile market conditions. For example, investors who consistently purchase high-quality overseas index ETFs with a fixed amount each month to enjoy long-term compound interest effects are rapidly increasing. By diversifying and managing assets in this way, one can defend against inflation risk and safely grow the principal over the long term.
In reality, looking at the returns of those around us who have consistently invested in equity ETFs on a regular basis for over ten years for retirement, they often achieve remarkable results that far exceed deposit interest rates. Of course, one’s mind may waver when the market temporarily declines, but due to the nature of pension accounts, the money is not accessed for decades, allowing one to maintain a strong mentality without being swayed by short-term fluctuations. It is most important to compare excellent products launched by various asset managers and construct a portfolio suitable for one’s investment style. While referring to expert recommendations and market trends, the final choice should be made cautiously, considering one’s retirement timing and risk tolerance.
Utilizing various ETFs and investment products within pension accounts can maximize long-term returns.
5. The Risks of Early Withdrawal and the Importance of Long-Term Maintenance
The biggest enemy to guard against in the process of accumulating retirement assets is the temptation of early withdrawal due to unexpected expenses. As life goes on, moments will inevitably arise where a large sum of money is suddenly needed or urgent cash is required, making one want to withdraw from the account they have been funding. However, as mentioned earlier, withdrawing from a pension account midway requires returning all the tax benefits enjoyed and results in a heavy “tax bomb” of miscellaneous income tax. Consequently, not only will you suffer a loss on your principal, but you will also have to pay additional taxes to the state, a painful situation that should absolutely be avoided.
I have seen many acquaintances who broke their valuable pension accounts in the past because they urgently needed funds, only to deeply regret it later in life. It is equivalent to giving up one’s most reliable companion for the future just to get through an immediate crisis, so a firm resolve is needed to protect this account under any circumstances. If an unavoidable funding need truly arises, one should first look for alternatives such as utilizing loan systems or temporarily suspending contributions, rather than withdrawing from the account. One must deeply engrave in their heart the truth that only those who maintain their accounts consistently over the long term can enjoy true financial freedom after retirement.
Early withdrawal leads to a tax bomb and principal loss, so maintaining the account long-term is key under any circumstances.
6. Action Plans for Retirement Design and Future Outlook
Based on the content reviewed so far, it is most important to check your income and expenditure structure today and set a contribution plan at an appropriate level. The pace of aging will accelerate further, and the environment where individuals must take responsibility for their own retirement is expected to deepen. Therefore, the wisdom to enroll in Pension Savings or Individual Retirement Pensions even a day earlier than others to enjoy the magic of compound interest is needed. If you develop the habit of saving a small amount consistently every month, you will feel great pride seeing your assets snowball in a few years.
Looking around, there are many people who do nothing while waiting for the perfect timing, but the best timing is right now. We hope you will actively utilize the tax deduction benefits and various investment strategies learned today to gradually draw up your own solid retirement blueprint. Do not forget that life after retirement is longer than expected, and only those who are prepared can enjoy that time comfortably and happily. Start small actions today for a prosperous life in the future.
Rather than waiting for the perfect timing, checking your pension account and starting contributions today is the shortcut to a successful retirement.
Frequently Asked Questions
=