Pension savings insurance is a representative financial product that allows you to receive tax deductions during your annual tax settlement while steadily building a stable retirement fund. Recently, as the preference for guaranteed interest rates over risky assets like stocks and bonds has grown, products offering annual interest rates in the 4% range are once again gaining attention. While fixed monthly expenses might make it feel like a burden to set aside 100,000 or 200,000 won separately, you can easily get started by simply reducing your coffee consumption a little. For example, Mr. Kim, an office worker, saves up his post-lunch coffee money to cover his pension insurance premiums. In this article, we will carefully examine everything from the specific tax deduction benefits of pension savings insurance to recent interest rate trends. If you want to prepare for retirement while also saving on taxes, please read this content to the end.
=
Comparative Analysis of Tax Deduction Limits and the Benefits of 4% Guaranteed Interest Rates in Pension Savings Insurance
1. Basic Concepts and Features of Pension Savings Insurance
Pension savings insurance is a representative savings product created by the government to support retirement security. It is designed so that if you pay a fixed amount monthly, you can receive it back in the form of a pension after retirement. Many people focus only on housing savings or regular deposits, but retirement funds should be prepared separately with a long-term perspective. This is why office workers start by automatically transferring 100,000 or 200,000 won from their monthly salaries into savings. While it may feel painful to see money leaving your account, it returns as a solid pillar of support over time. In particular, the psychological peace of mind that comes with principal protection, unlike other investment products, is a major advantage.
In the early stages of your career, insurance and savings products may feel unfamiliar and difficult to understand. However, as you age, you come to realize the importance of both health coverage and asset building. After your forties, you need to focus on serious retirement preparation and asset management, so the habit of starting to prepare now is crucial. This product must be maintained for a certain period after enrollment, and if you cancel it midway, you may have to return the tax benefits received. Therefore, you need the wisdom to set your premium amount within a reasonable limit that matches your income level.
Pension savings insurance is a representative product that allows you to prepare for retirement stably while ensuring principal protection.
2. Summary of Tax Deduction Benefits and Limits
The biggest reason for enrolling in pension savings insurance is undoubtedly the tax deduction benefit received during the annual tax settlement. Personal pension savings products provide a tax refund based on a certain percentage of the annual premium paid, making them an essential tax-saving tool for office workers. When combined with the Individual Retirement Pension (IRP), the deduction limit applies up to a maximum of 9 million won annually, which is highly advantageous. Employees with a total salary of 50 million won or less, or those meeting specific criteria, can receive a higher deduction rate. For office workers who worry about the “tax bomb” every year during the tax settlement season, there is no better relief than this.
Specifically, if you pay 300,000 won monthly, you will save 3.6 million won over a year. By multiplying this by the deduction rate corresponding to your income bracket, you can receive a substantial refund. The moment you see the refund amount deposited into your account, the burden of monthly payments turns into a sense of accomplishment. However, be aware that if you cancel the policy midway, you must repay the tax benefits received so far as miscellaneous income tax. Therefore, rather than enrolling impulsively just for the immediate refund, you should first check if you have the financial capacity to maintain it long-term. If you want to achieve both tax savings and retirement preparation, it is best to calculate your annual income and premium limits in advance.
When combined with an IRP, pension savings insurance offers tax deduction benefits up to a maximum of 9 million won.
3. The Appeal and Background of Recent 4% Guaranteed Interest Rates
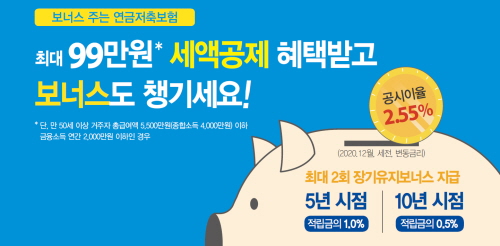
Recently, the number of investors seeking stable guaranteed interest rates instead of risky assets like stocks and funds has surged in the financial market. Life insurance companies are gaining significant popularity by introducing products with guaranteed annual interest rates in the 4% range through bancassurance channels. In a highly volatile investment environment, the promise of guaranteed interest without the risk of principal loss has captured the hearts of both the wealthy and office workers. Banks are also actively selling these insurance products to increase non-interest income, adding vitality to the market. The value of safe assets that bring certain returns shines brightest during times of high uncertainty.
It is true that the appeal of pension products was significantly lower during the era of low interest rates. However, at the current point where interest rates have risen, guaranteed interest rate products have emerged again as the best wealth management tool. Watching the predetermined interest accumulate bit by bit every month gives you a real sense of the magic of compound interest. As retirement approaches, people naturally prefer predictable returns over investment products with the risk of principal loss. Looking ten or twenty years into the future, products that guarantee stable interest rates bring peace of mind.
Pension products offering guaranteed annual interest rates in the 4% range are once again gaining attention as a stable investment destination in the recent financial market.
4. Differences Between Pension Savings Insurance and Pension Savings Funds
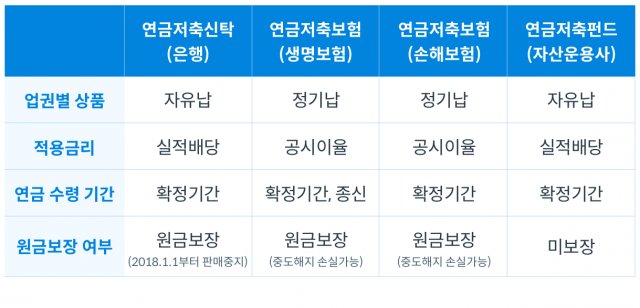
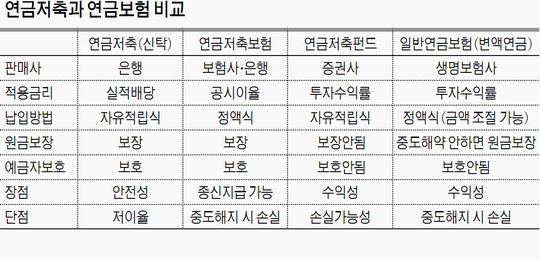
When preparing for a personal pension, many people find themselves deeply torn between pension savings insurance and pension savings funds. Insurance products guarantee the principal and provide stable interest rates, while fund products invest directly in stocks or bonds to pursue higher returns. Mr. Park, an office worker, chose insurance with a fixed interest rate because he prioritized stability, while Mr. Kim, who is skilled in stock investing, chose a fund that he manages directly. Since the same tax deduction limits apply to both products, the key is to choose based on your own investment style.
If you strongly dislike risk and want to grow your money safely like a bank deposit, pension savings insurance is a much more suitable choice. On the other hand, if you want aggressive returns that exceed the inflation rate and wish to manage your assets directly, you should look toward funds. Rather than blindly following what others say is good, you must consider your investment style and age to avoid failure. In the early stages of your career, it is useful to start with an insurance format to build a foundation of assets, and then combine it with funds once you gain confidence in asset management. You must carefully compare the structure and fee systems of the products before making a decision to avoid regret later.
Pension savings insurance suits those seeking stability and principal protection, while pension savings funds suit those pursuing higher returns.
5. Everyday Saving Tips for Managing Monthly Premiums
Many people say they want to put money into pension savings every month but can’t get started because their living expenses are tight. However, if you actually try to reduce unnecessary expenses in your daily life, you can easily create surplus funds. For example, saving on expensive daily coffee or reducing food delivery just once or twice can easily save you 100,000 won a month. Mr. and Mrs. Lee, a dual-income couple, set up automatic transfers to their pension account using the money saved by reducing weekend dining out. Even small amounts, when accumulated consistently every month, eventually become a substantial sum that protects your future.
Controlling expenses is a process of giving a gift to your future self, going beyond simply saving money. At first, it may feel painful to see money leaving your account, but your perspective changes completely after receiving your annual tax settlement refund. By using the automatic transfer function to deduct the savings amount immediately on payday, you naturally save because the money is no longer available to spend. It is important to strictly separate your emergency fund account from your retirement pension account so that you can use the emergency fund when needed. Try starting a small savings habit today with the mindset of simply skipping coffee ten times.
By reducing small everyday expenses and utilizing automatic transfers, you can continue pension savings without burden.
6. Final Recommendations and Outlook for Retirement Preparation
Life after retirement is much longer and broader than you might think, and a solid economic foundation to support it must be prepared in advance. Now, when the government’s tax deduction benefits and financial companies’ guaranteed interest rates align, is the best time to start pension savings insurance. No matter how the economic situation changes in the future, those who have consistently accumulated assets will never be shaken. Rather than being swayed by rumors, you must practice wise financial living tailored to your income and future plans. Please compare products suitable for you right now through a nearby financial institution or mobile app.
Retirement preparation has the nature of becoming more costly and burdensome the longer you delay it. The small practice you start today will return as millions of won in tax savings and a comfortable retirement life in a few years. The right answer is to start gradually with an amount you can afford, without being intimidated by complex financial terms. Instead of blind investing that everyone else is doing, exercise the wisdom to secure certain tax savings and stability. I recommend taking action now while imagining yourself smiling in the approaching future.
Thorough prior preparation and consistent premiums are the only guarantees of a successful retirement and certain tax savings.
Frequently Asked Questions
=