When comparing expense insurance, simply looking at the monthly payment amount and canceling your existing contract can lead to significant losses. Therefore, you must carefully examine the coverage scope for each generation of the product. As of 2026, many people are considering switching policies due to soaring renewal premiums, but the latest product is not always the right answer. Products purchased in the past often have lower out-of-pocket costs or more generous coverage limits, so switching hastily could result in facing a “medical bill bomb.” In fact, there are numerous cases where policyholders who maintained 1st or 2nd generation products canceled them out of frustration with renewal hikes, only to regret their decision later. In this article, we will perfectly compare the characteristics of each generation from the 1st to the latest products and specifically identify the most advantageous choice for you. Let’s now look at smart insurance management tips to protect your wallet, one by one.
=
Comparing Expense Insurance: 2026 Latest Guide to Generational Differences and Premium Savings Tips
1. Evolution and Key Features of Expense Insurance by Generation
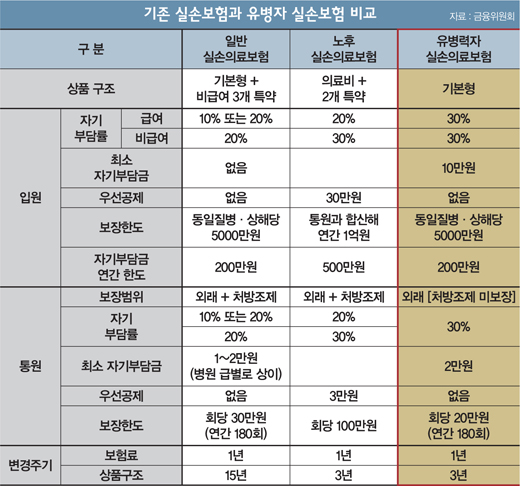
Since its first release in 1999, expense insurance has seen significant changes in coverage content and out-of-pocket cost structures depending on the time of enrollment. 1st and 2nd generation products were designed to be advantageous for policyholders with high medical usage frequency, as they had little to no out-of-pocket costs for hospital bills. However, as loss ratios surged, insurance companies gradually revised their products to increase out-of-pocket costs and control non-covered items. 3rd generation products attempted to suppress premium increases by separating non-covered medical treatments into special clauses and raising out-of-pocket costs.
Recently sold 4th generation and latest products have introduced a structure where premiums are discounted or surcharged based on the volume of non-covered item usage to prevent moral hazard. Therefore, if you are generally healthy and rarely visit the hospital, the latest products may be advantageous. However, for chronic disease patients who frequently require hospital treatment, maintaining their existing products is far more beneficial. If you switch to a product just because others say it is good without accurately understanding these generational differences, you may end up with only increased fixed monthly costs. You must first reflect on your usual health status and hospital usage habits and clearly grasp the pros and cons of your current contract.
Expense insurance varies significantly by generation in terms of out-of-pocket costs and non-covered item coverage methods, so you should carefully compare options based on your hospital usage tendencies.
2. What to Consider Before Canceling Existing Expense Insurance and Switching

When canceling an existing contract and switching to a new expense insurance policy, you must never make the decision based solely on premium comparison. You need to carefully check the coverage scope, out-of-pocket costs, and renewal cycle of your current contract first. For example, older contracts often have higher limits for outpatient treatment costs or advantageous coverage for specific diseases. On the other hand, newly released products may have reduced coverage limits or higher out-of-pocket percentages, resulting in less perceived benefit when settling actual hospital bills.
If you blindly switch products due to recommendations from others or simple advertising slogans, you may fail to receive proper coverage when facing major surgery or illness later. In particular, as you age, insurance underwriting becomes stricter, and premiums for new products become more expensive, increasing the financial burden. Therefore, it is essential to objectively compare the value of maintaining your current contract with expected future hospital expenses. While you can refer to insurance comparison sites or expert opinions, the final decision should be made according to your health history and financial situation.
When canceling existing expense insurance, you must consider the risks of reduced coverage scope and premium increases due to aging.
3. How to Compare Premiums Using Korea Insurance Association Disclosure Data
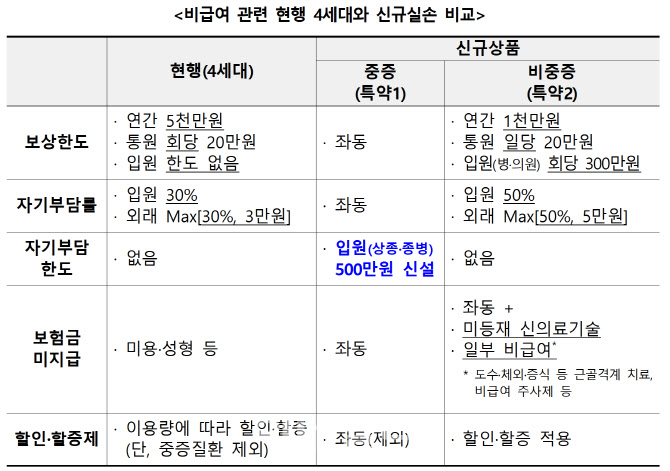
Using disclosure data from the Korea Insurance Association allows you to compare expense insurance premiums from each company based on objective criteria. By comparing prices from multiple insurance companies side by side based on the same age and gender, you can easily see which is cheaper. However, choosing a product solely because it has a low surface-level premium is risky; you must also examine detailed additional conditions and renewal cycles.
Since most companies adopt a renewable structure, even a product that is cheap right now may see a sharp increase in premiums after a few years. Therefore, you need the wisdom to comprehensively consider past loss ratio trends and the company’s financial soundness to choose a stable option. Utilizing internet comparison platforms allows you to narrow down the optimal product for you with just a few clicks, saving significant time. After carefully comparing conditions from multiple companies, you should proceed with enrollment at the one that offers the most practical coverage for you.
When comparing premiums using disclosure data, you should consider not only the immediate price but also the renewal cycle and the company’s stability.
4. Tips for Simple Expense Insurance Claims Without Cumbersome Documents
There are still many people who give up on claiming expense insurance benefits because preparing documents such as medical receipts and detailed statements is cumbersome. In the past, it was a significant burden for office workers to have to issue paper documents one by one from the hospital and send them by mail or fax. However, with the widespread adoption of simple claim systems linked to hospital computer networks, it can now be completed with just a few touches on a smartphone app.
Large hospitals and health centers have participated in document-free claim systems relatively early, greatly improving patient convenience. However, some local clinics and pharmacies have not yet completed the linkage, so it is necessary to check before visiting. Knowing how to make claims without documents in advance can help you receive reimbursements immediately when medical expenses arise, rather than putting it off, which can benefit your household economy. It is advisable to check if your frequently visited hospital supports the simple claim service and to install the smartphone app in advance.
Using the document-free simple claim system allows you to receive hospital bill insurance benefits much faster and more conveniently.
5. Checking for Duplicate Coverage with Travel Insurance and Daily Life Liability Insurance
When going on an overseas trip using a long holiday, it is important to carefully check the detailed coverage of travel insurance. Rather than simply comparing travel insurance premiums, you should check if the coverage overlaps with your existing expense insurance to prevent unnecessary expenses. Since expense insurance compensates for domestic and international medical costs proportionally to the actual costs incurred, you cannot receive insurance benefits from both sides even if you have duplicate coverage.
Additionally, in the case of special clauses like Daily Life Liability Insurance, it is often possible to receive compensation for damages caused to others even if only one family member is enrolled. While managing old insurance contracts, checking if such clauses are duplicated and organizing unnecessary parts can significantly save monthly premiums. It is also good to check the relationship with other products such as auto insurance or driver’s insurance to slim down your overall insurance portfolio. You should exercise the wisdom to stop leaking money through careful inspections and maintain only the necessary coverage robustly.
You should check for duplicate coverage with travel insurance or other contracts to reduce unnecessary premium expenses.
6. Final Recommendations for Smart Expense Insurance Management
Expense insurance plays a valuable role as a social safety net that reduces the burden of hospital bills in our lives, but if management is neglected, it can become a burden. Unconditional cancellation or blind switching is strictly prohibited; you need a mindset to coldly analyze your health status and financial situation. As medical technology advances and systems change, the insurance environment will continue to change, making periodic checks essential.
Do not be swayed by hearsay from those around you; make wise judgments based on authoritative data and your actual hospital usage records. Take out your policy now, check the coverage content, and inspect for any unnecessarily leaking costs. Small attention and actions will accumulate to firmly protect our valuable assets from the big hospital bill bomb in old age. I recommend that you create an expense insurance management plan that fits you perfectly based on what you have learned today.
Thorough current situation analysis and periodic checks are the only way to prevent unnecessary premium expenses and secure practical coverage.
Frequently Asked Questions
=