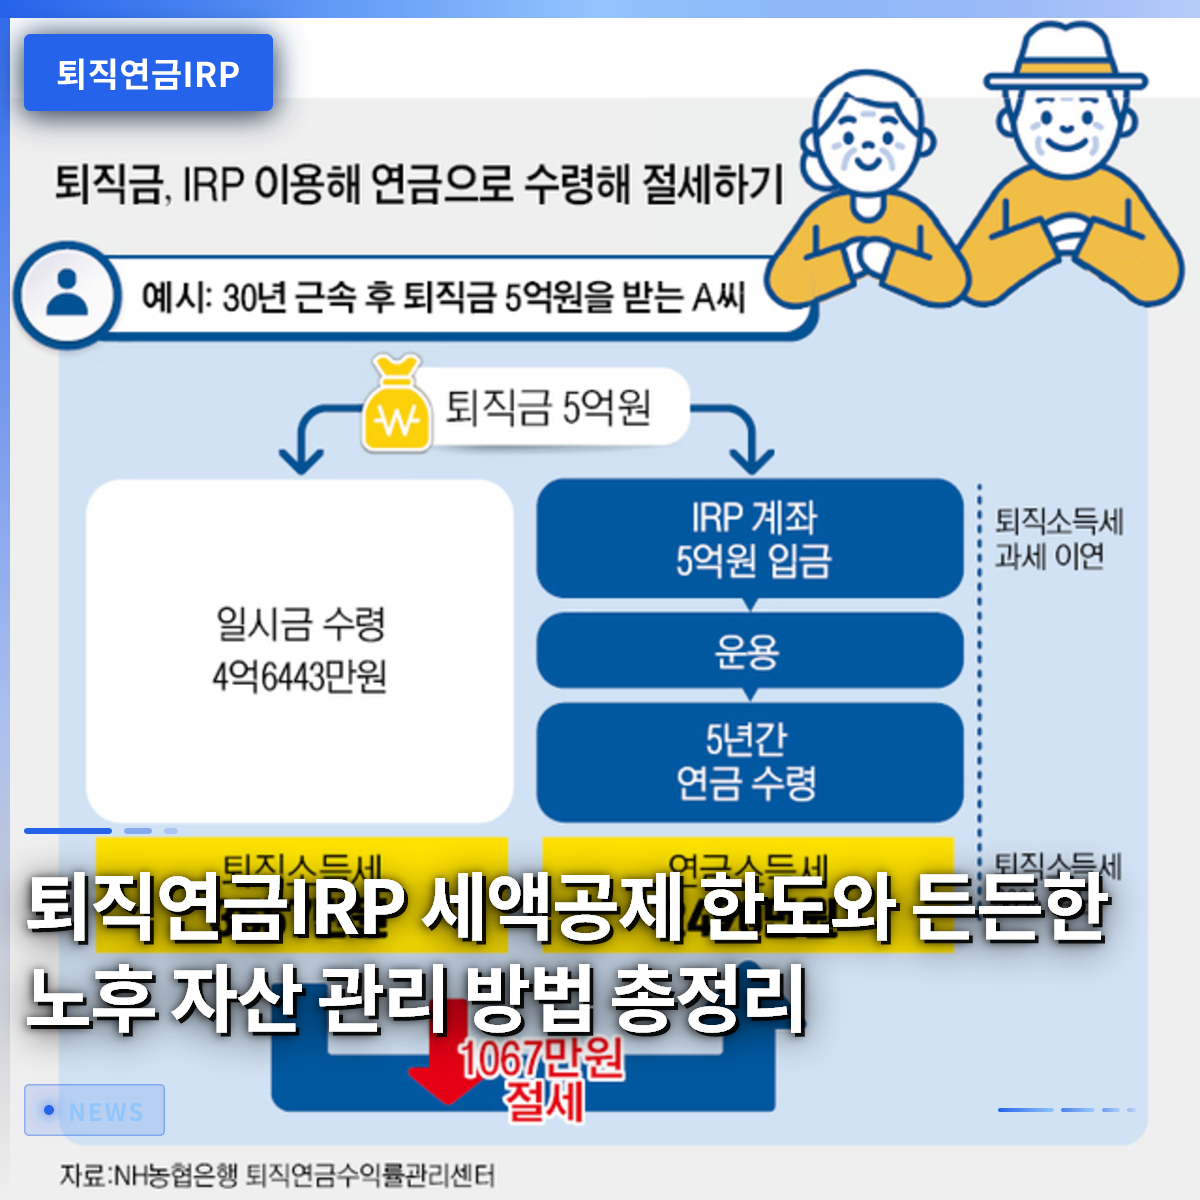
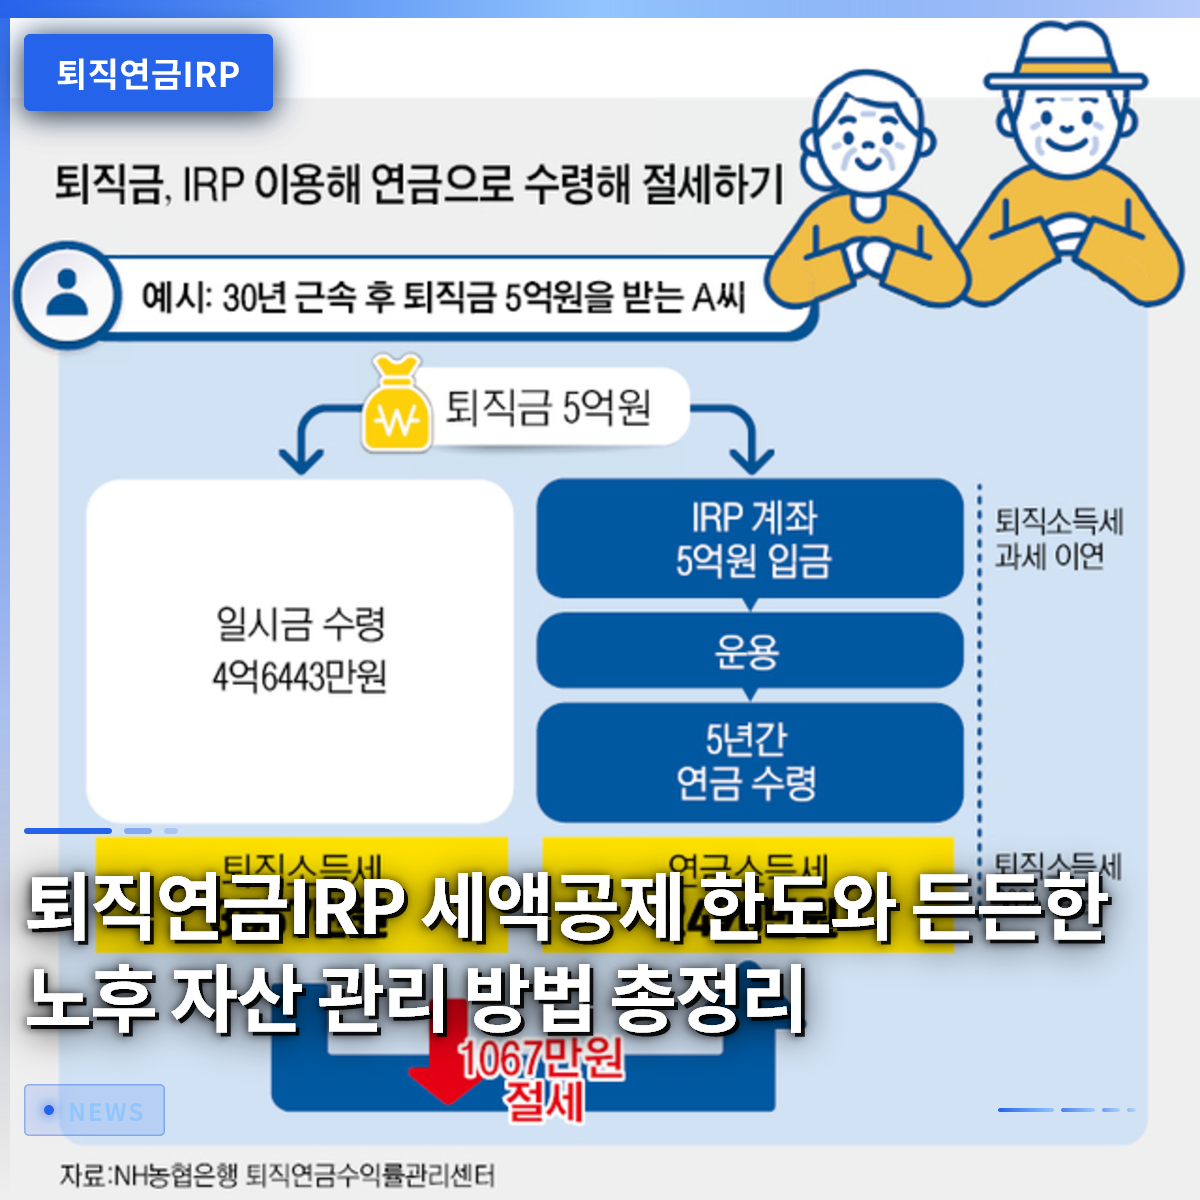
The Individual Retirement Pension (IRP) account is an essential financial product that not only provides substantial tax refunds during the annual tax settlement but also steadily grows your retirement funds. Mr. Kim, an office worker, regretted taking a “tax bomb” last year after failing to actively utilize his pension account. This year, he has committed to automatically transferring a fixed amount to his IRP account on his monthly payday. While many people procrastinate due to the perceived complexity, anyone can easily manage their assets by accurately understanding the basic structure and benefits. Recently, various financial institutions have expanded benefits for subscribers, such as offering mobile gift cards as sign-up bonuses and improving the automatic transfer environment. In this article, we will thoroughly examine practical information, from how to maximize tax deduction limits to safe asset management strategies. A small habit started now can completely change your financial comfort during retirement.
=
Complete Guide to IRP Pension Tax Deduction Limits and Secure Retirement Asset Management
1. Building Your Pension Seed Money with Automatic Transfers on Payday

Just as you need to fasten the first button correctly for a coat to fit well, consistent contribution habits are most important for an IRP account. If you set up automatic deductions from your salary account on a specific date each month, you can experience the miracle of accumulating a significant sum without even thinking about it. For example, it is effective to automatically transfer a fixed amount to the IRP account immediately after your salary is deposited on the 25th of each month, and then diversify additional funds into a pension savings fund the next day. Building such a systematic structure helps naturally control consumption desires, greatly aiding asset formation. Relying solely on willpower to save often leads to plans falling apart due to unexpected expenses. Therefore, automatic transfers should be viewed not as an option, but as an essential mechanism for successful retirement preparation.
It is wise to determine the automatic transfer amount by considering your income level and annual contribution limits, ensuring it is a size you can maintain consistently without strain. Setting the amount too high from the start can burden your living expenses, potentially leading to the worst-case scenario of closing the account midway. Mr. Lee, an office worker, maintained automatic transfers of 500,000 KRW per month and managed to accumulate a substantial investment capital over a few years. The key factor determining the final size of your assets is not the size of the amount, but how long you can continue contributions without interruption. Please actively utilize the automatic transfer services provided by financial institutions to steadily build your valuable assets month by month. Even small amounts, when combined with compound interest and tax benefits over several years, can make a huge difference.
Setting up automatic transfers on a fixed date each month helps control spending and steadily accumulate retirement assets.
2. Smart Contribution Strategies to Maximize Tax Deduction Benefits

During the annual tax settlement season, office workers’ fortunes diverge, and the strongest “relief pitcher” at this time is the pension account offering tax deduction benefits. By filling up to the annual contribution limit for the combined IRP and pension savings, you can receive a significant refund depending on your income bracket. An office worker with a total salary of 50 million KRW who fills the limit completely can enjoy the luck of receiving a tax refund of several hundred thousand to over one million KRW annually. Saving on taxes is directly equivalent to boosting your rate of return, so it must never be overlooked in the wealth management process. We often see regrettable cases where people miss valuable refund opportunities because they are unaware of the tax benefits.
Since there is an annual contribution limit, it is better to carefully calculate your expected annual tax settlement amount and the remaining time, and make split payments in advance rather than lump-summing everything at year-end. If your contributions for the year are insufficient, you need a strategy to deposit a lump sum before year-end to maximize the deduction limit. Mr. Park checks his pension contribution records every autumn and fills in the shortfall to save taxes frugally. Actively utilizing the legal tax-saving measures provided by the state is the smartest shortcut to protecting assets in modern society. If you reinvest the tax-deducted amount, you can further maximize the compound interest effect.
Filling the annual contribution limit to receive a tax refund during the annual settlement and reinvesting it is the core of tax saving.
3. Everything About Deposit Insurance Limits and Safe Asset Management

Since this account handles your valuable retirement assets, you must carefully verify that your principal is safely protected before choosing a financial institution. Under the Deposit Insurance Act, general deposits are protected up to 100 million KRW per financial company, covering both principal and interest. Similarly, the portion of an IRP account managed in safe protected products, such as deposits or derivative-linked products, is safely protected up to 100 million KRW. Therefore, it is safer to diversify and manage your assets across multiple institutions considering the deposit insurance limit, rather than putting all your assets into one financial institution. Even if a financial institution goes bankrupt, the state guarantees the principal within the protection limit, allowing you to entrust your retirement funds with peace of mind.
However, just because safety is high does not mean you should put all your funds into deposits; doing so may cause your real asset value to drop as it fails to keep up with inflation. You must appropriately mix performance-linked products, such as equity funds or index funds, to satisfactorily boost long-term returns. Recently, various events are being held to benefit subscribers, such as waiving management fees or offering mobile gift cards, so it is good to seize these opportunities. You must accurately determine whether your investment tendency is stable or aggressive and construct a portfolio with appropriate proportions accordingly. Please complete a balanced asset management system by appropriately allocating safe deposits and high-yield investment products.
Check the deposit insurance limit per financial company and appropriately allocate safe assets and investment products to protect your assets.
4. Saving Neglected Pensions with the Default Option System
Many people forget about their enrolled IRP accounts and are shocked to see the low returns only when they reach retirement. In the past, if subscribers did not give direct management instructions, their funds were left in cash for long periods, eroding assets due to inflation. The Default Option system was introduced to address this drawback; it is a mechanism that automatically rolls assets into pre-designated products. If there are no management instructions from the subscriber for a certain period, investments are automatically made according to the pre-selected portfolio, preventing valuable assets from sleeping. This is a grateful system, like rain in a drought, for office workers who lack time to regularly check their accounts.
When choosing a Default Option product, you must carefully consider your retirement timing, the remaining period, and the level of risk you can tolerate. Young subscribers with decades until retirement are better off choosing somewhat aggressive products to actively pursue returns. Conversely, subscribers near retirement should choose stable products focused on principal preservation to reduce asset volatility. Mr. Choi delayed setting up the Default Option, only to discover later that returns were negligible, and he immediately changed to a portfolio suitable for him. It requires meticulous attention to periodically check how your pension account is currently performing and to designate appropriate products.
Use the Default Option, which automatically manages assets when there are no instructions, to prevent assets from being neglected.
5. How to Resist the Temptation of Early Withdrawal and Protect Your Retirement
When an urgent need for a lump sum arises, the IRP account you have been saving in is often the first thing people reach for. However, if you close this account midway for simple change of mind rather than unavoidable reasons, you face a terrifying penalty: you must return all the tax benefits you received. Since other income tax is imposed on the principal and management returns that received tax deductions, the actual amount you receive can be much less than expected. Mr. Jung previously closed his pension account boldly to secure a deposit for a house, only to receive a huge additional tax bill during the next year’s tax settlement, causing great shock. You must be careful not to make the foolish decision of destroying the sturdy fence of your retirement just to put out an immediate fire.
If you are in an emergency situation where you urgently need money, you should first check if it qualifies for legal exceptions such as home purchase or bankruptcy, rather than completely closing the account. Alternatively, you should develop the financial management habit of setting up a separate emergency fund to fundamentally block access to the pension account. Once a pension account is broken, it is difficult to restore, and the flow of compound interest is interrupted, dealing a major blow to your entire retirement preparation. Only by keeping the account intact until retirement can you receive the lower pension income tax rate and enjoy a fulfilling retirement. Those who wisely navigate immediate temptations and crises and finish the race are the ones who ultimately grasp economic freedom after retirement.
Early withdrawal can result in a massive tax penalty, so you must maintain the account until the end unless it qualifies for an exception.
6. Final Check and Action for a Secure Retirement Plan
Based on the content reviewed so far, it is most important to open and check your IRP account status right now. Please carefully verify whether automatic transfers are set up correctly and if your contributions are sufficient to fill the annual tax deduction limit. If you also take advantage of various sign-up events or fee reduction benefits offered by financial institutions, it can add a small boost to growing your assets. Consistently contributing and managing your account every month, even if a bit clumsy, is the sure path to a successful retirement, far better than making a perfect plan but not executing it. It is not a distant future story about retirement, but the small practices of the present that create a comfortable and leisurely old age. I sincerely hope that all readers who read this article will welcome an economically free and smiling retirement through wise asset management strategies.
Check your account today and practice consistent contributions and management to prepare for a stable retirement.
Frequently Asked Questions
=