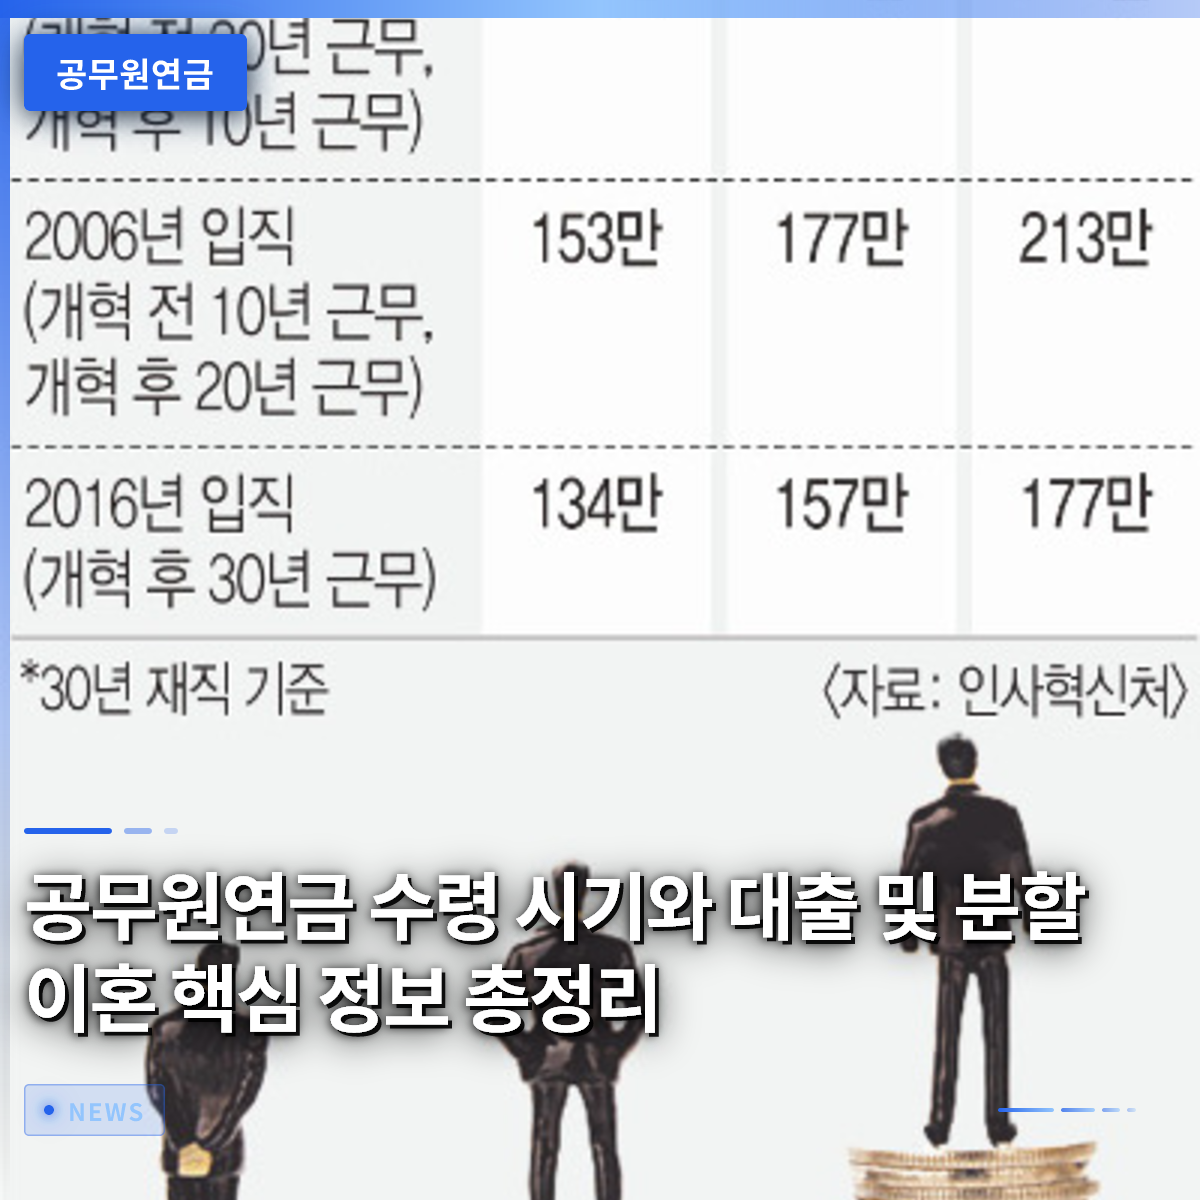
As the starting age for civil servant pension payments gradually increases, more people are facing income gaps after retirement, and related court rulings are emerging one after another. Hearing stories from senior civil servants who struggled financially for several years after retirement without receiving their pensions can be truly disheartening. I myself witnessed a close friend pacing anxiously for two years with no income after reaching mandatory retirement age, which made me acutely realize the importance of retirement planning. Today, we will thoroughly examine the changes in pension receipt timing, loan application methods, and property division issues arising from personal rehabilitation or divorce. If you have been confused by complex regulations, you will find definitive answers in this article. I encourage you to read through carefully and develop a strategy suited to your specific situation.
=
Comprehensive Guide: Civil Servant Pension Timing, Loans, and Divorce Property Division
1. Changes in Civil Servant Pension Eligibility Age and Strategies for Income Gaps

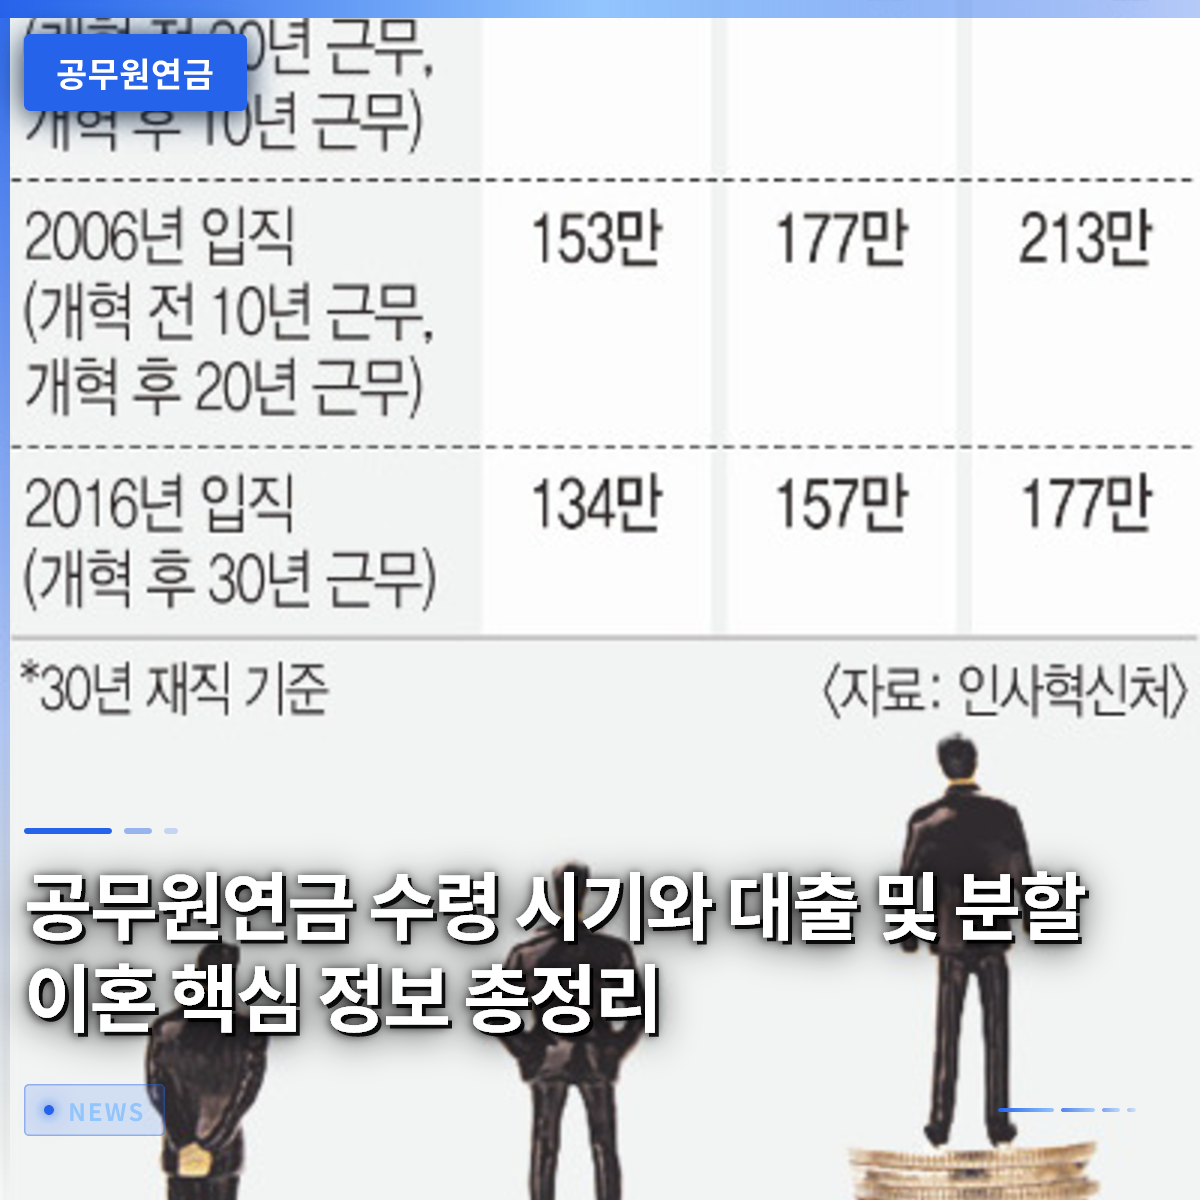
Unlike in the past, many retirees are now shocked to find that they must wait several years before receiving their civil servant pension. For instance, Mr. A, who reached mandatory retirement age, expected to receive his pension immediately after leaving his post. However, due to relevant regulations, he faced a gap of over a year before his pension began, which was a significant blow. There have also been cases where individuals filed lawsuits expressing frustration over the delayed payment, but the courts ruled that this does not constitute an infringement of property rights. Therefore, civil servants approaching retirement must absolutely prepare an emergency fund to bridge this income gap. If you cannot cover the gap through savings or other investment means, you may face severe financial hardship immediately after retirement, so special caution is required. The first thing to do when approaching retirement is to accurately determine the specific year you will start receiving your pension. The pension eligibility age varies depending on your initial appointment date, so vague guesses can lead to major mistakes. When discussing this with colleagues, you may find that some receive it immediately after retirement while others must wait several years, leading to complaints about fairness. However, since legal standards set by the state cannot be changed, it is wise to create a personalized financial plan. When utilizing flexible retirement options such as honorary retirement or merit-based leave, you must comprehensively consider the pension payment timing to avoid regret.
As the timing of civil servant pension receipt is delayed, you must accurately verify your individual payment age and plan your funds to prepare for the resulting income gap.
2. How to Utilize the Q4 2026 Civil Servant Pension Loan and Lending Schedule
When you suddenly need a large sum of money, utilizing the lending program supported by the Civil Servant Pension Fund can help you secure funds under more favorable conditions than banks. In the second half of this year, schedules for “Happy Leap” loans, housing acquisition loans, and general loans have been sequentially confirmed and are ready for implementation. Civil servant B, who urgently needed funds, was able to quickly apply and secure the money on this quarter’s lending application date because he had signed up for the notification service in advance. Had he not known about this program or missed the schedule, he would have had to rely on high-interest commercial bank products, incurring a heavy interest burden. Therefore, it is advisable to mark the schedule in your calendar so that your need for funds aligns with the Fund’s lending application period. When applying for a loan, you must carefully consider your available amount and repayment capacity to prevent excessive deductions from your salary later. The lending programs provided by the Fund have set limits, so during competitive quarters, you must act quickly as soon as applications open. Every time you hear of someone failing to secure a loan, you should treat it as a personal concern and prepare thoroughly in advance. Obtain necessary documents in advance and check your joint authentication certificate to avoid disqualification due to system errors on the day. While proper use of lending programs can relieve household financial pressure, excessive borrowing ultimately harms financial health, so a cautious approach is necessary.
You should grasp the Q4 2026 civil servant pension lending schedule in advance and sign up for notification services to securely secure the necessary funds.
3. Civil Servant Pension Attachment and Protection in Personal Rehabilitation Cases
For civil servants struggling with debt and considering personal rehabilitation due to financial difficulties, the safety of their pension is their primary concern. Mr. C, whose debt snowballed until he had to undergo rehabilitation proceedings, confessed that he lost sleep worrying about whether his lifelong pension contributions would be attached. However, according to relevant laws, the right to receive a civil servant pension is a public pension guaranteed by the state, and there are safeguards preventing general creditors from easily attaching it. Of course, cash already received and deposited in a bank account may be considered general property, so seeking specific legal advice is safer. Rather than being blindly anxious, it is wise to accurately understand the scope of the system’s protection and consult with an expert. Even if you proceed with personal rehabilitation, the pension received monthly is legally protected in most cases to ensure livelihood. However, when calculating rehabilitation repayment amounts, you must carefully assess how the current pension income affects monthly living expenses and debt repayment capacity. You should be cautious about acting based solely on hearsay from acquaintances, as this could result in failing to protect your valuable retirement assets. Getting a customized diagnosis through a law firm or counseling center that fits your situation is the shortcut to escaping the debt trap. Even if you are buried in debt, you must calmly navigate the difficulties, believing that the pension serves as a minimal safety net.
Even if you apply for personal rehabilitation, the right to receive a civil servant pension is legally protected, but caution is required regarding the receipt method and account management.
4. Everything About Civil Servant Pension Division and Property Division in Divorce
One of the most fiercely contested issues among couples who have decided to divorce after a long marriage is the division of the civil servant pension. In reality, Ms. D, who had been a housewife her whole life, was able to secure a stable retirement by claiming nearly half of the pension her husband would receive after retirement. In the past, the pension belonged entirely to the employed spouse, but now a system has been established that recognizes the contribution of the other spouse during the marriage and allows for division. To fully exercise your rights, you must accurately calculate the duration of the marriage and apply for pension division to the Fund with the help of a divorce specialist lawyer. During this process, the other party may strongly resist, so you should negotiate based on thorough evidence rather than reacting emotionally. Pension division can only be claimed if the marriage duration meets certain conditions based on the date of divorce, so you must carefully review the requirements. If you omit the pension item when determining the property division ratio during divorce litigation, it becomes very difficult to claim it separately later. Divorce specialist law firms in various regions, including Sejong City, are constantly receiving inquiries regarding pension division claims. You must remember that this is part of the joint property built by the couple and confidently demand your rightful share. If a smooth agreement is difficult due to deep emotional rifts, you must derive a pragmatic conclusion within the legal framework with an expert.
In divorce, you can proceed with a civil servant pension division claim by having your contribution during the marriage recognized, and you should verify the specific requirements in advance.
5. Utilizing Shinhan Bank Cashback and Pension Receipt Account Change Benefits
You can enjoy various cash benefits simply by receiving the four major pensions at a specific financial institution. Shinhan Bank is running a cashback event offering up to 50,000 KRW to customers who newly designate the receipt of the four major pensions, including the civil servant pension. While these financial events are often easily overlooked, taking advantage of such small benefits can provide a pleasant boost to your living expenses. In fact, Mr. E, who changed his retirement pension receipt account to Shinhan Bank, left a review expressing how delighted he was to receive an unexpected cashback. Since you can gain benefits with just an account change without much effort, active participation is advantageous. When changing your pension receipt account, you must ensure that utility bills and loan repayment accounts previously set for automatic transfer are also linked accordingly. If you change the account carelessly, automatic payments may be delayed, causing trouble, so you must check thoroughly in advance. Preferential interest rates and fee waiver benefits vary significantly among financial institutions, so it is best to compare them carefully and choose the most advantageous one. Since fixed income is limited after retirement, the wisdom to save and grow even a single won is paramount. I hope you use this opportunity to check whether your current pension receipt account offers the most favorable conditions.
You can receive up to 50,000 KRW in cashback benefits by newly receiving your civil servant pension at advantageous financial institutions like Shinhan Bank.
6. Retired Civil Servants’ Participation in Organizational Culture and Stable Retirement Outlook
The Civil Servant Pension Fund is adding warmth to society by delivering donations raised through various organizational culture improvement campaigns involving its employees to vulnerable children. In addition to such positive internal changes within the Fund, there is a continuing trend of increasing programs that make life after retirement more valuable. Civil servants approaching or already in retirement are actively participating in volunteer work and social contribution activities, designing fulfilling second lives. I myself was able to overcome my fear of old age by watching retired seniors around me live vibrantly while realizing social value. In the future, the pension system will continue to evolve in a direction that ensures financial soundness while enhancing the welfare of recipients. To remain steady amidst changing systems, you must develop the habit of periodically checking your asset status and pension receipt timing. Rather than blaming an uncertain future and feeling anxious, those who prepare one step ahead based on accurate information will ultimately be the winners. I hope you deeply remember the topics discussed today, from civil servant pension loans to divorce division and income gap preparation, and put them into practice. Although the massive life transition of retirement may feel unfamiliar and frightening, with thorough preparation, you can fully embrace a beautiful period. We will continue to be your reliable retirement partner based on useful and accurate information, so please keep your interest and watch us.
You should proactively prepare for a stable post-retirement life by paying attention to various institutional changes and social contribution activities related to the civil servant pension.
Frequently Asked Questions
=