A shocking controversy has surfaced regarding the manipulation of medical records, where hospitalization clearly deemed necessary after varicose vein surgery is suddenly reclassified as unnecessary during the process involving insurance companies and intermediaries. As even the careful assessments made by attending physicians are being reversed, calls are growing to overhaul the current medical consultation intermediation structure, which is heavily influenced by the entities responsible for paying insurance claims. The Standard Internal Control Guidelines for Medical Consultations, established in 2021, remain merely voluntary guidelines without any binding force, rendering them ineffective in practice. This article aims to thoroughly expose the dark side of medical consultations, which are being abused as a means to cut or deny surgery and hospitalization costs. We will carefully examine what institutional safeguards are urgently needed to ensure that policyholders do not suffer undue disadvantages. Readers may find themselves reflecting with a start on whether there were any loopholes in the consultation process for the insurance policies they currently hold.
=
Controversy Over Manipulation in Varicose Vein Cases: How Medical Consultation Intermediation Is Turning Necessary Hospitalization into “Unnecessary”
1. The Truth Behind the Case Where Varicose Vein Hospitalization Was Deemed Unnecessary
Recently, a bizarre incident regarding the appropriateness of hospitalization for patients who underwent varicose vein surgery has caused a major stir in the medical and insurance industries. The attending physician, who actually performed the surgery and directly examined the patient, stated that hospitalization was absolutely necessary. However, for some reason, this assessment was completely reversed as the case passed through the insurance company and the medical consultation intermediary. After going through the intermediary, the result was absurdly transformed into a finding that there was no evidence to support the necessity of hospitalization for the patient in question. This situation reveals a structural contradiction that occurs too frequently to be dismissed as a simple individual error or mistake. It means that the legitimate medical judgments of patients and doctors are being flipped as easily as a piece of paper, depending on the interests of the companies that must pay the money. From the patient’s perspective, they are facing the double burden of enduring physical pain for treatment only to have their insurance claims rejected. Ultimately, this incident has made it impossible to avoid the criticism that the current medical consultation system has degenerated into a tool representing insurance company interests rather than protecting patients. This phenomenon, where clear medical opinions are distorted through the intermediation process, acts as a primary factor in undermining consumer trust.
A controversy has arisen where legitimate opinions from attending physicians regarding the necessity of hospitalization are distorted to be deemed unnecessary as they pass through intermediaries.
2. Unfair Medical Consultation Intermediation Structure Swayed by Insurance Company Influence
The fundamental reason why the current medical consultation intermediation structure produces such biased results lies in the flow of funds and operational methods. The majority of medical consultation intermediaries currently in operation rely entirely on intermediary fees paid by insurance companies to cover most of their operational costs. Since the insurance companies are the ones providing the funds, intermediaries face structural limitations that make it difficult for them to confidently present results that are unfavorable or contrary to the insurance companies’ interests. Consequently, intermediaries, who are not free from insurance company influence, are motivated to compromise the objectivity of consulting physicians and induce or manipulate results in a direction favorable to the insurance companies. If this unreasonable structure is left unchecked, countless policyholders will inevitably suffer the harm of having their legitimate rights stripped away without understanding why. The existing Standard Internal Control Guidelines established by financial authorities lack substantial behavioral regulations or penalty clauses, leaving them effectively in name only. Therefore, there are widespread calls for a comprehensive overhaul of funding methods and operational systems to ensure that intermediaries can perform their duties fairly without being tied to specific interests. In a structure where one must constantly look over one’s shoulder at the funding source, expecting truly objective consultation is as difficult as picking stars from the sky.
It is pointed out that objective and independent medical consultation is impossible due to the structural limitation of intermediaries relying on insurance company fees.
3. Limitations and Lack of Effectiveness of Standard Internal Control Guidelines Remaining as Voluntary Directives
The reason why the Standard Internal Control Guidelines, developed through collaboration between financial authorities and insurance associations, are not fulfilling their role is that they lack clear binding force. Regrettably, the guidelines established in the summer of 2021 remain at the level of simple voluntary control directives, meaning there is no appropriate way to sanction violations in the field. Because there are no legal grounds to impose penalties for violations, insurance companies and intermediaries do not feel the incentive to strictly adhere to them. To resolve this issue, the Financial Services Commission and the Financial Supervisory Service are deeply considering the option of incorporating these internal control guidelines into the higher-level Financial Company Governance Act. If the guidelines are brought within the legal framework, strong sanctions or penalties can be imposed for violations, thereby exerting much higher binding force. However, some voices express concern that if the loopholes in the internal control guidelines are left as they are while rushing to legislate, it could actually lead to the side effect of strengthening insurance companies’ authority. In particular, the scope of subjects subject to medical consultation is defined too broadly, leaving room for insurance company staff to use their discretion to send even clear opinions from attending physicians back for consultation. For the system to be properly established, detailed supplementary measures that can fundamentally block the abuse of power by insurance companies must be prepared alongside the introduction of penalty clauses.
The Standard Internal Control Guidelines, currently in the state of voluntary directives without legal binding force, risk only expanding insurance companies’ power, necessitating incorporation into higher-level law along with meticulous supplementation.
4. The Urgency of Introducing External Business Audits and an Independent Consultation Committee
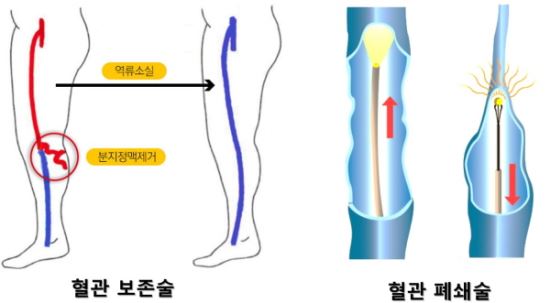
To restore the transparency and objectivity of the medical consultation system, the most urgent task is to establish a strong monitoring system for intermediaries. Experts advise that intermediaries should be mandated to undergo regular external business audits to ensure they do not have the motive or opportunity to manipulate results from the outset. Additionally, an independent consultation selection committee with no direct interest in insurance companies should be established to create a system where business is entrusted only to companies that have been fairly verified. If intermediaries are forced to transparently disclose not only the information of their affiliated hospitals but also the identities of the physicians actually handling the medical consultations, attempts to manipulate results unfairly can be significantly reduced. The current method, where insurance companies pay for consultations and induce results favorable to themselves, only invites strong distrust from policyholders. Only by transitioning to a rational system where a third independent institution can manage and control the consultation process can an environment be created where insurance consumers can feel at ease. A transparently disclosed consultation process will serve as a solid foundation for increasing the overall credibility of the insurance industry and correcting the practice of unfair insurance claim reductions. If monitoring mechanisms that ensure both independence and transparency are not put in place, controversies like the current one will continue to repeat endlessly.
The transparency of medical consultations must be ensured by mandating external business audits for intermediaries and introducing an independent consultation selection committee.
5. The Reality of Medical Consultations Degenerating into a Tool for Denying or Reducing Insurance Payouts
Criticism that the medical consultation system has been distorted into a practical means of saving or cutting insurance payouts, contrary to its original intent, is not a new phenomenon. In fact, it has been revealed that the percentage of cases where insurance was not paid or was reduced among all medical consultations conducted last year reached a staggering 28.3%. The labor costs of loss adjusters, medical consultation fees, and various legal consultation costs included in the net insurance premium are all managed by the insurance companies. It is difficult to avoid the criticism that insurance companies are abusing these substantial costs to artificially raise the fault ratio of accident victims or to refuse insurance payments. The fact that insurance companies use their discretion to request further medical consultation even after a doctor has concluded that treatment is absolutely necessary serves as evidence of this. Ultimately, patients are faced with the painful reality of having to wage a lonely battle against giant insurance companies to receive the insurance money they are rightfully owed. If this structural contradiction is left unchecked, the fairness of the entire insurance industry will be seriously compromised, and the damage will ultimately fall squarely on the backs of honest policyholders. It is truly time to break the vicious cycle where the medical consultation system is abused for the purpose of cutting treatment costs or insurance payouts.
The abuse of medical consultations as a means to deny or reduce insurance payouts has led to a side effect where the relevant ratio reached 28.3% last year.
6. Outlook and Challenges for Institutional Reform Toward a Healthy Insurance Market
To correct the controversy over medical consultation manipulation and the unfair intermediation structure, sincere efforts from financial authorities and the industry are more essential than ever. The legislation work on internal control guidelines being pushed by the authorities must be meticulously refined to possess substantial penalties and binding force, rather than remaining a mere formality. Of course, there are voices within the insurance industry expressing concerns about excessive regulations or the risk of fines, but increasing the transparency of the system is the path to building trust in the entire market in the long run. Reform centered on an independent third institution is needed so that policyholders no longer have their treatment costs rejected for unfair reasons or suffer mental distress. For the insurance policies we all hold to serve as a reliable barrier in times of crisis, we must expose the raw reality of the medical consultation process without omission and carry out major surgery on the system. We must keep a close watch on whether the specific legislation plans to be presented by financial authorities and the industry’s self-purification efforts will actually lead to substantive change. Until a transparent and fair insurance environment is established, policyholders must pay more attention to their own rights and raise their voices. We hope that reform plans to supplement institutional loopholes and strengthen independence will be quickly implemented, creating a fair society where patients can focus solely on their treatment.
Fundamental institutional reforms, including legislation and the operation of independent institutions, must be implemented promptly to establish a transparent and fair medical consultation system.
Frequently Asked Questions
=