A pension savings account is the most reliable financial tool for building retirement assets while receiving tax refunds ranging from hundreds of thousands to millions of won during the annual year-end tax settlement. Mr. Kim, an office worker who regretted not meeting the tax deduction limit at the end of last year, has set up automatic monthly transfers since early this year to consistently save. Unlike the past, when people simply kept their money in bank deposits, there has been an explosive increase in individuals directly purchasing high-quality U.S.-listed equity products or index-tracking funds through brokerage pension accounts. If your total annual income is 55 million won or less, you are eligible for a tax deduction rate of up to 16.5%, meaning the actual benefit of maxing out the limit is significantly larger than one might expect. In this article, we will go through specific tips for saving on taxes and maximizing long-term investment returns using a pension savings account. We will cover everything from opening the account and selecting products to realistic strategies for filling the remaining amount during the rest of the year.
=
How to Max Out the 9 Million Won Tax Deduction Limit in a Pension Savings Account and Invest in U.S. Stock ETFs
1. What is a Pension Savings Account?

A pension savings account is a representative tax-saving product and investment account created by the government to help citizens secure a stable retirement. In the past, pension savings insurance offered primarily by insurance companies was popular, but recently, brokerage pension savings funds, which allow individuals to directly trade stocks or exchange-traded funds (ETFs), have gained significant popularity. Not only office workers but also self-employed individuals and freelancers with income can join, and a major advantage is that anyone can open an account regardless of age. Since you can grow your funds while enjoying tax benefits, it is far more advantageous from a long-term investment perspective than using a regular securities account. You receive a portion of your income tax back based on a certain percentage of your annual contributions, making it a staple item in year-end tax settlements for office workers.
In particular, when trading various index-tracking products or bond products listed domestically within this account, profits are not taxed immediately; instead, tax payment is deferred until you receive the pension. This allows you to experience the magic of compound interest, where your principal and interest grow further, making it excellent for long-term asset formation. Instead of just envying colleagues who boast about increased refunds every year-end, you should open an account in your own name and take the first step right now. There is no need to overcomplicate things; simply download a brokerage app on your smartphone and open the account non-face-to-face, and it will be done in just a few minutes.
A pension savings account is a core tool for long-term asset formation that allows you to secure both tax benefits and investment returns.
2. How to Utilize the 9 Million Won Tax Deduction Limit

When combining personal pension savings and individual retirement pensions (IRP), you are given an annual tax-deductible contribution limit of up to 9 million won. A pension savings account alone can be recognized for up to 6 million won, and the remaining 3 million won can be filled by making additional contributions to an individual retirement pension account. If your total annual income exceeds 55 million won, a deduction rate of 13.2% is applied, allowing you to receive a maximum refund of 1.188 million won. If your income is 55 million won or less, a rate of 16.5% is applied, allowing for a maximum refund of 1.485 million won. For office workers who have taxes deducted from their paychecks every month, this amount is a precious refund, like a ray of sunshine in a drought.
Many people rush to deposit a lump sum only when the year-end approaches, or they regret not meeting the limit. Even if you don’t have much spare cash, adopting a method of making small contributions monthly can significantly reduce the burden on your household budget while naturally filling the limit. For example, to fill the 6 million won pension savings limit, you can set up an automatic transfer of approximately 500,000 won per month. If you find yourself in October or November, calculating the remaining amount and feeling panicked, you can consider a strategy of concentrating your efforts to fill the shortfall during the remaining three months. It is important to accurately assess your income level and financial situation and maintain a level you can afford each month, rather than forcing yourself to max out the limit.
By combining 6 million won in pension savings and 3 million won in individual retirement pension, you can fill the 9 million won limit and receive a refund of over 1.48 million won.
3. Investment Strategy for U.S. Stock Index Products
Recently, many investors are actively purchasing products that track major U.S. indices using their pension savings accounts. This is because systematic investing in indices that include a large number of global blue-chip companies leading the artificial intelligence and semiconductor industries can be expected to yield excellent long-term results. In fact, the net asset size of major U.S. index products from domestic asset management companies has grown enormously as massive funds from individual investors have poured in. Rather than trading for short-term price differences, a strategy of buying stocks on a fixed date each month is effective for lowering the average purchase price without being shaken by market volatility.
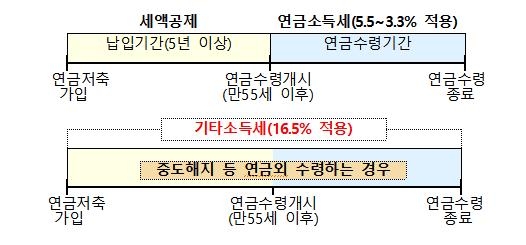
If you trade foreign stocks directly in a regular account, you must pay 22% capital gains tax on your profits. However, if you trade within a pension account, you can defer this tax until the time of pension receipt. The pension income tax rate paid when receiving the pension in retirement is much lower, ranging from 3.3% to 5.5%, making it overwhelmingly advantageous from a tax perspective. The younger the office worker, the longer the time available to enjoy these compound interest effects and tax benefits, making it difficult to find a better tool for building retirement assets. Set it up so that a fixed quantity of U.S. index products is automatically purchased on your payday each month, and as you focus on your daily life, you will find yourself facing surprisingly grown assets a few years later.
Systematic investing in U.S. index products through a pension account allows you to enjoy both tax deferral and low-rate taxation benefits.
4. Tips for Transferring Matured Funds and Additional Contributions
When the maturity of a common personal asset management account (ISA) seen around you approaches, many people worry about how to manage that money. Instead of simply withdrawing the matured funds to a regular account for use, transferring them to a pension savings account within 60 days of the account maturity date opens up a huge opportunity to secure additional tax deduction benefits. You can receive an additional tax deduction on 10% of the transferred amount (up to a maximum of 3 million won), meaning even those who have already maxed out their limit can enjoy tax-saving effects once more. Smart office workers who make good use of this system organically link multiple tax-saving accounts to maximize the efficiency of asset growth.
For example, if you transfer the lump sum from a matured account that you have diligently grown directly into a pension account, you can significantly boost your retirement funds at once while avoiding a tax bomb. However, when moving funds between accounts, you must be careful to follow the proper procedures within the designated period to fully receive the tax benefits. It is safe to consult directly with a bank or brokerage advisor or check the exact transfer method through a mobile app before proceeding. Simply knowing and practicing these small institutional differences can result in a sky-and-earth difference in the size of the assets you hold in your hands a few years later.
Transferring matured assets to a pension account within the designated period allows you to secure an additional tax deduction limit.
5. Precautions and Countermeasures for Early Termination
Since a pension savings account is a long-term product for retirement preparation, terminating it midway just because you urgently need money can result in significant losses. This is because you may be hit with a high tax of 16.5% under the name of miscellaneous income on the principal for which you received tax deductions and the profits accumulated so far. In reality, there are many office workers who regret having broken their accounts to receive year-end settlement benefits due to urgent needs for marriage funds or home purchase funds, only to face a tax bomb during the following year’s comprehensive income tax filing. Therefore, you should approach the money put into this account with the mindset that it is spare money you will absolutely not touch until retirement.
If you find yourself in a situation where you urgently need cash, it is wiser to look into partial withdrawal systems or utilize the contribution suspension function rather than terminating the entire account. Some brokerages offer services that reduce tax penalties in special circumstances or allow you to borrow only the amount you need temporarily, so you should check with their customer service. The best way to prevent termination is to thoroughly calculate your fixed monthly expenses and emergency fund when setting your monthly contribution amount, and to consistently deposit only an amount that does not leave you gasping for air. In the long game of retirement preparation, quitting midway is the greatest enemy, so you must establish a stable contribution plan.
Early termination requires returning the tax benefits received, so you should only contribute an amount you can maintain until retirement.
6. Final Recommendations for a Successful Retirement
So far, we have examined in detail the concept of pension savings accounts, tips for filling the tax deduction limit, and investment strategies through U.S. stock products. As average life expectancy increases and life after retirement becomes longer, simply piling money in a bank is no longer enough to overcome inflation and guarantee a comfortable retirement. If you save the seed money created by cutting back on a few cups of coffee a month and reducing unnecessary consumption, and steadily accumulate it in a pension account, your bank balance will be completely different in 10 or 20 years. Rather than blindly following trends just because others are doing it, it is most important to make a realistic plan tailored to your income and investment style.
During the remaining period of this year, calmly check your contribution status, and if there is a shortfall, please modify your automatic transfer settings right now. Small changes in habits will accumulate to become a sturdy shield that determines the quality of your life after retirement. The simple act of opening a brokerage app and checking your account balance is the most powerful starting point for investment that can change our future retirement. I sincerely encourage you to start your own solid tax-saving investment immediately based on what you have learned today.
You must prepare for economic freedom after retirement in advance through consistent accumulation and thorough tax-saving strategies.
Frequently Asked Questions
=