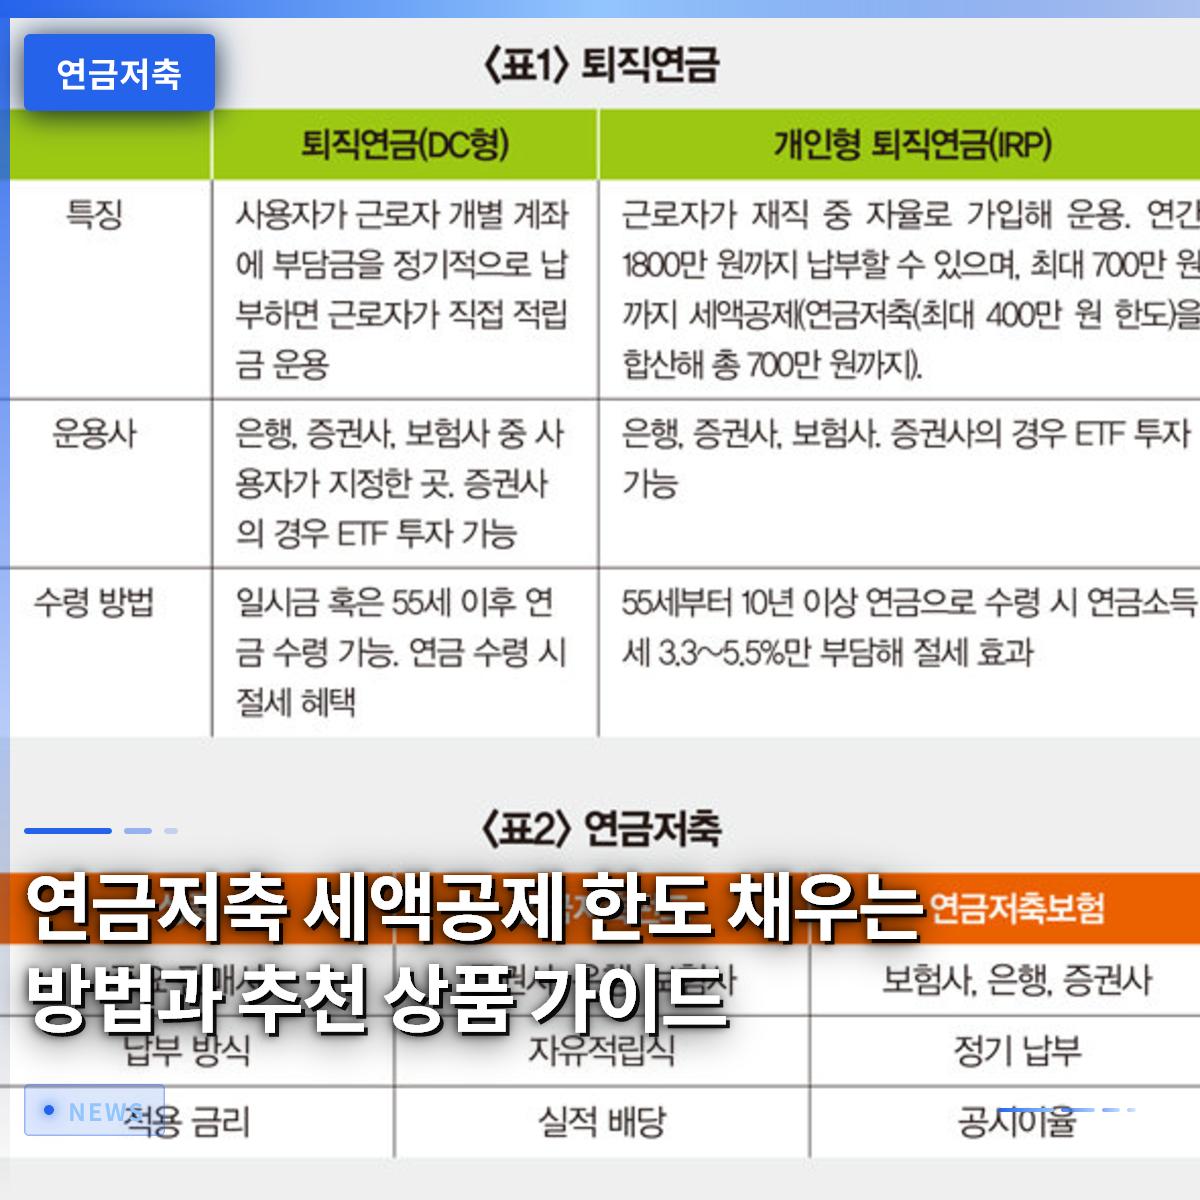
By utilizing a pension savings account, you can receive tax refunds ranging from hundreds of thousands to millions of won during your year-end tax settlement, so you should start immediately. Many people vaguely worry about life after retirement or postpone saving until they have more financial leeway, but the habit of preparing a little each month from a young age determines the abundance of your old age. In particular, if you are an employee, missing out on tax deduction benefits is the same as kicking away the subsidy provided by the state. From today, you should fill your account with the mindset of gifting your future self by saving the cost of a few cups of coffee each month. Let’s take a detailed look at a specific guide to maximizing compound interest effects and reliably reducing your tax burden. You will experience firsthand that preparing for retirement, which may have seemed overwhelming, is actually much easier and more enjoyable than you think.
=
How to Maximize Your Pension Savings Tax Deduction and Recommended Products Guide
1. Basic Concepts and Differences Between Pension Savings and Individual Retirement Pensions

Pension savings is a representative financial product for retirement preparation that any citizen of South Korea can join, offering tax deduction benefits on a certain percentage of the annual contribution amount. You can join through banks, securities firms, or insurance companies and pursue returns by directly investing in various assets such as funds or exchange-traded funds (ETFs) according to your investment style. In contrast, an individual retirement pension is a retirement asset management account that employed workers or self-employed individuals with income can join, making it a very familiar system for employees. Although these two accounts may look similar at first glance, there are subtle differences in eligibility, penalties for early termination, and the scope of asset management for investable products. Therefore, it is necessary to have the wisdom to accurately assess your income level and investment style and combine the two accounts appropriately. Rather than blindly following products that others say are good, it is most important to find the optimal combination that suits your financial situation. The synergy effect of managing both accounts together is far more powerful than you might think and makes a significant difference in your annual year-end tax settlement. If the limit for pension savings alone is insufficient, using an individual retirement pension as a supplementary tool can maximize the deduction limit. For example, Mr. Kim, an employee, splits a fixed amount each month between the two accounts and secures a substantial refund during his year-end tax settlement every year. Initially, he hesitated due to the burden of fixed monthly expenses, but thanks to setting up automatic transfers, he achieved his goal without significantly impacting his living costs. Utilizing such systems to build a forced savings habit can be called the surest shortcut to financial success. As retirement approaches, this ability to generate cash flow will determine your quality of life.
You must understand the differences between pension savings and individual retirement pensions to find the optimal combination for yourself.
2. The Smartest Way to Fill the Maximum Annual Tax Deduction Limit
When combined, pension savings and individual retirement pensions offer tax deduction benefits of up to 9 million won annually, so you should actively utilize this limit. Trying to gather a large sum all at once near the end of the year places an enormous burden on your household economy, so a strategy of consistent accumulation is essential. Setting up automatic transfers of a fixed amount immediately after your payday prevents money from slipping through your fingers and allows you to save naturally. Mr. Park, an employee, was able to naturally fill the annual limit without cutting expenses thanks to setting up automatic transfers on a fixed day each month. Once you experience the magic of compound interest from consistently saving even small amounts each month, you will finally realize the joy of saving. You must absolutely avoid the foolish act of canceling fixed deposits or using overdraft accounts to scramble for funds just before the year ends. There are many employees around you who regret it only after receiving a tax bomb at year-end due to unplanned spending. You can easily create enough room to save several hundred thousand won each month by slightly reducing coffee costs or unnecessary food delivery. Try to develop the habit of meticulously checking your household ledger and transferring that money directly into your pension account. You will be amazed to find that your account balance grows substantial and your anxiety about the future disappears. Those who fully enjoy the tax-saving benefits promoted by the state are true masters of asset management.
Instead of making a large lump-sum deposit at year-end, you should use automatic monthly transfers to fill the tax deduction limit without burden.
3. Powerful Tax-Saving Benefits When Receiving Pension After Age 55
While enjoying tax deduction benefits during the accumulation phase is a great pleasure, the low tax rate applied when receiving it as a pension after age 55 is the true privilege of a retiree. In general financial products, profits are subject to a 15.9% interest or dividend income tax, but pension accounts are subject to low-rate taxation ranging from 3.3% to 5.5%. This allows you to save significantly on taxes, becoming a powerful weapon to fully grow the compound interest effects from long-term investments into your own assets. For employees in their 50s who are close to retirement, the most urgent task is to prepare this stable cash flow in advance. After retirement, when fixed income disappears, the pension deposited into your account on a fixed day each month becomes an unshakable pillar that cannot be exchanged for anything else. Investing in stable products such as long-term government bonds or ETFs of high-quality US dividend stocks and reinvesting the dividends is the most effective strategy for growing assets. Since you can reinvest the annual dividends directly into the principal without worrying about taxes, the speed at which your assets grow accelerates sharply over time. It is difficult to feel the importance of compound interest in your younger years, but once you pass your 50s, you will feel with your whole body why long-term investing is the answer. Observing people around you who enjoy a financially comfortable life after retirement, you will find they all share a history of consistently maintaining their pension accounts from their younger days. Do not rejoice or grieve over immediate stock price fluctuations; instead, you must cultivate the insight to look at the massive mountain of assets ten or twenty years from now.
You can maximize the compound interest effect through the low-rate taxation applied when receiving the pension after age 55.
4. Recommended Financial Products to Invest in Pension Savings Accounts
A pension savings account is not just a place to deposit money in savings; it is a magic basket where you can invest in various assets such as stocks, bonds, and ETFs. Recently, products investing in the US semiconductor industry or global innovative companies have gained popularity and are being chosen by many investors. By selecting products with very low total expense ratios and investing long-term, you can save on fees and significantly boost your final return. For example, if you purchase a product investing in US dividend growth stocks in your pension account, you can catch both stable dividend income and stock price appreciation. For beginner investors, it is wise to build a portfolio focused on safe ETFs that track the overall market index rather than recklessly investing in individual stocks. By utilizing the mobile apps provided by each securities firm, you can easily incorporate high-quality assets from around the world into your account with just a few touches. In the past, you had to visit a bank in person and fill out complex documents, but now all asset management is possible comfortably from home with just a smartphone. By setting up automatic purchases of specific ETFs on a fixed day each month, you can completely escape the stress of checking the stock market every day. For modern people busy with work, such a hands-free automatic investment system is the key secret to making financial management sustainable. It is as if you have your own reliable economic secretary working 24/7, allowing you to focus on your main job with peace of mind.
You should increase the return rate of your pension account by using low-fee ETFs and global high-quality assets.
5. The Tax Bomb and Mistakes to Avoid When Terminating Early
Since pension savings is a long-term product, if you terminate it without thinking just because you suddenly need money, you may face the unfortunate situation of having to return all the benefits you have received so far. You must be extremely careful because a heavy tax of 16.5% is imposed as miscellaneous income tax on the principal and operating profits for which you received tax deductions. When you suddenly need a large sum of money, rather than terminating the entire account, you should first check for legally allowed unavoidable reasons or look for other methods such as contract loans. Many people get caught up in the sweetness of tax benefits and join, only to find themselves at a loss when they terminate the account due to an urgent need for cash. Therefore, you must start with the firm mindset that the money going into this account is money you will absolutely not touch until at least your retirement date. If major life events such as marriage or home purchase are scheduled, you also need the flexibility to adjust your pension account contributions to match your cash flow. You should be careful not to stretch your living expenses to forcibly fill the limit, as breaking the account midway will completely defeat the original purpose. Saving is like a marathon; if you push too hard from the start, you will likely get exhausted midway and fail to finish. If filling 9 million won in a year feels burdensome, it is wise to start with a realistic amount you can afford and gradually increase your contributions each year. Keep the truth in mind that consistency wins the game, and walk steadily toward the finish line of your retirement marathon.
Since heavy taxes are imposed upon early termination, you should design your plan with an amount you can consistently maintain until retirement.
6. Specific Action Strategies and Outlook for a Successful Retirement
Thanks to the government’s tax support policies and the high interest of the public, retirement preparation using pension savings has become not an option but an essential condition for survival. As an aging society accelerates, it goes without saying that the scale of individual retirement assets will be the absolute measure determining happiness in old age. Right now, turn on your smartphone, log in to your main securities firm’s app, open a pension account, and start setting up automatic monthly transfers. Small actions will accumulate and return to us as the great gift of economic freedom ten or twenty years from now. So that my future self can sincerely thank my present self, I must check my valuable asset management habits today and take immediate action. The most certain investment for enjoying a regret-free retirement life is starting pension savings right at this moment.
The small action of opening a pension account and starting automatic transfers right now creates future abundance.
Frequently Asked Questions
=