Personal pension savings accounts are the most reliable financial product for employees to secure the largest tax deductions during their year-end settlement while simultaneously building a solid retirement asset. Many people are maximizing the power of compound interest by investing in various financial products, such as exchange-traded funds (ETFs), beyond simple savings, helping them secure a stable life after retirement. Simply making consistent monthly contributions allows you to receive valuable tax refunds, establishing this account as an essential gateway to wealth management. Instead of just envying colleagues who smile while looking at their year-end tax refund statements, you should open your own account and start preparing right now. In this article, we will thoroughly cover everything from how to maximize tax deduction benefits to specific asset management strategies using ETFs. There is no need to be intimidated by complex financial terms; if you follow along step by step, anyone can easily embark on the path to becoming a retirement millionaire.
=
How to Prepare for Retirement: Personal Pension Tax Deduction Limits and Fund Investment Strategies
1. Basic Concepts and Eligibility for Personal Pension Savings

Personal pension savings are a representative long-term savings product that the government strongly supports with robust tax incentives to help individuals prepare for life after retirement. Any Korean citizen with income can join, and it can be effectively utilized not only by employees but also by self-employed individuals and freelancers, provided they can prove their income. The account must be maintained for a minimum of 5 years, and funds are received in the form of a pension after reaching the age of 55. While bank pension trusts and insurance company pension policies were the norm in the past, pension savings funds through securities firms have recently gained overwhelming popularity. Using a securities firm account allows you to directly invest in various index-tracking products and dividend stocks listed on the stock market, enabling you to grow your assets beyond the rate of inflation. This account is where the foundation begins for enjoying the magic of long-term compound interest by automatically transferring a fixed amount each month.
Manager Kim, a colleague in the office, has been consistently contributing 300,000 KRW to this product every month since his early career, following his mother’s advice. Initially, he felt frustrated that his funds were tied up, but his perspective changed completely when he started receiving refunds equivalent to half a month’s salary during the year-end settlement. He notes that as he gets older, his anxiety about retirement funds grows, and the mere existence of this account provides significant psychological peace of mind. The era of relying solely on bank interest is over; it is now a time when individuals must study and actively manage their assets.
Personal pension savings are a long-term tax-saving product requiring contributions for at least 5 years, with the goal of receiving pension payments after age 55.
2. Year-End Settlement Tax Deduction Benefits and Limits: A Complete Guide
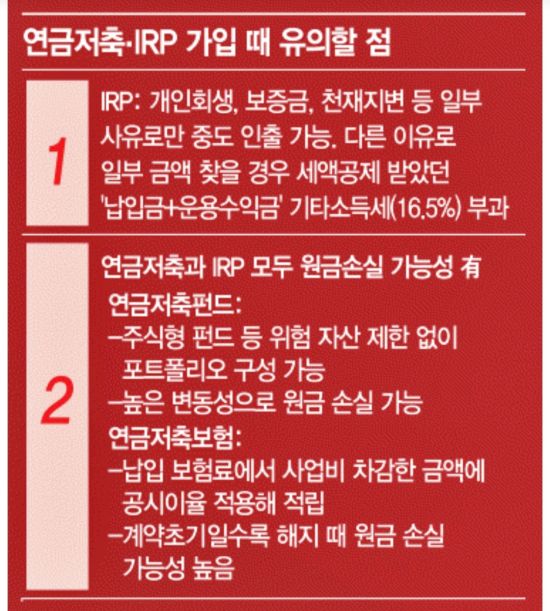
The most powerful weapon in the year-end settlement, often called the “13th-month salary,” is the combination of personal pension savings and Defined Contribution (DC) retirement pensions. Since the total contribution limit eligible for tax deductions across all pension accounts is up to 9 million KRW per year, you can maximize tax-saving effects. If your total annual income is 55 million KRW or less, you can receive a refund of 16.5% of your contributions, resulting in a significant tax saving of up to 1,485,000 KRW. Even if your total income exceeds 55 million KRW, a deduction rate of 13.2% applies, allowing you to receive a refund of up to 1,188,000 KRW, which is an excellent deal. Specifically, the deduction limit for personal pension savings alone is up to 6 million KRW per year, and by additionally utilizing an Individual Retirement Pension (IRP) account, you can fill the limit up to 9 million KRW. Since you can return money that would have gone to taxes directly into your account to use as principal for reinvestment, this system is a blessing for employees.
Assistant Manager Lee, who works in Seoul, checks for any shortfall in his pension account contributions every December and tops up the remaining amount in a lump sum to secure tax benefits. He typically sets up automatic transfers of 500,000 KRW per month to reach 6 million KRW, and in months when he receives a bonus, he adds extra funds to fully utilize the 9 million KRW limit. He has realized that the refunds accumulated over several years are enough to buy a decent used car, and he actively recommends this to his colleagues. Reducing taxes is equivalent to definitively increasing your rate of return, making it a fundamental principle of wealth management.
You can receive a high tax deduction benefit of up to 16.5% within the total pension account contribution limit of 9 million KRW.
3. Investment Strategies for Securities Firm Pension Savings Funds and ETFs

Since stable bank deposit interest rates are difficult to use to defend against inflation, pension savings funds managed by securities firms have recently become the mainstream. With a securities firm account, you can directly purchase ETFs that track domestic and international stock indices or products investing in dividend-growth companies. By using the regular purchase service, which automatically buys your desired products on a set date each month, you can accumulate stocks at favorable prices without worrying about every stock price fluctuation. If you hold products that pay dividends, distributions will steadily accumulate in your account, allowing you to directly see the compound interest effect of reinvestment. Since taxes on capital gains from stock trading are deferred until you receive the pension, there is no better environment for maximizing compound interest.
In practice, Mr. Park, an employee, deposits money up to the tax deduction limit each month and splits it equally to purchase ETFs tracking major U.S. indices and high-dividend stock products. He enjoys checking the dividend details in his account every month and visualizes his post-retirement life by watching the account valuation trend upward. This method of diversifying investments across the entire market, without the stress of picking individual stocks, allows him to manage his assets effortlessly while working. He is perfectly implementing the model answer for long-term systematic investing recommended by experts with just this one account.
By systematically purchasing ETFs in a pension savings fund account, you can enjoy both tax deferral and compound interest effects simultaneously.
4. Precautions for Early Termination and Pension Receipt Methods
Although it is a valuable account started for your old age, there may come a moment when you urgently need a large sum of money and seriously consider early termination. However, if you terminate a pension savings account early or withdraw funds in a form other than a pension, you must return all the tax deduction benefits you have received and will also be subject to miscellaneous income tax. A high tax rate of 16.5% is applied to the principal and investment returns that received tax deduction benefits, so you could suffer a blow greater than a loss of principal if you are not careful. Therefore, unless it is for a legally recognized unavoidable reason such as purchasing a house, paying a deposit, or long-term care, the best strategy is to never terminate early and hold the account until the end. When receiving the pension in the form of annuity payments after age 55, you should extend the receipt period to 10 years or more to apply the low pension income tax rate of 3.3% to 5.5%, thereby minimizing your tax burden.
Mr. Choi, an employee, emphasizes how important it is to accurately understand the nature of the system, having once talked a friend out of terminating his pension account due to a need for urgent cash. After returning the tax-deducted amount and paying taxes, one might feel self-reproach for why they worked so hard to save, so emergency funds should be kept in a separate account. When receiving the pension, rather than taking it as a lump sum, you should calculate the annual receipt limit and receive it in installments to avoid a tax bomb. Those who accurately understand the rules of the system and complete the long marathon will ultimately be the winners in the retirement market.
Early termination can result in a heavy tax penalty, so it is essential to receive the funds in the form of a pension after age 55.
5. Transferring Accounts to Other Firms and Utilizing Expert Discretionary Services
If you find a securities firm offering better returns or a financial institution with lower fees, you can transfer your existing account to another company without terminating it. By utilizing the account transfer system, you can maintain the continuity of tax benefits while moving your assets to your preferred institution to manage them under more favorable conditions. Recently, the securities industry has actively introduced discretionary services, such as pension savings wraps, where experts allocate and manage assets on behalf of customers to reduce the hassle of picking stocks. Investors who lack the time to pick stocks themselves or find it difficult to respond to market volatility should actively consider seeking this expert assistance. Utilizing financial platforms that provide various simulators and asset management report features allows you to regularly check your retirement preparation status and supplement any deficiencies.
Mr. Jung, an employee who found choosing complex financial products troublesome, recently visited a securities firm branch and transferred his assets to a discretionary pension product managed by experts. He said he found peace of mind because the expert checks and adjusts the portfolio for him, as his main job was too busy to monitor the stock market daily. The process of transferring the account was also much simpler than expected; he only had to fill out a few documents, and his previously accumulated benefits were carried over as is. Finding the financial institution and management style that suits you and consistently maintaining it is the key to successful retirement preparation.
You can transfer to a more favorable financial institution while maintaining benefits through the account transfer system, and you can also utilize expert discretionary services.
6. Long-Term Asset Management Outlook for a Successful Retirement
As the era of an aging population fully unfolds, it has become a reality that a comfortable retirement is difficult to imagine with only the public pension guaranteed by the state. Personal pension savings have now become not a choice but an essential survival strategy and the most reliable means of wealth management. The habit of consistently accumulating funds each month and investing in high-quality ETFs through a securities firm account creates a significant asset gap over time. There are not many products in this world that allow you to catch both the immediate sweet benefit of tax deductions and the solid cash flow after retirement. I hope you will turn on your smartphone right now to open an account or check your existing contribution limits and set up automatic monthly transfers. You should start planting the seeds for your future step by step from today, envisioning the you who will be smiling in ten or twenty years.
It is said that the biggest regret of seniors who have retired around us is not having prepared their pension assets in advance during their younger years. When you are young, the word “retirement” feels like a story from a faraway land, but time passes in the blink of an eye. A small action taken now can become a powerful magic that completely changes your future quality of life. I recommend joining the ranks of monthly systematic investors starting today, believing in the truth that the time you think it is too late is actually the earliest time.
Personal pension savings are the most reliable survival strategy for preparing for the aging era, and you should start immediately.
Frequently Asked Questions
=