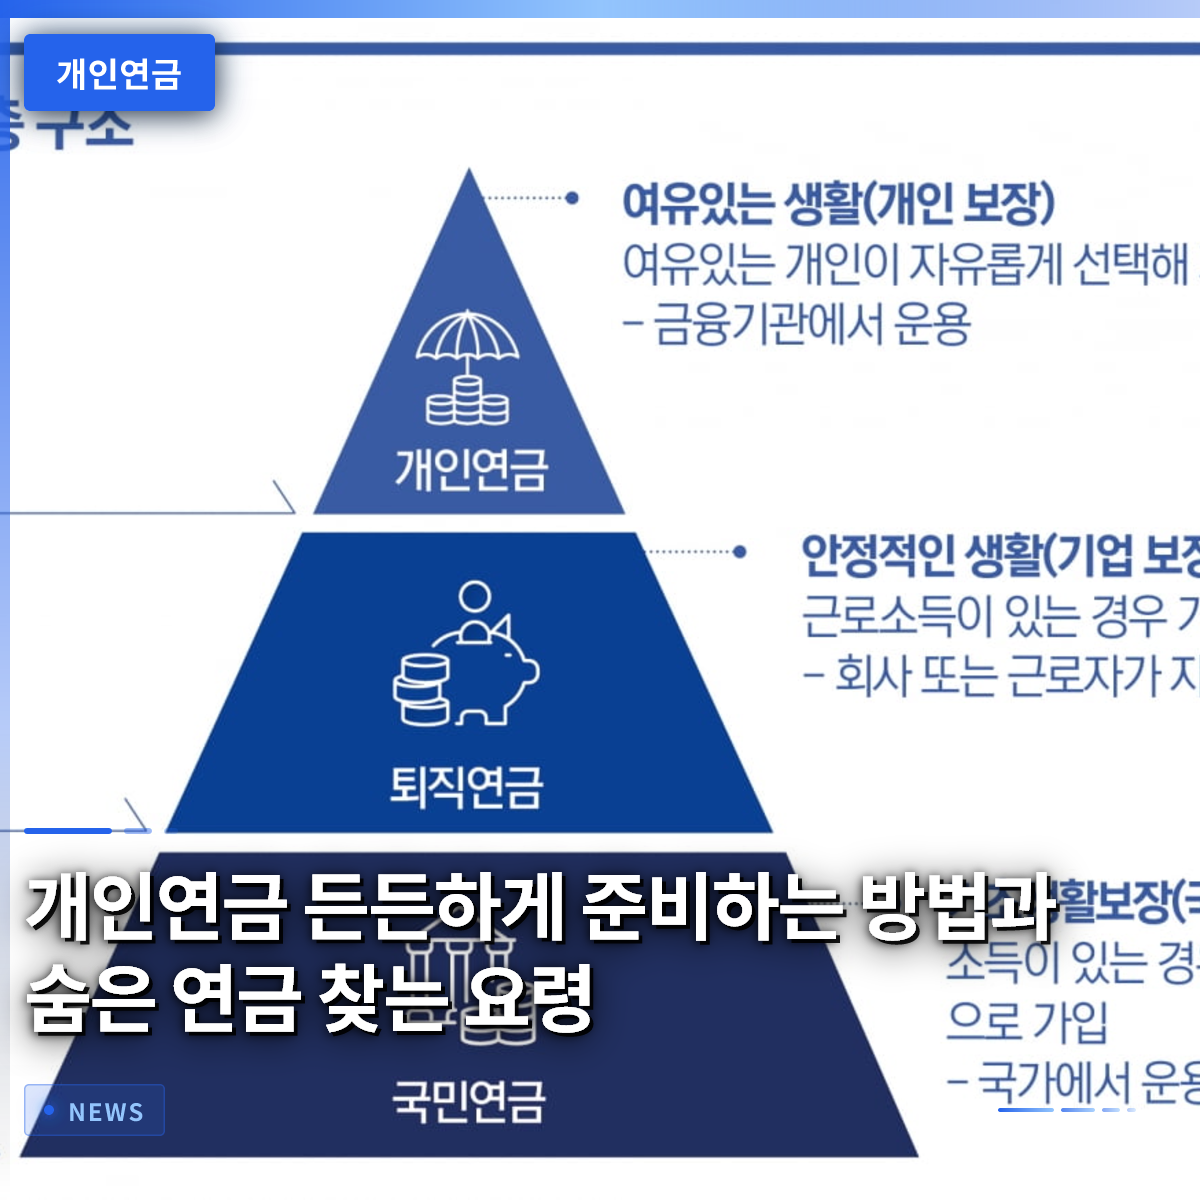
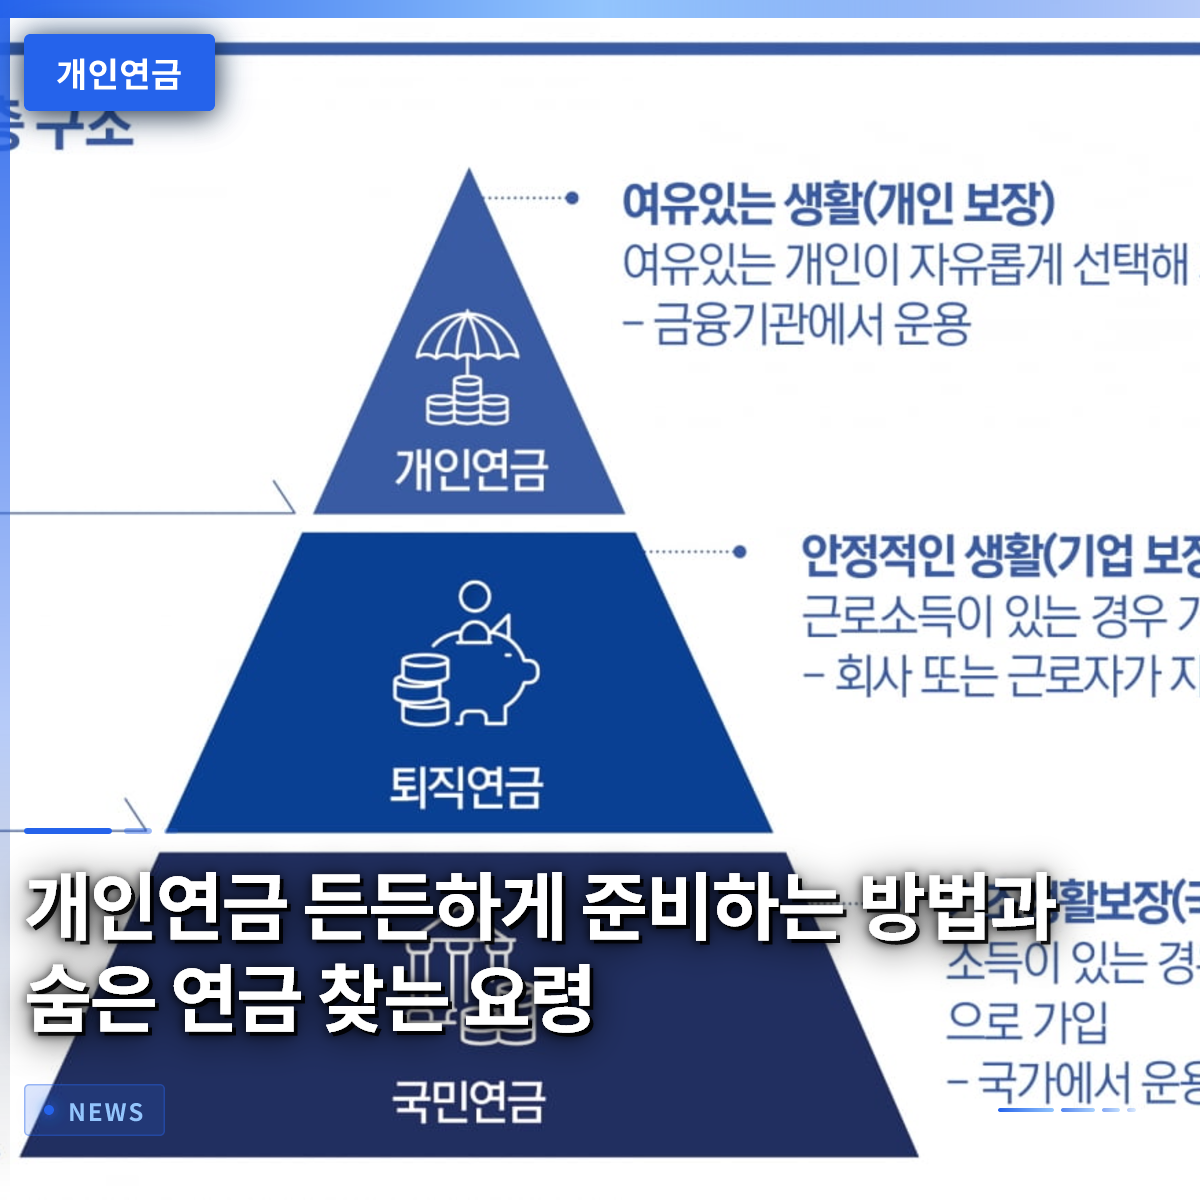
Preparing a personal pension has become a necessity rather than a choice to ensure a stable income after retirement. Many people face a gap between their retirement and the start of their National Pension benefits, or find their retirement funds insufficient due to expenses like repaying children’s student loans. This article details how to check your scattered personal pensions at a glance and offers tips for efficient investment management.
=
How to Securely Prepare Your Personal Pension and Tips for Finding Hidden Pensions
1. Why Relying Solely on the National Pension Can Be a Disaster

Retiring while relying solely on the National Pension is likely to lead to significant financial trouble. In reality, the National Pension benefit alone is often insufficient to cover basic living expenses like food, clothing, and shelter, given the pace of inflation. There is inevitably a gap period between leaving your job and reaching the age at which you can start receiving National Pension benefits. If you have no other income during this time, you may have to dip into your savings or take on debt to cover living expenses. In fact, many employees sigh deeply about this income gap after retirement. Therefore, a strong shield to supplement the National Pension is essential.
In the past, people believed that owning a house was enough to secure their retirement, but the situation has changed completely. House prices are high, but if you don’t have immediate cash on hand, it is difficult to cover medical bills or food costs. Families who did not prepare any personal pension because they were busy raising children and buying a house face even greater difficulties. In such cases, the Housing Pension system, which allows you to receive a monthly pension using your house as collateral, is a useful option. However, if all your assets are tied up in a single house, the flexibility of your asset management drops significantly. Only by consistently building up a personal pension from a young age can you ensure a peaceful life after retirement.
Since it is difficult to survive the post-retirement income gap with the National Pension alone, securing additional funds through a personal pension is essential.
2. How to Find Hidden Pensions Registered in Your Name

You might have a personal pension that you signed up for long ago and forgot about, sleeping in a corner of your financial life. If you have changed jobs or moved frequently, it can be difficult to remember which pensions you are enrolled in. Using the Integrated Pension Inquiry Portal Service allows you to check all your pension information scattered across various financial institutions at a glance. It is very convenient as you can view details such as the type of product, the accumulated amount, and even the expected benefit amount. It also covers retirement pensions or Individual Retirement Pension (IRP) accounts you may have opened while working at previous jobs.
You do not need to visit financial institutions one by one to find hidden pensions. After verifying your identity through a public certificate or simple authentication, all details appear on the screen within minutes. Many people are surprised to discover substantial accumulated amounts in unexpected accounts. These found pension assets serve as a benchmark for objectively evaluating your current retirement preparation status. Simply waking up dormant funds and reallocating them efficiently can be the start of a solid retirement plan.
Using the Integrated Pension Inquiry Service allows you to easily find your scattered personal and retirement pensions.
3. Why Chasing High Returns Can Lead to Regret and Alternatives

If you blindly sign up for high-yield products just because of rumors, thinking you are growing your retirement funds, you may face serious problems. Many individual investors lose their principal and suffer mental distress after impulsively investing in products solely because they have the highest recent returns. A strategy of regularly accumulating equity index funds (ETFs) on a fixed schedule, such as daily or weekly, is much safer. Major financial companies like Mirae Asset Securities and Kyobo Life are also expanding these systematic investment services to retirement and personal pensions. Consistently accumulating assets without being shaken by market volatility is the shortcut to winning in long-term investing.
When managing assets, you must avoid the foolish act of putting all your money into a single product. It is important to construct a portfolio by appropriately allocating stocks, bonds, and stable cash assets. In particular, products like variable insurance or pension savings should have their returns checked at least once a year. As market conditions change, the weight of your assets also shifts, making regular rebalancing necessary. Consulting with an expert or using a securities firm’s asset management platform allows for more systematic return management.
Instead of recklessly chasing high-yield products, you should enhance stability through periodic systematic investing and asset allocation.
4. Tax-Saving Tips to Avoid a Tax Bomb on Your Personal Pension
You should be aware that the tax structure changes if you diligently contribute to a personal pension and receive a large amount later. If your pension benefit exceeds a certain threshold, it may become subject to comprehensive income tax or increase your health insurance premiums. Therefore, while it is important to take advantage of annual tax deductions, you must also calculate the taxes at the time of receipt in advance. It is advantageous to strategically contribute to pension savings accounts and Individual Retirement Pensions (IRPs) to match the tax deduction limit. You can significantly reduce the tax burden by spreading out the timing of your pension withdrawals or adjusting the amount received after retirement.
Preparing pension products from a tax-saving perspective early in your career greatly helps in asset formation. If you delay retirement savings to pay off student loans, it can come back to haunt you later, eroding your finances. You need the wise habit of making small personal pension contributions simultaneously with debt repayment. You should carefully check tax benefits and ensure that the financial products you sign up for are suitable for your income level. Seeking help from a tax expert or using a tax-saving calculator on a financial platform is also a good method.
As pension benefits increase, the tax burden may also grow, so a tax-saving strategy considering the timing and limits of withdrawals is essential.
5. Comparison and Selection Guide for Various Pension Products
There are numerous personal pension products offered by various financial institutions, including banks, securities firms, and insurance companies. Bank pension trusts guarantee the principal but have low interest rates, making it difficult to keep up with inflation. On the other hand, securities firm pension savings funds allow for direct investment in various equity assets, expecting higher returns. Insurance company pension insurance is considered to have the greatest advantage in stability, as it allows you to receive a pension for life. You must accurately understand your investment style and retirement timing to choose the most suitable product type.
Recently, asset management companies are introducing various exchange-traded funds (ETFs) for individual customers, not just institutional clients. As financial markets offer wider choices, such as Kyobo Life transforming into a comprehensive asset management platform through its subsidiaries, it is essential to carefully compare fees and past returns of products from different companies and choose the one most favorable to you. Since you must maintain the account for a long period after signing up, you should also consider the penalties for early termination in advance. You need to make independent decisions by focusing on your economic situation rather than being misled by hearsay.
You should choose the right pension by comparing the characteristics of products from banks, securities firms, and insurance companies with your own investment style.
6. Practical Advice for a Successful Retirement
A personal pension is like a tower built brick by brick over a long period; it is not completed overnight. Small, practical steps, such as checking your current pension enrollment status and filling in the gaps, are important. You must never forget the truth that asset management habits in your youth determine the abundance of your old age. As AI-based asset management systems become more widespread, more precise pension design is expected to be possible. You should actively utilize these technological aids while maintaining an attitude of expanding your own financial knowledge.
Retirement comes to everyone, but the quality of life afterwards varies greatly depending on the preparation made. Build a solid framework of the three-tier pension system, encompassing the National Pension, retirement pensions, and personal pensions. You must create a solid economic foundation for yourself that will not waver even in unexpected post-retirement crises. Time is flowing rapidly even now, and the golden time for retirement preparation is gradually shrinking. Based on what you have learned today, I hope you will check and supplement your pension accounts starting tomorrow.
You should start preparing now for a stable and abundant retirement life through consistent pension management and systematic asset allocation.
Frequently Asked Questions
=