The Individual Retirement Pension (IRP) account is an essential financial product for employees, offering substantial tax deduction benefits during the annual year-end tax settlement. After being surprised by the refund amount from last year’s tax settlement, Manager Kim has started making consistent monthly contributions this year. Many people have joined IRP accounts simply because they heard it was a loss not to have one, but they often feel overwhelmed by the lack of clear information on specific benefits and how to manage the funds effectively. To achieve both retirement preparation and tax savings, it is crucial to understand the detailed regulations of the system and wisely allocate assets according to your investment style. Recently, as the government has pushed for reforms to the retirement pension system, there have been gradual changes in related laws and support measures. In this article, we will clearly explain everything from IRP eligibility and tax deduction limits to penalties for early termination and efficient asset management methods.
=
IRP Retirement Pension Tax Deduction Limits and 2026 Tax-Saving Strategies: A Complete Guide
1. What is an IRP and Why Should You Join?

The Individual Retirement Pension, commonly abbreviated as IRP, is a highly useful system that allows employees to accumulate their severance pay in an account under their own name when they change jobs or retire, and continue to invest it until retirement. Since you can make additional contributions with your own funds at any time while employed, it has established itself as a representative wealth management tool for office workers. While it was previously used solely for receiving severance pay, it has now become a core means of preparing for old age, actively encouraged by the government. For any employee looking to save even a little on their monthly taxes, joining an IRP is not just an option but a necessity.
Many people are confused about the difference between pension savings products and IRPs, but since both accounts offer tax deduction benefits within their respective limits, utilizing them together creates a significant synergy. You can easily open an account at any bank or securities firm, and non-face-to-face registration is also available through mobile apps. Manager Park, an office worker, was thrilled to receive a tax refund of several hundred thousand won in this year’s year-end settlement thanks to his combined contributions to pension savings and IRP last year. Similarly, by consistently accumulating funds during your working years and receiving them as a pension after retirement, you can significantly reduce your tax burden.
The IRP is an essential account that simultaneously handles severance pay storage and additional contributions while maximizing year-end tax savings.
2. Latest 2026 Tax Deduction Limits and Tax-Saving Effects

The most powerful weapon of the IRP account is undoubtedly the exceptional tax deduction benefit available every year. You can receive deductions up to the maximum annual contribution limit by combining pension savings and IRP contributions, with the deduction rate varying based on your total income. Employees with a total income of 50 million won or less are subject to a higher deduction rate, resulting in a much more tangible tax-saving effect. It is hard to find a better investment opportunity than saving a little each month and having the government return part of your taxes at the end of the year.
Manager Lee, who used to envy friends when they talked about their year-end tax refunds, has started making automatic monthly transfers to his IRP this year. Since a surprisingly large amount is deposited into his account at the end of the year, it also naturally cultivates the habit of forced monthly savings. However, you should set your contribution amount according to your income level, as trying to max out the limit too aggressively could lead to financial trouble if you suddenly need cash. By staying informed about annual tax law amendments and utilizing tax-saving seminars hosted by securities firms or banks, you can obtain the latest information faster than others.
The IRP is the core of tax savings, offering maximum tax deduction benefits on annual contributions when combined with pension savings.
3. What Happens If You Simply Terminate Your Account Upon Receiving Severance Pay?

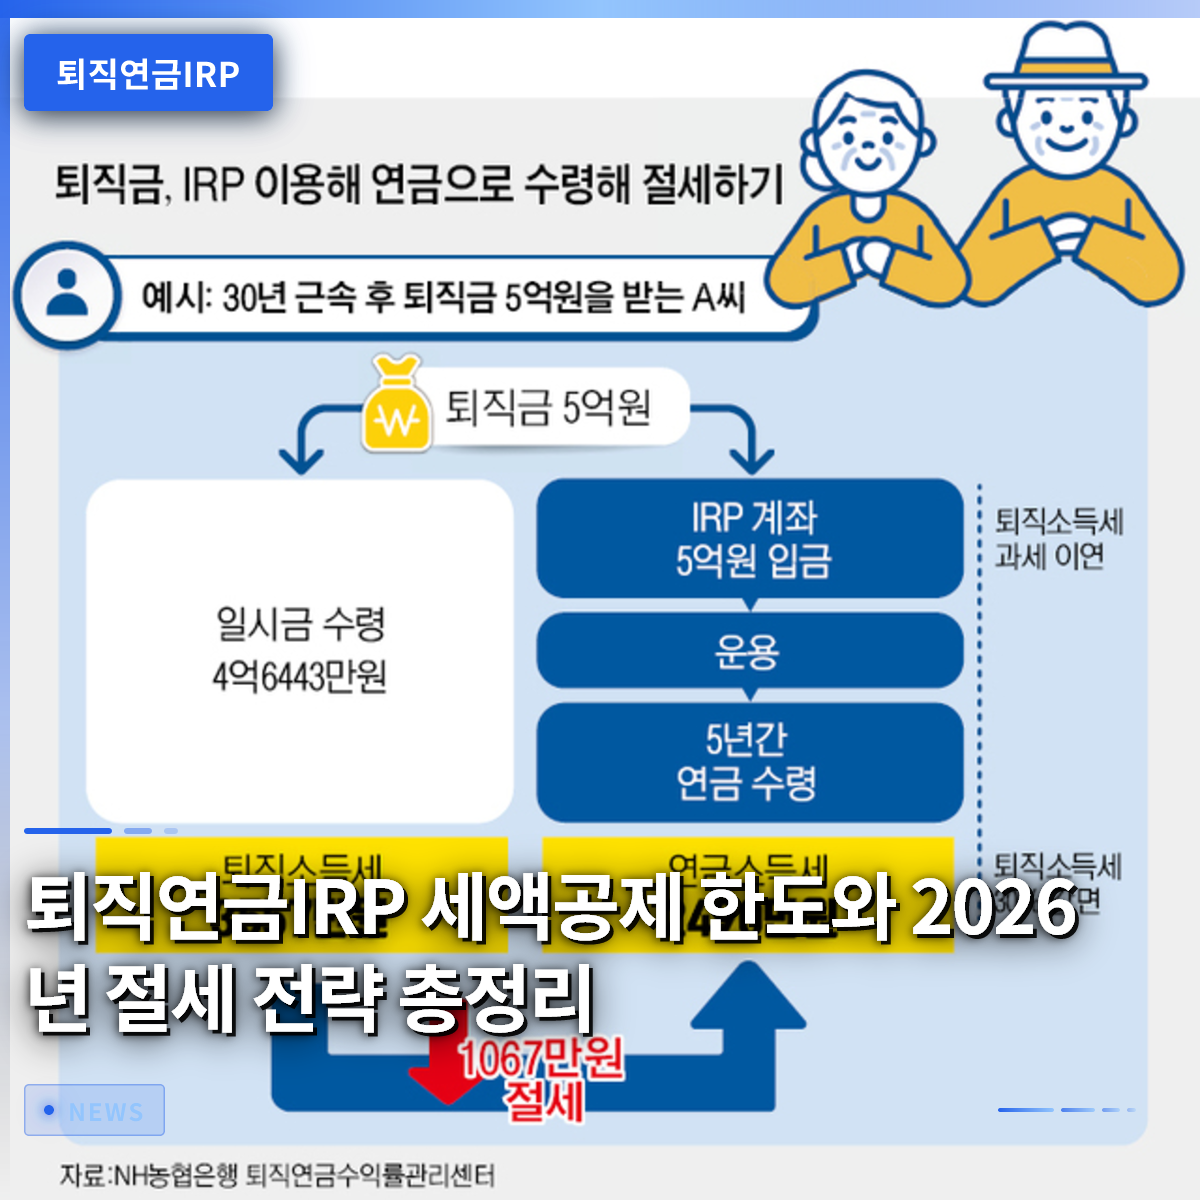
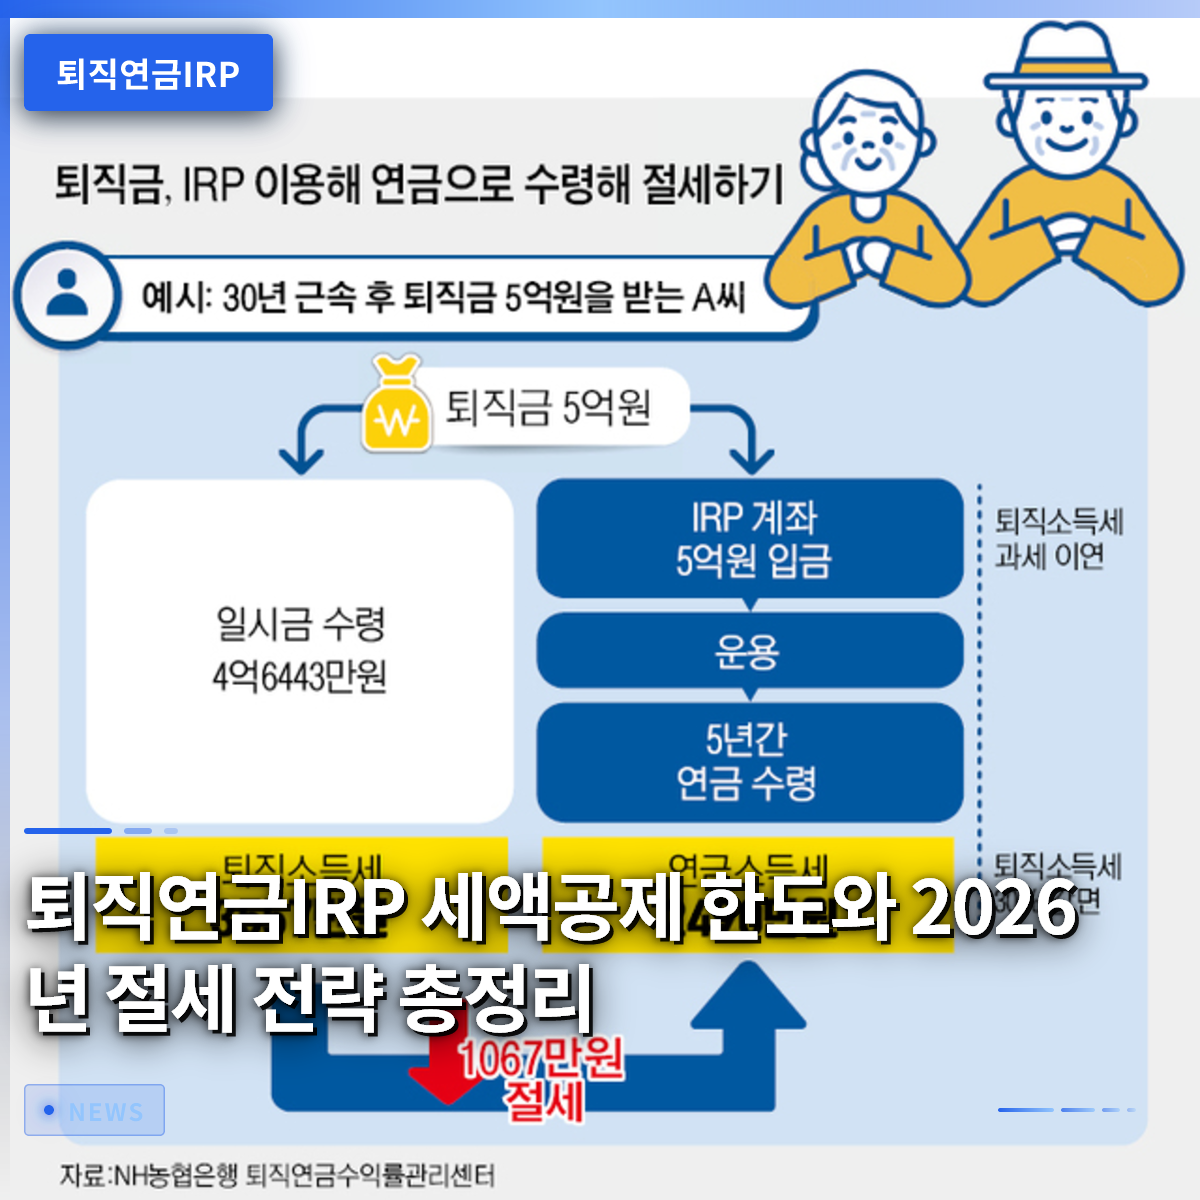
More people than you might think receive their accumulated severance pay as a lump sum when quitting or changing jobs and immediately terminate their IRP accounts. If you carelessly withdraw your severance pay into a regular checking account right after receiving it, you will be hit with a hefty severance income tax bill. To encourage employees to use their retirement funds in old age, the government offers a tax deferral benefit, delaying the taxation of severance pay transferred to an IRP account. Ignoring this benefit and breaking the account midway means you will have to pay all the taxes you had been saving at once, so it is absolutely something to avoid.
Manager Choi, a ten-year veteran nearing retirement, was shocked to see a senior colleague hit with a tax bomb after using their severance pay to buy a new car immediately. If you leave your severance pay in the IRP account, not only is the tax deferred, but if you receive it as a pension after age 55, you can receive a reduction of up to 30% on severance income tax. It is much wiser to choose a pension receipt method to minimize tax burden rather than rashly terminating the account just because you need a lump sum immediately. Even if you must use the funds, you should carefully review the exception clauses allowed by relevant laws and make a prudent decision.
Terminating your IRP account upon receiving severance pay eliminates the tax deferral benefit, leading to a massive tax burden; therefore, receiving it as a pension is advantageous.
4. Safe and Wise Asset Management and Utilizing Default Options
Opening an IRP account and just leaving the money there is not the end; the future size of your assets depends entirely on how you manage the accumulated funds. You should actively utilize the default option system, where funds are automatically invested in pre-designated products if the subscriber does not issue specific management instructions for a certain period. It is advisable to appropriately adjust the ratio of principal-guaranteed products to performance-linked funds based on whether your investment style is stable or aggressive. Recently, various financial products that use artificial intelligence technology to check and manage asset status daily have also emerged.
Staff member Jung, who has been interested in stock investing since the early days of his career, actively includes fund products in his IRP account to boost returns. On the other hand, his parents’ generation, who are close to retirement, focuses on protecting their assets by constructing a portfolio primarily of safe assets with no risk of principal loss. Regularly visiting the Integrated Pension Portal site allows you to easily compare your accumulated balance, long-term returns, and various fees, which is very convenient. You should also carefully consider the fee differences imposed by each securities firm or bank and choose a favorable institution to be advantageous in growing your assets in the long term.
Do not neglect your IRP accumulated funds; actively manage them through default options and style-based portfolios to increase returns.
5. Perfect Linkage Strategy with ISA Account Maturity Funds
There is an excellent system that those who have diligently saved money in an Individual Savings Account (ISA) and reached its maturity should pay attention to. When an ISA account reaches maturity, transferring those funds directly to an IRP account opens up a surprising opportunity to receive additional tax deduction benefits. Since a certain percentage of the maturity funds is added to the IRP contribution limit, you can maximize the tax-saving effect. This is a two-for-one strategy that allows you to save on taxes while securing ample retirement funds by moving a lump sum to a pension account.
When acquaintances worry about where to use their ISA maturity funds, telling them this method often makes them slap their knees in realization. It is much more beneficial to link your hard-earned seed capital, accumulated over several years, with a pension account for long-term investment rather than simply withdrawing and spending it. By utilizing webinars or consultation services provided by financial institutions, you can receive detailed guidance on how to link these accounts. Organically connecting ISAs and IRPs in line with tax law amendments and financial trend changes is the true secret to tax saving for the pros.
Transferring ISA maturity funds to an IRP allows you to effectively grow retirement assets along with additional tax deduction benefits.
6. Final Check for Successful Retirement Preparation
To make life after retirement comfortable and abundant, you need to make the effort to closely examine the status of your IRP account right now. As the government continues to discuss mandatory retirement pensions and structural improvements, those who quickly adapt to system changes will be the winners. Do not be stingy with monthly fees; instead, weigh long-term returns and tax benefits to maintain the most advantageous portfolio. Starting today, the small act of opening your smartphone app to check your pension balance and deduction limits will determine your future abundant life.
It is important to have an attitude of calculating your income and retirement timing accurately and contributing funds in a planned manner, rather than being swayed by rumors. The small pension assets you accumulate now will become a massive safety net in your retirement years, protecting you firmly. Based on the tax deduction limits and account linkage strategies learned today, we hope you will check your bank or securities firm app immediately tomorrow. Systematic preparation and consistent interest are the most certain keys to preventing retirement bankruptcy and welcoming a truly happy second half of life.
Consistent asset management through IRP and utilizing the latest systems is the most certain and safe path to a successful retirement.
Frequently Asked Questions
=