Pension savings funds offer tax deduction benefits on annual contributions of up to 6 million won, making them an essential wealth management tool for office workers. You may have opened an account simply because everyone around you was doing so, only to feel overwhelmed when it came time to decide which products to invest in. Many people leave their accounts dormant because they are unsure how much to save monthly to maximize their tax refunds. In this article, we will walk you through the basic structure of pension savings funds and specific contribution strategies to maximize the tax deduction limit. We will also look at a realistic case study of Mr. Kim, an office worker who grew his assets by regularly investing in high-dividend index funds. Let’s take a detailed look at practical methods to steadily build your retirement assets from a long-term perspective while reducing your tax burden.
=
Maximizing the 6 Million Won Tax Deduction for Pension Savings Funds: Complete Strategy and Investment Tips
1. What is a Pension Savings Fund and Why is it Essential for Office Workers?
A pension savings fund is a long-term retirement preparation account that allows you to invest directly in various equity assets and bonds through a securities firm while enjoying tax benefits. Unlike general pension savings trusts or insurance products opened at banks, it allows subscribers to directly select index funds or equity products, which is advantageous for defending against inflation. Since you can receive a tax deduction of up to 15 percent of your contributions during the year-end tax settlement, it acts as a substantial bonus for office workers. If your total annual income is 55 million won or less, you benefit from a higher deduction rate of 16.5 percent, allowing you to receive a tax refund of up to 990,000 won.
Mr. Park, an office worker who has been interested in wealth management since early in his career, deposits a fixed amount into this account every month and uses the year-end tax settlement refund as pocket money. While investing in a general stock account requires paying a 15.4 percent dividend income tax on profits, using a pension account allows you to defer this tax until you receive the pension. You can also enjoy the compound interest effect of reinvested taxes, meaning the speed of asset growth becomes noticeably faster over time. If you want to secure retirement funds while avoiding annual tax burdens, this is the top-priority financial product you should open.
Pension savings funds are the most reliable retirement preparation tool, allowing you to enjoy both tax deduction benefits and the compound interest effect from tax deferral.
2. Monthly Contribution Strategies to Maximize the 6 Million Won Tax Deduction Limit
The annual tax deduction limit for pension savings funds is 6 million won, which can be increased to a maximum of 9 million won when combined with an individual retirement pension. If you can only save exactly 6 million won a year, it is far more advantageous to focus solely on the pension savings fund without overcomplicating things. Individual retirement pensions are subject to supervision regulations that limit equity assets to 70 percent of the account’s evaluated amount. In contrast, pension savings funds have no restrictions on the proportion of equity assets, allowing those with aggressive investment tendencies to manage their funds freely.
Consistently contributing 500,000 won per month creates a structure where exactly 6 million won is accumulated over a year, allowing you to fully utilize the limit. For office workers who have just started their careers, it is better to start with a manageable amount of 300,000 won per month and gradually increase it rather than forcing a large amount from the beginning. If you have extra funds and wish to contribute more, you should turn to an individual retirement pension account after filling the pension savings fund limit. By managing these accounts separately, you can maximize tax benefits while ensuring complete autonomy in asset management.
Setting up an automatic transfer of 500,000 won per month to fill the annual 6 million won limit is the most realistic and effective tax-saving strategy.
3. Foolproof Systematic Investment Techniques and Asset Allocation
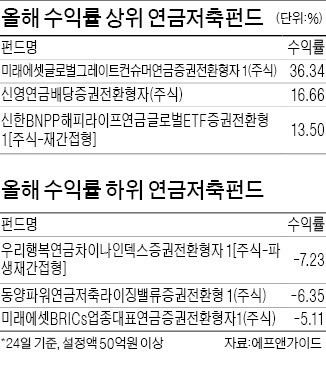
Once you have decided to contribute a fixed amount monthly, you need to create a concrete execution plan for which stocks to buy and how to accumulate them. To maximize the characteristics of a pension account, which requires long-term investment, you should use a dollar-cost averaging technique that automatically adjusts the quantity bought based on price fluctuations. This method reduces risk by buying more when the market falls and less when it rises, thereby lowering the average purchase price. In reality, many investors make the mistake of selling in panic when the index fluctuates, but a systematic approach allows you to endure market volatility with much greater psychological comfort.
Investors who prefer stable cash flow can create a structure where they buy domestic high-dividend stocks or index-tracking funds and reinvest the monthly dividends. Applying a “windmill” approach of using monthly distributions to buy more stocks leads to a geometric increase in holdings over time. Rather than betting everything on a single stock, you should construct a portfolio that mixes representative US indices and domestic high-dividend assets to lower volatility. Mechanically repeating purchases on a fixed date each month, without being swayed by emotions, is the only shortcut to long-term victory.
Systematic investment, which involves buying quality index funds in installments on a fixed date each month regardless of stock price fluctuations, minimizes the probability of failure.
4. Differences Between Pension Savings Funds and Other Tax-Saving Accounts and How to Use Them Together
The Individual Asset Management Account (ISA), which is popular among domestic investors, and pension savings funds have entirely different natures, so they should be used in parallel according to their respective purposes. The ISA has a maturity of 3 years, making it very advantageous for accumulating a lump sum over a relatively short period while enjoying tax-free benefits. On the other hand, pension savings funds are accounts exclusively for retirement funds after retirement, so if you terminate the account midway, you must repay all the tax benefits received. Therefore, if you need to increase your deposit for a rental house in 3 years or require funds for marriage, it is wise to utilize the ISA first.
Conversely, if you have more than ten years until retirement and want to focus solely on retirement preparation and year-end tax settlement refunds, pension savings funds have an absolute advantage. Smart investors transfer a portion of the lump sum received upon the maturity of their ISA to their pension savings fund to get an additional tax deduction as a bonus. By organically linking these two accounts, you can manage the funds needed for each stage of life while saving the most on taxes. You must remember that the return on investment and taxes vary significantly depending on which legal framework your valuable assets are placed in.
The completion of a tax-saving strategy involves using the ISA for short-term lump sum accumulation and transferring the matured funds to a pension savings fund.
5. Points to Note When Receiving Pension and How to Avoid a Tax Bomb
Even when you reach retirement age and start receiving your pension, you may face a tax bomb if you do not carefully consider the rules set by the state. If the annual pension receipt exceeds 15 million won, it may be subject to comprehensive income tax by being combined with other income instead of pension income tax, so caution is required. To avoid this, it is safe to calculate the upper limit of the monthly receipt amount precisely and formulate a strategy to receive it in installments over several years. Rather than simply withholding withdrawals to save on taxes, you should consistently withdraw an appropriate amount tailored to your post-retirement cash flow.
Additionally, even if you start receiving the pension after the age of 55, the condition for applying the lower pension income tax rate is only met if the subscription period exceeds 5 years. If you rashly terminate the account because you urgently need money, a 16.5 percent miscellaneous income tax will be imposed, potentially rendering your efforts futile. When you inevitably need to use the funds, instead of terminating the entire account, you should first withdraw the principal that did not receive a tax deduction. Since amounts that did not receive a tax deduction can be withdrawn without paying tax, knowing this tax knowledge in advance is very helpful.