If you desire a stable retirement, you must carefully compare the structure and conditions of pension insurance products right now. With the rapid progression of low birth rates and an aging population, the National Pension alone is no longer sufficient to fully support life after retirement. It is easy to see people around you struggling to decide where to invest their severance pay or surplus funds. In fact, many retirees are facing significant difficulties due to the burden of increasing medical and living expenses. It is more important than ever to safely preserve a lump sum while creating a reliable monthly cash flow. In this article, we will specifically examine the characteristics of various products and the criteria for making the right choice for you.
=
Pension Insurance Enrollment Conditions and Selection Tips for a Stable Retirement
1. The Need for Pension Insurance Amidst Rising Medical Costs in Old Age
The factor that most significantly threatens household finances after retirement is undoubtedly the increase in medical costs and fixed living expenses. As people age, the frequency of hospital visits increases, and without prepared funds, one faces significant difficulties. It is a regrettable situation where retirement savings are completely depleted by hospital bills and insurance premiums. Therefore, one should consistently prepare pension insurance from a young age to defend against future medical and living costs simultaneously. There is a significant difference in the quality of life after retirement between simply saving and preparing a pension. A steady monthly cash flow is necessary to receive medical treatment with peace of mind and maintain a basic standard of living. I often see acquaintances who struggled after their income stopped post-retirement and later regretted not preparing sooner. If you do not prepare thoroughly now, you may suffer from unbearable economic pressure later. Therefore, you should actively consider enrolling in pension insurance as a shield against retirement bankruptcy.
Securing a stable cash flow through pension insurance is essential to defend against rising medical and living costs in old age.
2. Characteristics and Pros/Cons of Lump-Sum Payment Products
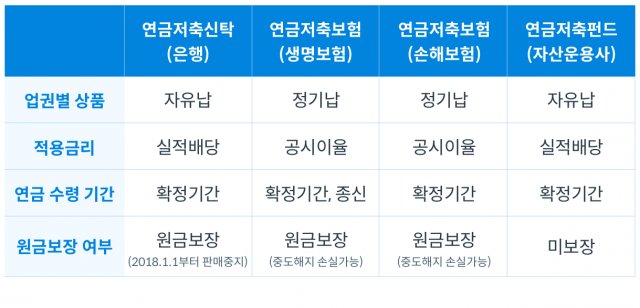
Interest is growing in lump-sum payment pension insurance products, which allow you to pay a large sum all at once when you have surplus funds. It is true that entrusting severance pay or inherited lump sums to private financial institutions often raises concerns about principal loss. In such cases, utilizing lump-sum products from the post office or commercial financial institutions can provide peace of mind regarding principal protection. A major advantage is that you can safely manage a lump sum and receive a stable pension after a certain period. However, lump-sum products have the drawback that liquidity may decrease because the funds are tied up at once. If a large sum of money is suddenly needed, it becomes a hassle to cancel the policy midway or take out a loan. Therefore, you should make the enrollment decision after carefully considering your total asset size and future cash flow plans. Rather than enrolling just because others say it is good, wisdom is needed to choose a payment method that fits your financial situation. You must establish a balanced asset allocation strategy that satisfies both safety and profitability.
While lump-sum pension insurance is good for safely managing a large sum, you should consider the potential for reduced liquidity in advance.
3. Differences Between Pension Savings Insurance and Pension Savings Funds
Many people seriously struggle with deciding which to choose between pension savings insurance and pension savings funds. Pension savings insurance has an insurance structure, making it very advantageous for maintaining the contract stably over the long term. However, if you cancel the contract midway, you may incur significant losses, so caution is required. On the other hand, pension savings funds have the advantage of allowing you to invest in various financial products yourself to pursue higher returns. For those with a conservative investment style who prefer stability, insurance-type products can be a much more reassuring choice. Conversely, those who want to actively manage returns by reading the trends of the stock and bond markets prefer fund products. I often see people around me who regret enrolling without clearly understanding the pros and cons of both products. To avoid regret, you must accurately diagnose your investment style and economic situation before choosing the appropriate product. You should always cultivate the habit of carefully reading product prospectuses before enrolling in any financial product.
Pension savings insurance is advantageous for stable long-term maintenance, while pension savings funds are suitable for pursuing active investment returns.
4. Checking Business Costs and Mid-Term Cancellation Risks
The hidden obstacle that must be most carefully examined when enrolling in a pension insurance product is the business cost and fee structure. Since a certain portion of the monthly premium is deducted as business costs, you must definitely verify the actual amount being accumulated. If you cancel the policy midway shortly after enrollment, you may experience the absurd situation of not even recovering your principal. Due to this structural characteristic, pension products are not structured for short-term profits but are a long-term race requiring maintenance for at least ten years. It is easy to find retirees who enrolled based solely on yield and later became disappointed due to high business costs. Before signing the contract, it is necessary to consult closely with an agent and carefully examine the surrender value table. You should also check if there are relief mechanisms such as payment suspension or reduction systems in case payments become difficult due to unforeseen circumstances. You are required to evaluate the possibility of long-term maintenance coldly, rather than being dazzled by immediate, flashy benefits. It is wise to set a reasonable monthly payment amount that you can maintain until the end, tailored to your income level.
To prevent high business costs and disadvantages upon mid-term cancellation, you must definitely check the surrender value and the possibility of long-term maintenance before enrollment.
5. Utilizing Tax Benefits and Tax-Exempt Requirements
Securing tax-saving benefits while preparing for retirement is a basic and core strategy in wealth management. Some pension insurance products offer tax-exempt benefits on interest income if certain conditions are met. Since the actual pension amount received after retirement increases by the amount of tax saved, the quality of life changes significantly. It is important to harmonize filling the tax deduction limit with utilizing tax-exempt products. In fact, many asset holders include tax-exempt pension products as an essential element of their portfolio to reduce tax burdens. Since relevant tax laws can change frequently, you must grasp the accurate benefit details that meet current standards in advance. You need to seek advice from experts or make an effort to continuously learn about financial information. Reducing invisible expenditures like taxes is one of the most certain ways to generate returns. You must analyze your annual income and consumption patterns to complete the most advantageous tax-saving pension structure.
Actively utilizing tax-exempt requirements and tax benefits can maximize the actual pension amount received.
6. Final Advice for Successful Retirement Planning
As we enter the era of super-aging, retirement preparation, which is no longer someone else’s story but our own reality, can no longer be postponed. To ensure that the efforts of your younger days are not in vain, you should open and analyze your insurance policies again starting now. It is most important to take the attitude of making concrete plans and implementing them one by one, rather than trembling with vague anxiety. As time passes, the range of choices narrows, so acting immediately is the wisest method. Please discuss life after retirement seriously with your family and calculate the necessary funds. It is also a good method to build a customized pension portfolio that perfectly fits your financial status with the help of an expert. Do not forget that small interests and practices accumulate to gift you a peaceful and leisurely retirement later. Let us check our pension status immediately through a nearby financial institution or a trustworthy channel starting today. I hope you will start the most certain and reliable investment for your future self right now.
You must escape from vague anxiety, check your pension status immediately, and implement concrete retirement planning.
Frequently Asked Questions
=