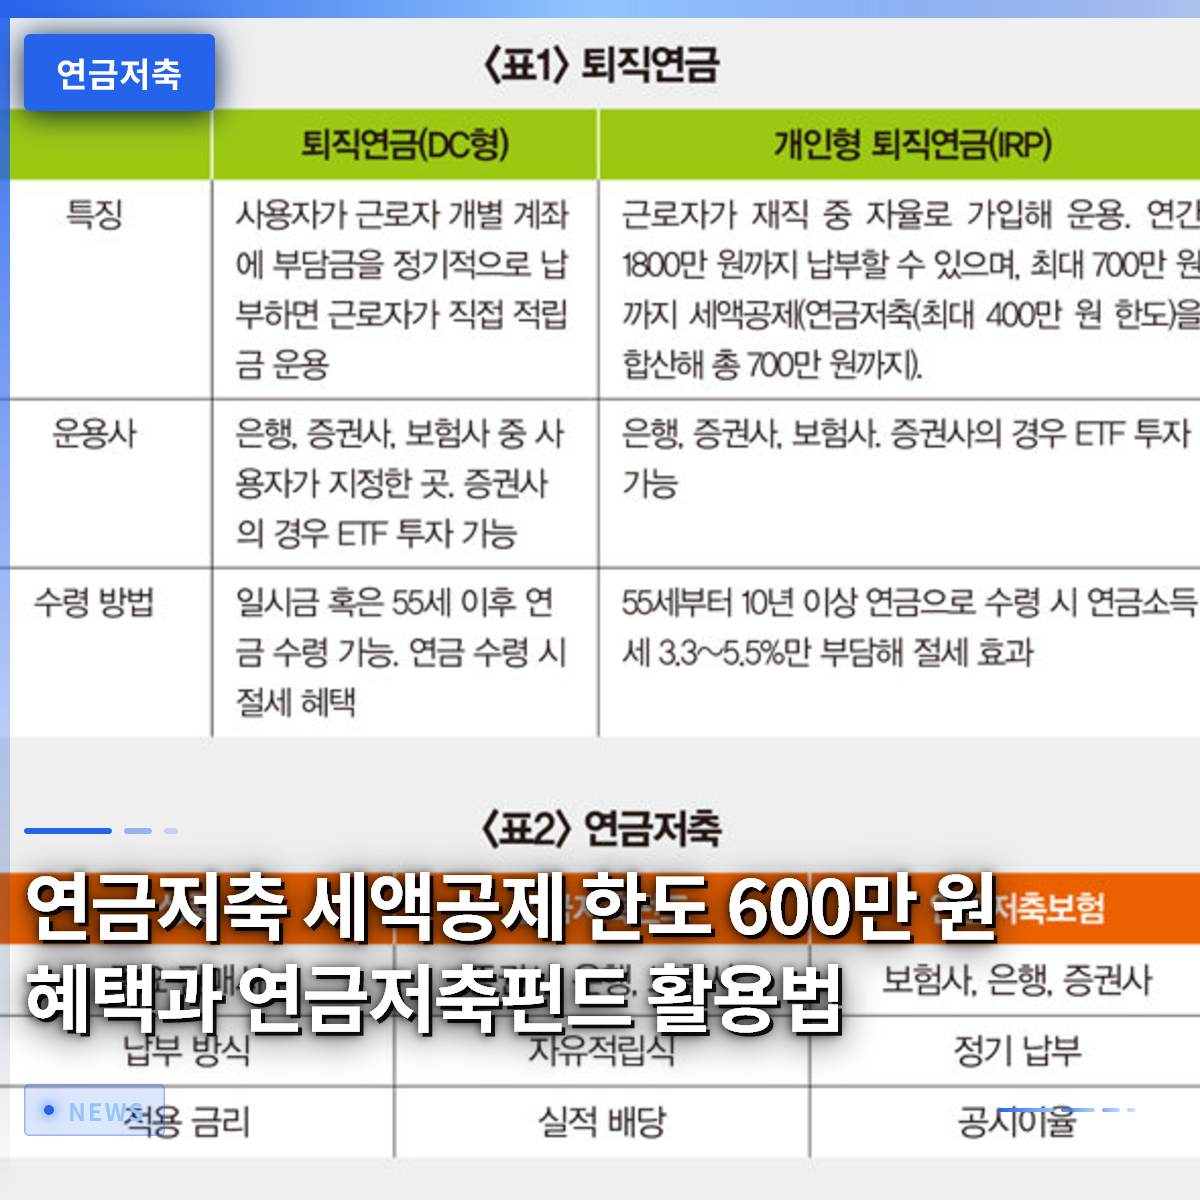
If you want to secure your retirement funds and save on taxes during your year-end settlement simultaneously, opening a pension savings fund account is undoubtedly the wise choice. Many office workers find themselves sighing in frustration every year when the year-end tax settlement season arrives, feeling hit by a “tax bomb.” It is truly frustrating when your colleagues get refunds of several hundred thousand won while you have to pay more in taxes. I, too, have bitter memories of missing out on tax benefits in the past, believing that savings accounts and deposits were the only best options. However, after opening a pension savings account on the advice of a senior colleague, I have seen a noticeable increase in my annual tax refunds. In this article, I will clearly explain the basic concepts of pension savings, the tax deduction limits, and how to invest in equity-based products.
=
The 6 Million Won Tax Deduction Limit for Pension Savings: Benefits and How to Use Pension Savings Funds
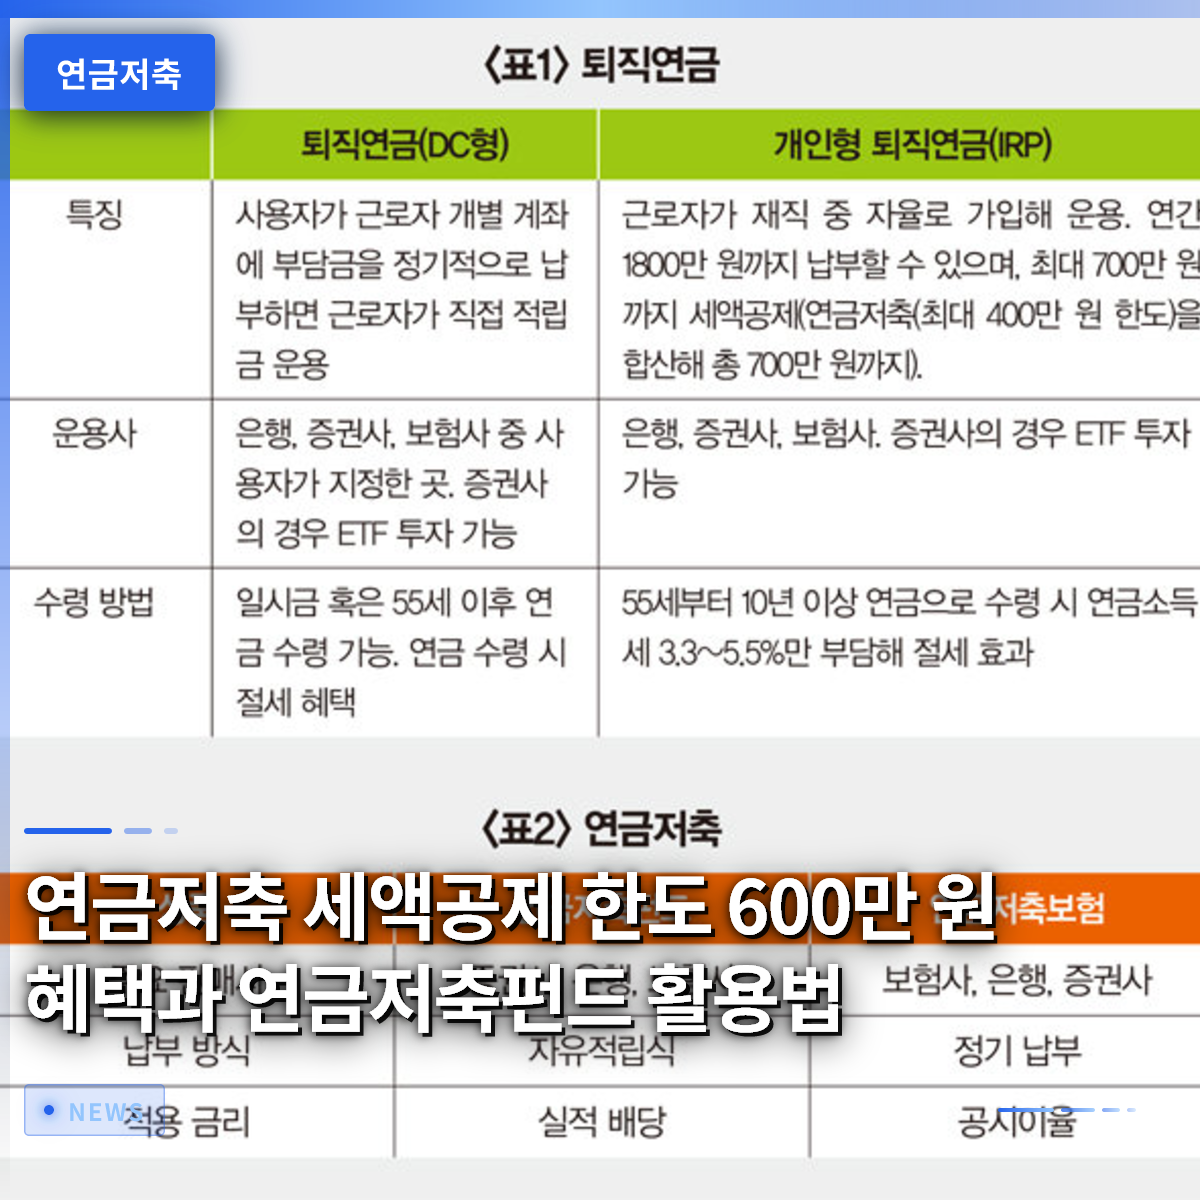
1. Concepts and Necessity of Pension Savings

Pension savings, as commonly referred to, is a highly valuable financial product that allows you to prepare for a stable retirement while also enjoying tax benefits. In the past, the older generation had access to many bank products with high interest rates, but today, with the continued low-interest-rate environment, it is difficult to even beat inflation with just deposits. In fact, media reports have highlighted how a veteran broadcaster has maintained a pension savings account opened in the 1990s and has benefited greatly from it. While interest rates were very high back then, we are now in an era where individuals must choose their own investment products to improve returns. Therefore, it is crucial to consistently contribute to a pension account from a young age to benefit from compound interest. Many people feel overwhelmed by the prospect of life after retirement, but the outcome varies drastically depending on when you start preparing. Even saving the cost of a cup of coffee each month to put into a pension account will eventually return as a solid pillar of support. When talking to friends, I often find that many worry about how they will survive in old age but take no actual action. However, those who start early by building a portfolio with monthly automatic contributions are the ones who ultimately win. From now on, I encourage you to accurately understand the necessity of pension savings and start contributing gradually, even with small amounts.
Pension savings is an essential financial product that simultaneously addresses retirement preparation and tax savings.
2. Complete Guide to Tax Deduction Limits
The first thing to check when opening a pension savings account is the annual tax deduction limit. Currently, according to the law, you can receive a tax deduction benefit of up to 6 million won if you contribute solely to a pension savings account. If you combine this with an IRP (Individual Retirement Pension) account, the limit increases to a maximum of 9 million won. Office workers with an annual salary of 55 million won or less can benefit from a high deduction rate of 16.5%, allowing them to receive a refund of up to 990,000 won. Even if your salary exceeds 55 million won, you can still receive a substantial refund with a 13.2% deduction rate. This is why many early-career professionals and office workers rush to deposit money into their pension accounts as the year-end approaches. It is also very useful to manage your account like a regular savings account and make additional contributions when the year-end settlement period approaches. However, to minimize the tax burden, the principal and investment returns that received tax deductions must be received as a pension after the age of 55. If you cancel the account midway due to unforeseen circumstances, you may have to return all the benefits received, so it is essential to keep in mind that this is for long-term maintenance. If you develop the habit of maxing out the 6 million won limit every year, you can achieve excellent financial results.
You can receive a tax deduction of up to 6 million won with pension savings alone, and up to 9 million won when combined with an IRP account.
3. Differences Between Pension Savings Funds and IRP

While various pension products exist in the market, choosing a pension savings fund is undoubtedly advantageous if you want to grow your assets. IRP accounts are subject to regulations on the mandatory ratio of safe assets, which places certain restrictions on holding equity assets. In contrast, pension savings funds opened at securities firms allow you to invest 100% in the equity-based Exchange-Traded Funds (ETFs) of your choice, without any separate safe asset restrictions. The younger generation should bet on the growth potential of the stock market to significantly grow their assets, making pension savings funds much more attractive. It is time to move away from the older generation’s approach of seeking only stable products like deposits and savings accounts and embrace active investing. Of course, you can make additional contributions through an IRP account for the remaining amount not covered by the pension savings fund, thereby maximizing your tax deduction limit. It is crucial to accurately understand the pros and cons of both accounts and allocate funds according to your investment style. If you want to take an aggressive approach with a higher stock allocation, you should first fill your pension savings fund and use the IRP when you have extra funds. This is why investment experts around you unanimously advise filling the pension savings fund first: it is due to this operational autonomy. Choose the right account for you to capture both high returns and tax savings.
Pension savings funds are advantageous for asset growth as they allow 100% investment in equity ETFs without safe asset restrictions.
4. Strategy for Transferring Matured ISA Funds to Pension Savings
Transferring matured funds from your Individual Savings Account (ISA), which has become an essential part of asset management, to a pension savings account can yield enormous additional benefits. When a tax-advantaged account matures, people often withdraw the lump sum for living expenses or transfer it to a regular stock account. However, if you transfer the matured funds to a pension savings account, you can receive an additional tax deduction equivalent to 10% of the transferred amount. For example, if you transfer a lump sum to a pension account, you can secure additional deduction benefits within a limit of 3 million won. This is a powerful tax-saving bonus created by the government to encourage stable retirement fund formation. One of my acquaintances left the lump sum from a matured account in their regular account and was surprised to learn about this system later, immediately transferring the funds. By putting the lump sum into a pension account at once, you can also secure additional tax deduction limits, achieving a two-for-one effect. However, since this money must be received as a pension in the distant future, you should decide carefully if you plan to use it for immediate living expenses. If you have surplus funds that you do not need immediately, transferring them to a pension account is much more tax-efficient than leaving them in a regular account. Smart investors actively utilize this inter-account transfer system to thoroughly block unnecessary taxes.
Transferring funds from a matured account to pension savings allows you to receive additional tax deduction benefits, making it highly advantageous.
5. Tips for Managing a Monthly Accumulation Portfolio
If you have opened a pension savings fund, you should practice accumulation investment by consistently contributing a fixed amount each month rather than putting in a large sum at once. The stock market is always volatile, so if you buy all at once and encounter a market downturn, you will inevitably be shaken psychologically. On the other hand, by consistently buying equity-based ETFs on a set date each month, you benefit from a lower average purchase price. A natural defense system operates where you buy less when the market is good and buy more units when the market crashes. This is why office workers set up automatic transfers every time they receive their salary and do not worry about it. When building a portfolio, it is safer to mix products that diversify investments not only in the domestic market but also in global high-quality indices. By appropriately combining ETFs that invest in US large-cap tech stocks or global indices, you can expect excellent long-term performance. Do not be swayed by rumors about which stocks have hit the jackpot; the secret to success is to steadily accumulate high-quality indices. I, too, invest peacefully by automatically transferring funds on my payday and occasionally checking my account. If you abandon impatience and view the market with a long-term perspective of ten years or more, you will eventually discover your grown assets.
Accumulation investment, where you automatically transfer funds monthly to high-quality ETFs, is beneficial for both psychological stability and returns.
6. Pension Receipt Timing and Precautions
To minimize the tax burden on your diligently accumulated pension savings assets, you must receive them in the form of a pension after the age of 55. If you withdraw the lump sum all at once upon reaching the pension receipt age, miscellaneous income tax will be imposed, potentially nullifying the benefits you have enjoyed. The government encourages receiving pensions in installments to ensure a stable retirement life, so it is advisable to set a long receipt period. If the annual pension receipt amount exceeds a certain threshold, it may become subject to comprehensive income tax, so you need the wisdom to adjust the receipt amount. Referring to the advice of tax experts and designing your post-retirement cash flow in advance is the completion of wise retirement preparation. Financial companies are also reflecting these customer needs by offering various pension enrollment events and customized services. You can easily open an account and apply for events through a securities firm’s app, potentially receiving gift certificates or investment support funds. Now is the time to stop treating this as someone else’s story, turn on your smartphone, and find the securities firm that is most advantageous for you. Small interests and actions will accumulate to become the most powerful weapon determining the abundance of your retirement. The time you think it is too late is actually the earliest time, so check your pension savings account and prepare for your future right now.
You must receive the funds as a pension in installments after age 55 to avoid a tax bomb and enjoy maximum tax savings.
Frequently Asked Questions
=