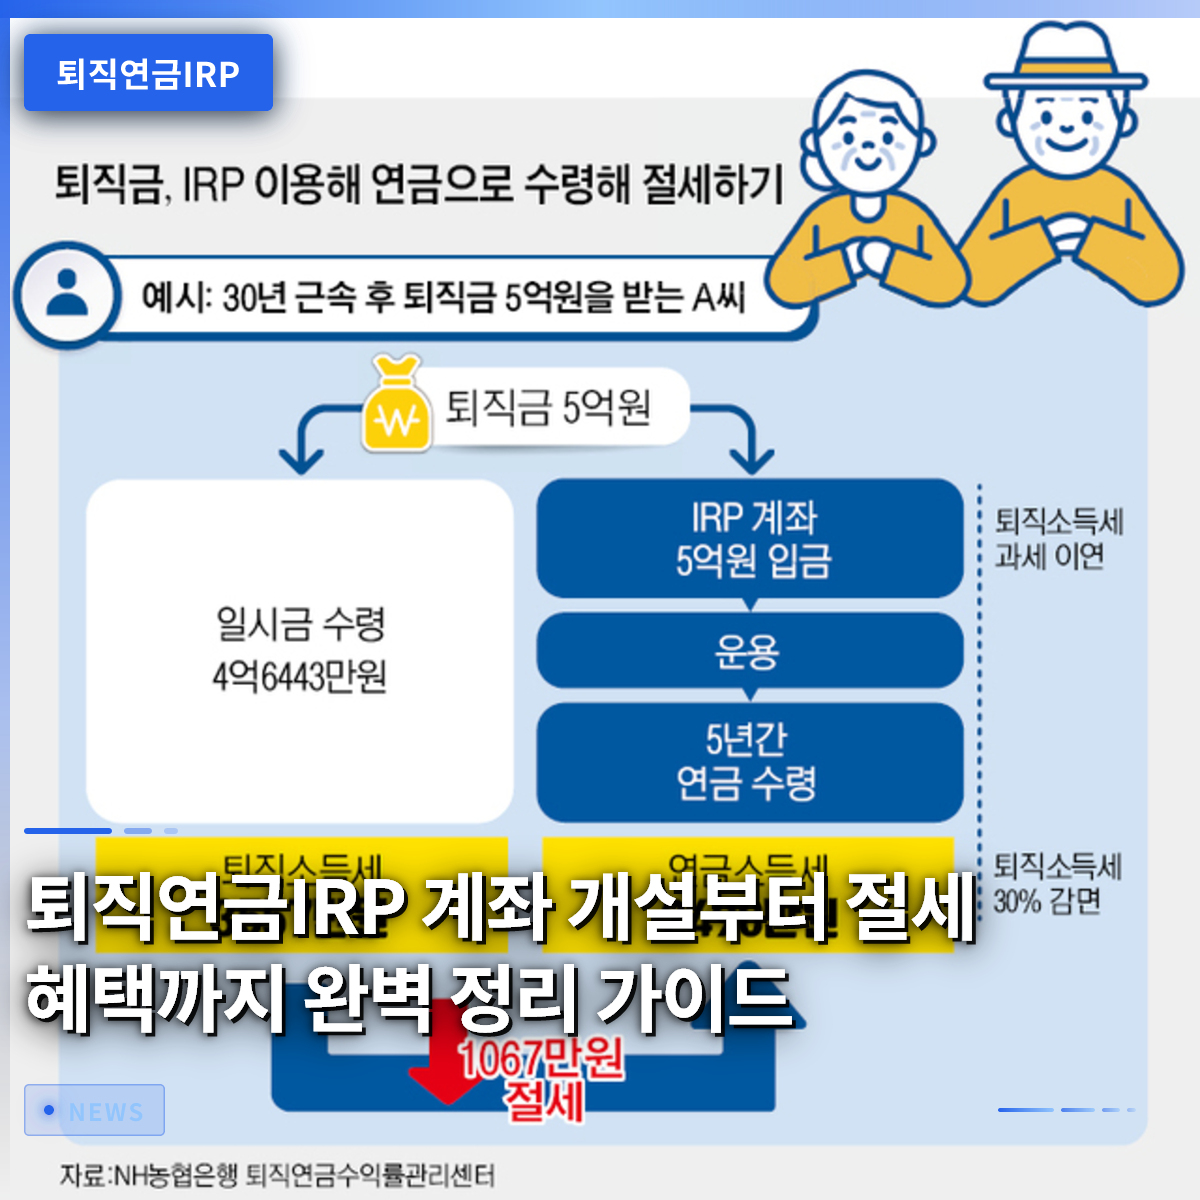
The Individual Retirement Pension (IRP) account is an essential financial product that offers both retirement preparation and tax benefits to both employees and self-employed individuals. Last year, Mr. Kim, an office worker, nearly faced a massive tax bill when reviewing his year-end tax settlement documents. However, thanks to the account he hastily opened, he was able to enjoy the joy of receiving a tax refund of several hundred thousand won. While many people join these accounts to grow their retirement assets, they often leave them untouched because they do not fully understand the specific management methods or the system. In this article, we will thoroughly examine everything from how to manage the account efficiently to key points to note when changing jobs or retiring. If you understand and utilize this system properly, your life after retirement will be much more secure. Let us now look at the key elements for wise asset formation, one by one.
=
The Ultimate Guide to IRP Retirement Pension Accounts: From Account Opening to Tax Benefits
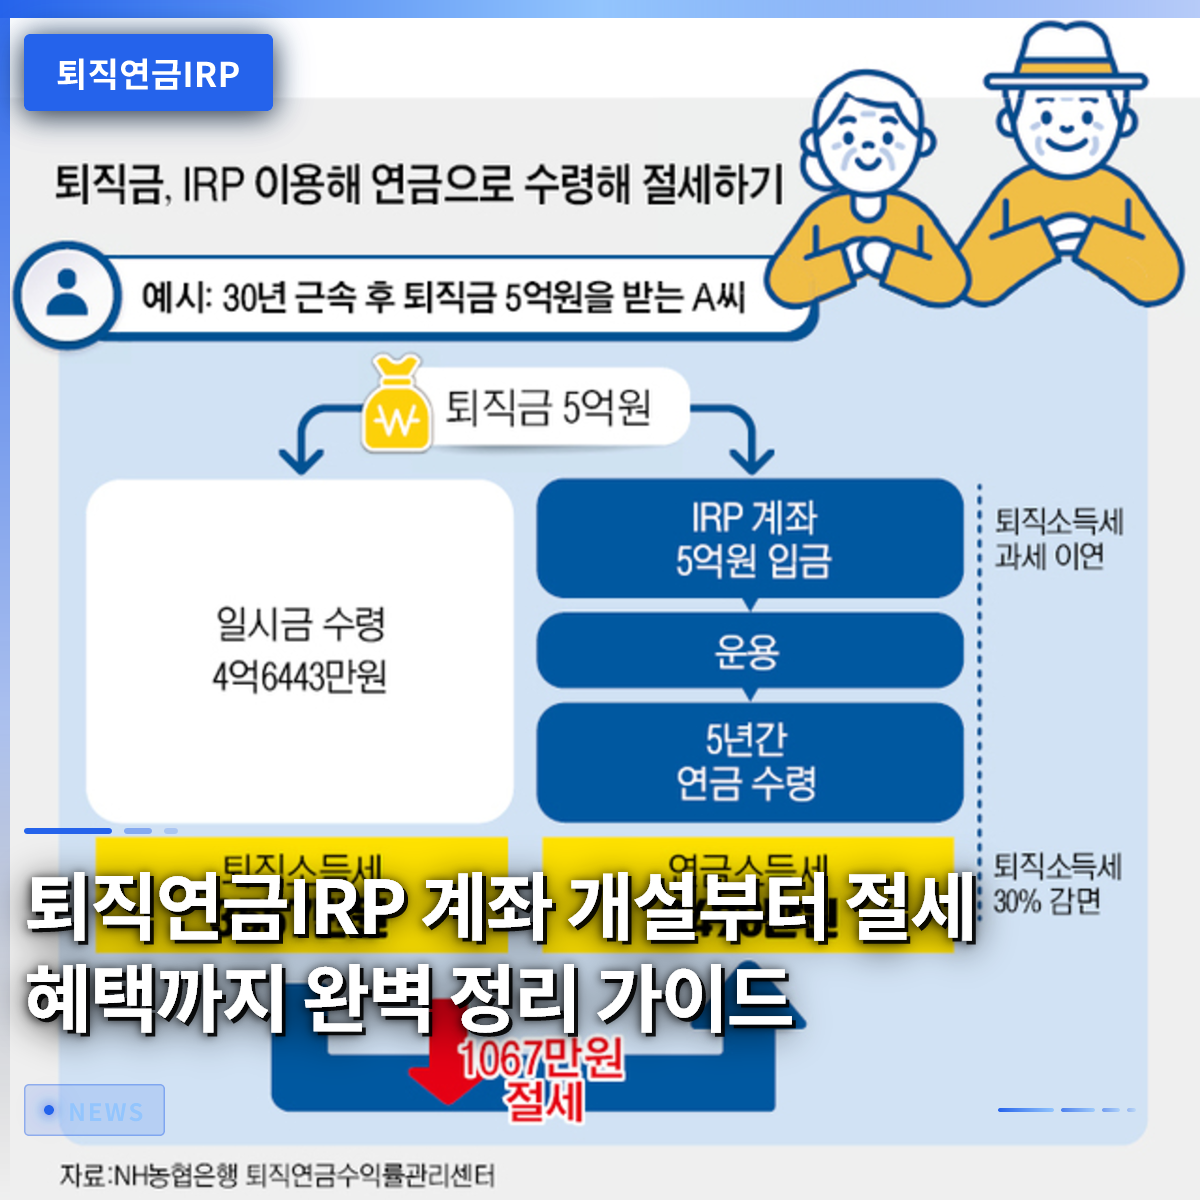
1. What is an IRP Retirement Pension Account and Who Can Join?

The Individual Retirement Pension (IRP) has established itself as a flexible system that allows not only employees but all economically active individuals with income to participate. In the past, it was primarily used to receive severance pay when changing jobs or retiring. However, the number of people voluntarily making additional contributions has exploded. The barrier to entry has lowered, allowing even self-employed individuals and freelancers, who previously found it difficult to benefit from Defined Benefit (DB) or Defined Contribution (DC) plans, to utilize this system. It is highly accessible, as accounts can be easily opened through the mobile apps or branches of financial institutions such as banks and securities firms. It is perfectly structured for growing long-term lump sums by adding spare funds while employed. The number of people choosing this account as the first step toward a stable life after retirement is increasing rapidly every year. In fact, if you look around, the first place employees look to safely transfer their severance pay when preparing to change jobs is this account. If you mistakenly withdraw the money received upon resignation into another account and spend it, the lump sum can disappear in an instant. However, if you keep it in this account, you can defer taxes while continuing to grow your assets. Mr. Park, who runs a self-employed business, deposits a fixed amount into this account every month, steadily building a safety net for his business income. In this way, it serves as a reliable fence for those who want to prepare for their retirement regardless of their income type. The enrollment process has also become so simple that it can be completed with just a few taps on a smartphone screen with only an ID card. It has gained great popularity among busy modern people because they no longer need to visit a branch with complex documents.
The IRP Retirement Pension Account, which anyone with income can easily join, is a core tool for managing retirement assets and preserving severance pay.
2. Complete Analysis of Year-End Tax Settlement Tax Credits and Limits

During the year-end tax settlement, the biggest concern for office workers every winter, this account is undoubtedly considered the best tax-saving helper. This is because a certain percentage of the contributed amount is directly deducted from the tax amount, resulting in a very tangible benefit. There is a maximum limit on annual contributions, and the deduction rate varies slightly depending on your income level and age. Simply developing the habit of saving can significantly reduce your tax burden, offering a two-for-one effect. Last year, Mr. Choi, an employee who filled the maximum limit through this system, received a refund much larger than expected, earning the envy of those around him. It is an essential item to manage from a tax planning perspective, going beyond simply saving money. Specifically, tax credit benefits are provided up to a certain limit of the annual contribution, so the higher the income, the larger the refund amount. Since the limit is applied in combination with pension savings products, harmoniously managing both products is the key to tax savings. For example, employees with income below a certain threshold can apply a higher deduction rate to maximize their actual rate of return. Setting up automatic transfers from your monthly salary to withdraw a fixed amount also has the added benefit of forcing you to save, which is easy to overlook. Thanks to this structure that saves on taxes while growing retirement assets, it has become an essential financial product for office workers. It is much more advantageous to make consistent split contributions from the beginning of the year rather than rushing to prepare when the year-end approaches.
To enjoy the maximum tax credit effect during the annual year-end tax settlement, it is important to make consistent contributions up to the limit.
3. Harmonious Management of Principal and Interest Guaranteed Products and Performance-Based Products

A variety of management products are available to satisfy both those who want to protect their assets safely and those seeking high returns. Principal and interest guaranteed products, such as deposits and savings accounts, are popular among conservative investors because there is no risk of losing the principal, even if interest rates are low. On the other hand, performance-based products, such as equity or bond funds and Exchange-Traded Funds (ETFs), carry risks but offer the potential for long-term returns that exceed inflation rates. There is a limit on the amount that can be invested in risky assets out of the total accumulated funds, providing a safety mechanism to prevent indiscriminate losses. Mr. Jeong, an employee, was able to sleep soundly even when the market was volatile because he constructed a portfolio by appropriately mixing safe and risky assets. The scale of funds you hold at retirement can vary dramatically depending on how you adjust the proportions according to the nature of the assets. You can check at a glance via graphs in financial institution mobile apps where and how much of your assets are currently invested. Wisdom is needed to increase the proportion of safe assets when the stock market feels overheated, and to look toward promising products in the opposite case. Recently, there is a growing trend of investors including U.S. value stocks or various dividend-oriented products to defer taxes while enjoying compound interest effects. You can manage your account stably even in a busy daily life by referring to expert advice or utilizing automatic rebalancing features.
You must adjust the ratio of safe assets and performance-based products according to your investment style to increase long-term returns.
4. Tips for In-Kind Transfer and Management of Retirement Pensions When Changing Jobs or Resigning
Many people are at a loss for how to handle their accumulated severance pay when changing jobs or retiring. In the past, it was cumbersome because all existing products had to be converted to cash upon resignation. However, recently, a system allowing the transfer of existing products to accounts at other financial institutions without a complex selling process has become active. This allows you to save on unnecessary trading fees and transfer your assets while maintaining the desired products, even when market conditions are favorable. This is an essential feature for modern employees who change jobs frequently and serves as a reliable shield protecting the continuity of assets. In fact, just a few years ago, many employees were upset because their portfolios were forcibly dismantled every time they quit their jobs. Now that the in-kind transfer system has been established, you can choose a securities firm or bank you like, much like choosing a house to move into, and transfer your assets as they are. However, there are still regulations requiring transfers between pension savings accounts and this account to go through cash form, so you should check the specific conditions in advance. You must continue to manage the account consistently after retirement to avoid a tax bomb and fully enjoy the benefits of low-rate taxation when receiving your pension. It is necessary to develop the habit of carefully checking to ensure your valuable retirement assets remain stable even amidst the major life change of resignation.
Utilizing the in-kind transfer system when resigning or changing jobs allows you to easily move your assets to your desired financial institution without unnecessary losses.
5. Tax Knowledge You Need to Know About Early Withdrawal and Pension Receipt
Many people wonder if they can withdraw funds from this account when they urgently need a large amount of money, but in principle, it is not easy. Early withdrawal is only permitted in very exceptional legal circumstances, such as purchasing a house, bankruptcy, or rehabilitation proceedings, so caution is required. If you forcibly withdraw money, you not only have to return the tax credit benefits you have received so far, but you may also be subject to miscellaneous income tax, leading to a difficult situation. Therefore, it is wise to think of this account as completely separate from your emergency fund rather than easily canceling or withdrawing it just because you need a lump sum. You must not forget that the lowest tax rate is applied when you receive it in the form of a pension gradually upon reaching retirement age. At the stage of receiving the pension as monthly living expenses in old age, a low-rate taxation is applied, which is much lower than ordinary income tax. If you receive it as a lump sum, you must pay taxes at a high rate, but if you receive it in annual installments, you can significantly reduce the tax burden. To make life after retirement abundant, it is advantageous to accurately understand this tax structure and extend the receipt period. If you have unavoidable expenditure plans, such as a child’s marriage or medical expenses, it is best to consult with a tax expert in advance to find the most favorable option. Rather than being swayed by immediate temptations and breaking the account, you should maintain it until the end to serve as a sturdy pillar for your retirement.
Early withdrawal is only possible under strict circumstances, and you must receive it as a pension over a long period after retirement to minimize the tax burden.
6. Practical Strategies for Successful Retirement Preparation
Based on the content reviewed so far, you should check the status of your IRP Retirement Pension Account today and prepare for the future. Retirement is not a story of the distant future but a reality that everyone will face, so you must plant seeds steadily from a young age. Not forgetting to manage the automatic transfer amount going into your pension account amidst fixed monthly expenses is the shortcut to becoming wealthy. Instead of being swayed by rumors and repeating frequent trades, you need an attitude of steadily accumulating centered on reliable, high-quality assets. Even if the financial environment and systems continue to change, you have nothing to fear if you establish your own firm criteria for asset management. The small action of turning on your smartphone now to check your account balance and management products will be the key to determining an abundant old age. In fact, people who consistently check their accounts and review their portfolios every year often find themselves smiling at the point of retirement. The magic of compound interest grows with time, so the person who starts one day earlier is bound to be the winner in the end. There is no need to be anxious about stories of colleagues making big money through private equity funds or short-term investments. This is because this ordinary path of saving taxes and safely growing assets is the most certain and robust strategy for retirement preparation. It is also a good method to gather with family during upcoming holidays or year-end to check each other’s retirement financial lives. I sincerely hope that reading this article today will be the occasion for a miracle of tax savings and growth to occur in your account.
Checking your account today and practicing consistent accumulation and long-term investment is the only way to complete a successful retirement.
Frequently Asked Questions
=