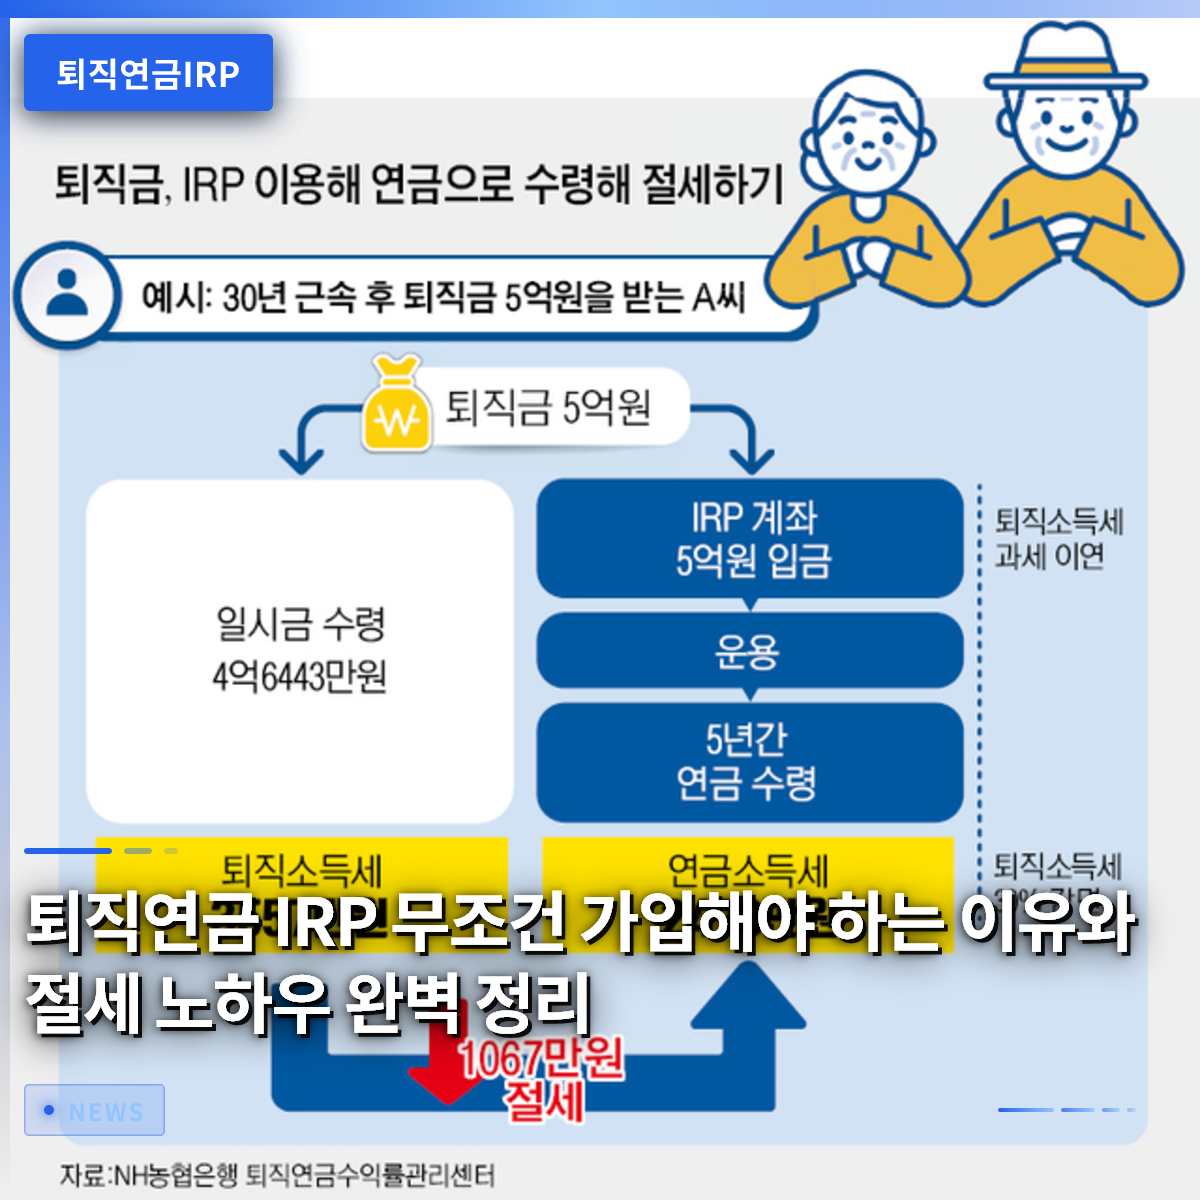
Did you know that you must route your severance pay through an Individual Retirement Pension (IRP) account to avoid a tax bomb and protect your assets? Many people who are changing jobs or approaching retirement make the mistake of receiving their severance pay directly into a regular bank account, resulting in unnecessary tax payments. In this article, we will examine the basics of the IRP, including tax deduction benefits, how to invest in safe assets, and precautions to take when terminating the account early. You will likely be amazed at why the IRP is essential after hearing stories from people who paid millions of won in taxes because they received their severance pay in a regular account. Let’s break down the IRP utilization strategies that smart professionals never miss. Preparing tax-saving know-how ahead of others is the shortcut to a comfortable retirement.
=
Why You Must Enroll in an IRP and the Ultimate Guide to Tax-Saving Strategies
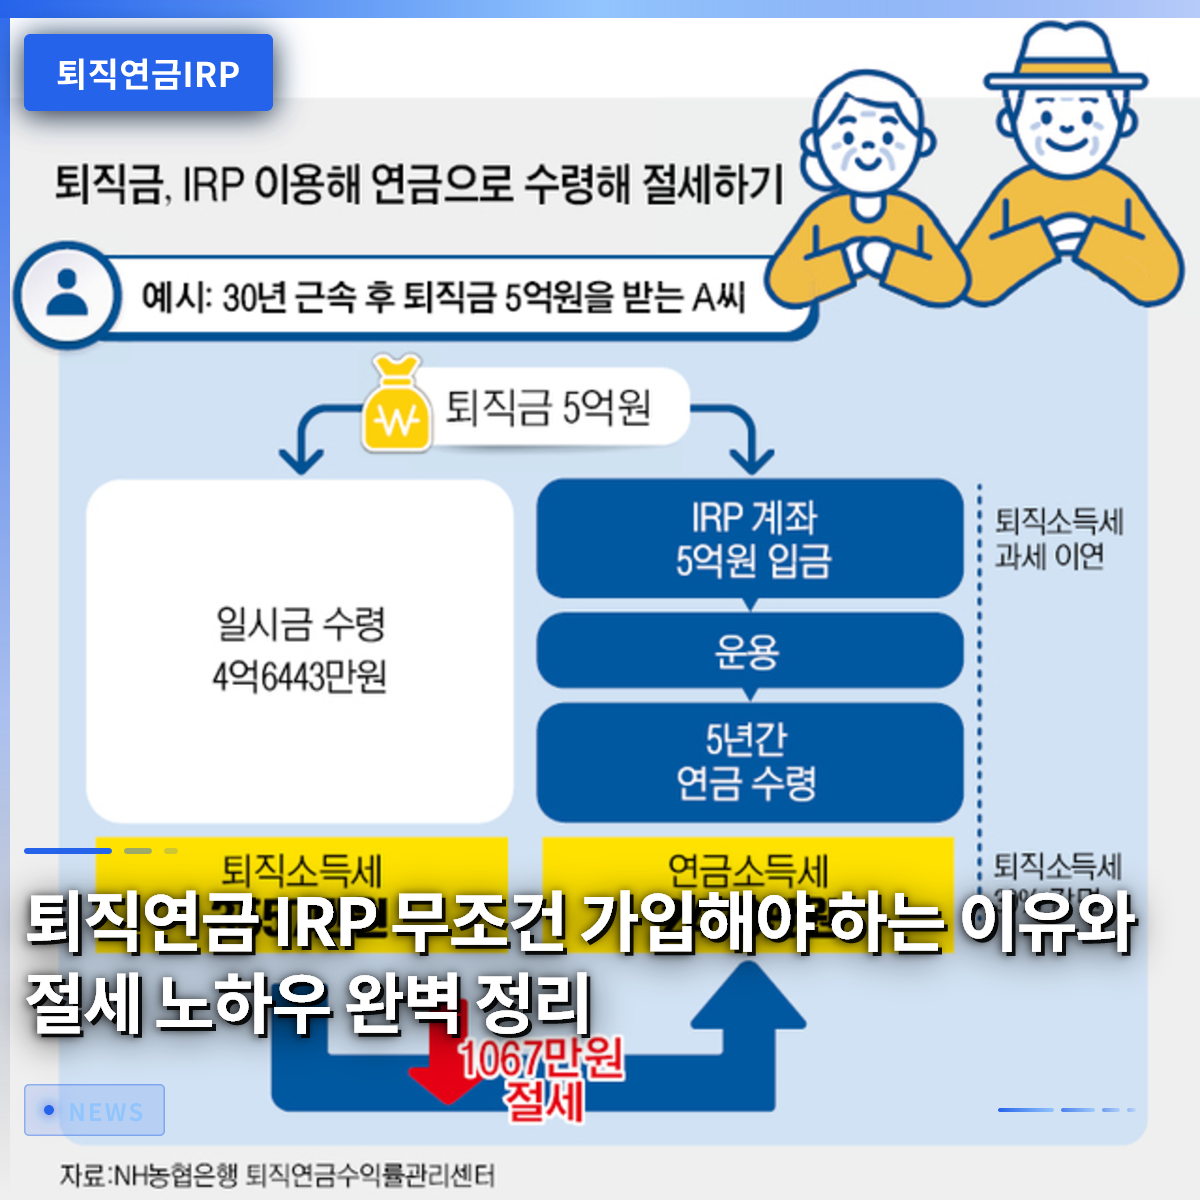
1. What is an IRP (Individual Retirement Pension)?

The Individual Retirement Pension (IRP) is a comprehensive asset management account where employees can consolidate and manage severance pay received upon changing jobs or retiring, as well as funds they contribute directly. In the past, when people quit their jobs, their severance pay would go directly into a bank account, often leading to it being easily spent on living expenses or poor asset management. However, since the system changed, severance pay must be transferred to an IRP account to ensure it is safely stored and grown until retirement. By utilizing this system effectively, your severance pay will accumulate in a single account without being scattered, even if you change jobs multiple times. Additionally, you can receive significant tax deduction benefits on your annual personal contributions during the year-end tax settlement, making the IRP an essential financial product for employees. This account is the most reliable starting point for reducing taxes and growing assets while preparing for retirement.
Mr. Kim, an employee, wanted to receive his severance pay in a regular account when he changed jobs last year, but he transferred it to an IRP on the advice of a staff member. Initially, he felt frustrated that his funds were locked away, but his perspective changed completely when he saw his tax refund during the year-end settlement and his assets growing. Like this, the IRP serves not just as a savings account but as a sturdy shield protecting your post-retirement life. If you manage it consistently from a young age, you can enjoy the magical effect of compound interest later on.
The IRP is an essential retirement preparation account that consolidates severance pay for management and saves on taxes.
2. The Decisive Reason to Receive Severance Pay via IRP

The biggest reason to choose an IRP account over a regular account when receiving severance pay is the tax deferral benefit. Normally, you must pay severance income tax immediately upon retirement, but if you transfer it to an IRP, the tax payment is deferred until you withdraw the money. Because the tax is not deducted immediately, a larger principal remains in the account, allowing it to grow like a snowball through the power of compound interest. This means you can enjoy additional returns that would have been impossible if you had invested only the remaining amount after paying taxes upfront. If you receive the transferred severance pay in the form of a pension after age 55, you can receive a reduction of more than 30% of the severance income tax you would have originally paid. This is the only way to significantly lower the tax burden while increasing the scale of your retirement funds.
Hearing stories from senior colleagues, many regret receiving their severance pay as a lump sum and spending it on buying a new car or their children’s wedding costs. However, keeping it in an IRP creates a forced savings effect, allowing you to protect your retirement funds intact. On top of that, you can enjoy the bonus of tax reduction benefits, achieving a two-for-one effect. As you approach retirement, this difference in tax savings can lead to a massive gap in assets. Therefore, it is best to establish the principle of always receiving severance pay into an IRP when leaving a company.
Receiving severance pay via IRP allows you to enjoy both tax deferral benefits and tax reductions simultaneously.
3. Strategy to Maximize Year-End Tax Deductions

The IRP allows you to maximize year-end tax deduction benefits by contributing funds directly, in addition to the severance pay provided by your company. Combined with pension savings products, you can receive a high-rate tax refund on contributions up to a maximum of 9 million won per year. For early-career professionals or the youth, the tax deduction rate is often higher, making it advantageous to enroll early in their working lives. Even if you just set up automatic monthly transfers, you can enjoy the joy of receiving a refund ranging from several hundred thousand to over one million won during the year-end settlement season. Reinvesting this refunded amount accelerates the growth of your assets. How well you utilize pension accounts, a basic formula for tax planning, determines the actual income of an employee.
Mr. Park, an employee who used to sigh over the “year-end tax bomb” every December, received a substantial refund last year after filling his IRP contribution limit. Seeing his colleagues envy him, he regretted not knowing this financial information sooner. Simply diverting a portion of the money you would have put into a savings account into this IRP can yield returns and tax-saving effects far higher than bank interest. Just as “a little makes a lot,” the tax deduction benefits accumulated each year return as enormous assets at the time of retirement. This is why you should check your bank balance right now and make a plan to fill the remaining limit.
You can receive tax deductions on contributions up to a maximum of 9 million won per year when combined with pension savings and IRP.
4. Investment Methods in Safe Assets and Various Products
Opening an IRP account does not mean leaving your money idle; you can invest in various financial products such as stocks, bonds, and funds. However, to protect retirement funds safely, regulations require that a certain percentage of the total accumulated amount must be invested in safe assets. Recently, bond-mixed products with safe asset characteristics that track US indices and various index-linked products have become popular. Additionally, since this year, individual investor government bonds can also be purchased through IRP accounts, significantly broadening investment options. By allocating equity products and safe assets appropriately according to your own investment style, you can achieve returns that beat inflation in the long term. Many investors also enjoy the process of checking market conditions monthly and readjusting their portfolios.
For young employees with decades left until retirement, it is advantageous to maintain an appropriate ratio of risky assets rather than sticking strictly to safe assets. Leveraging the characteristics of long-term systematic investing, a strategy of accumulating more units during stock price declines can lead to significant returns later. If you lack financial knowledge, choosing life-cycle fund products structured by experts is also a wise method. As you get closer to retirement, you should adjust your strategy to gradually increase the proportion of safe assets to protect your wealth. This flexible asset allocation ability is the core key that determines the prosperity of your retirement.
You can pursue long-term investment returns by combining various products and safe assets within the IRP.
5. Risks of Early Withdrawal Before Age 55 and Exceptional Regulations
Since the IRP is a system created for retirement funds, it is generally difficult to withdraw money early before the age of 55. If you terminate the account easily because you urgently need money, you will have to return all the tax deduction benefits you received and will also be subject to miscellaneous income tax. Many employees want to withdraw money midway for reasons such as buying a house or securing a deposit for a rental, but they often regret it after facing a tax bomb. Therefore, it is safest to manage the money in your IRP account as surplus funds that you truly do not need to use until retirement. If you are in a situation where you must withdraw money, carefully check whether it falls under the exceptional early withdrawal reasons stipulated by law rather than simply terminating the account.
In special circumstances, such as purchasing a house as a non-homeowner or treating a disease requiring long-term care, there are ways to reduce penalties or withdraw funds exceptionally. However, these exceptional regulations are strict, so it is beneficial to maintain the account without breaking it. Mr. Lee, who terminated his IRP because he needed urgent cash, was shocked after receiving a tax notice and having to return his tax deductions. You must be careful not to make the foolish choice of sacrificing future benefits for immediate convenience. You need the perseverance to protect the account to the end, viewing it as a sturdy piggy bank for your retirement.
Early termination before age 55 incurs significant tax penalties, so the account should be maintained unless it falls under exceptional reasons.
6. Final Advice for Successful Retirement Preparation
The IRP is not just an account to receive money from your company, but a powerful weapon that determines your economic freedom in the remaining years of your life. It is important to have the habit of paying attention to changing tax reform proposals and financial market trends, and periodically checking your account. This is because retirement is the fruit of a process prepared step by step from a young age, not something that arrives suddenly. Start by opening your smartphone app right now to check your IRP account’s return rate and contribution limit. Small interest and actions can completely change the quality of your life in retirement. I sincerely hope that all employees in South Korea can face their second life with confidence, without worrying about their post-retirement life.
Start the financial study you have been putting off today, and set up automatic monthly transfers to your pension account. As time passes, you will be grateful for reading this article as you see your assets grow and your taxes decrease. Your appearance 10 or 20 years from now is determined by the choices and actions you make today. If you proceed steadily with unwavering principles, anyone can enjoy a comfortable retirement life that others envy. I encourage you to take action now by opening your securities app and checking your IRP account.
Consistent interest and practice in managing your IRP account is the shortcut to a successful retirement.
Frequently Asked Questions
=