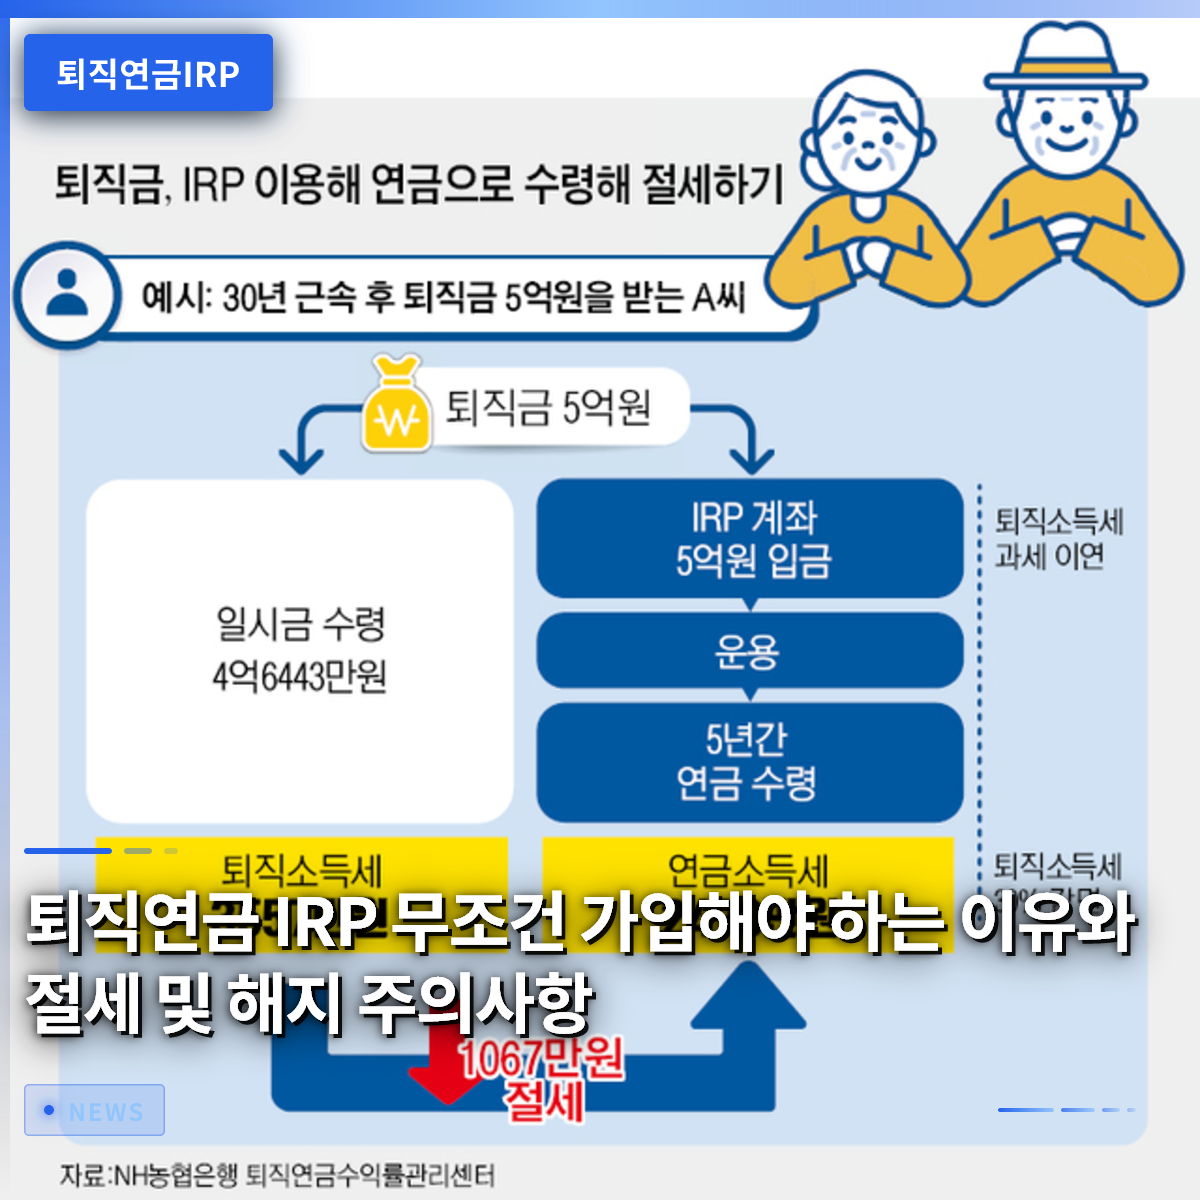
To save on taxes and protect your valuable retirement assets, you must use an Individual Retirement Pension (IRP) account when receiving your severance pay. Many people who are changing jobs or approaching retirement prefer to receive their severance pay in cash for easy access, but this can result in a massive tax burden. In recent years, while the amount transferred to IRPs has been enormous, the cancellation rate is also high, which is regrettable. This article will carefully examine the basic concepts of the retirement pension IRP, tax benefits, and effective asset management methods. If you need a lump sum of money immediately and cancel your account without proper consideration, you may suffer unexpected losses. Therefore, it is crucial to understand the system accurately and respond wisely. Let’s explore step by step how to utilize the retirement pension IRP to maximize your assets.
=
Why You Must Join an IRP for Your Retirement Pension: Tax Savings and Cancellation Precautions
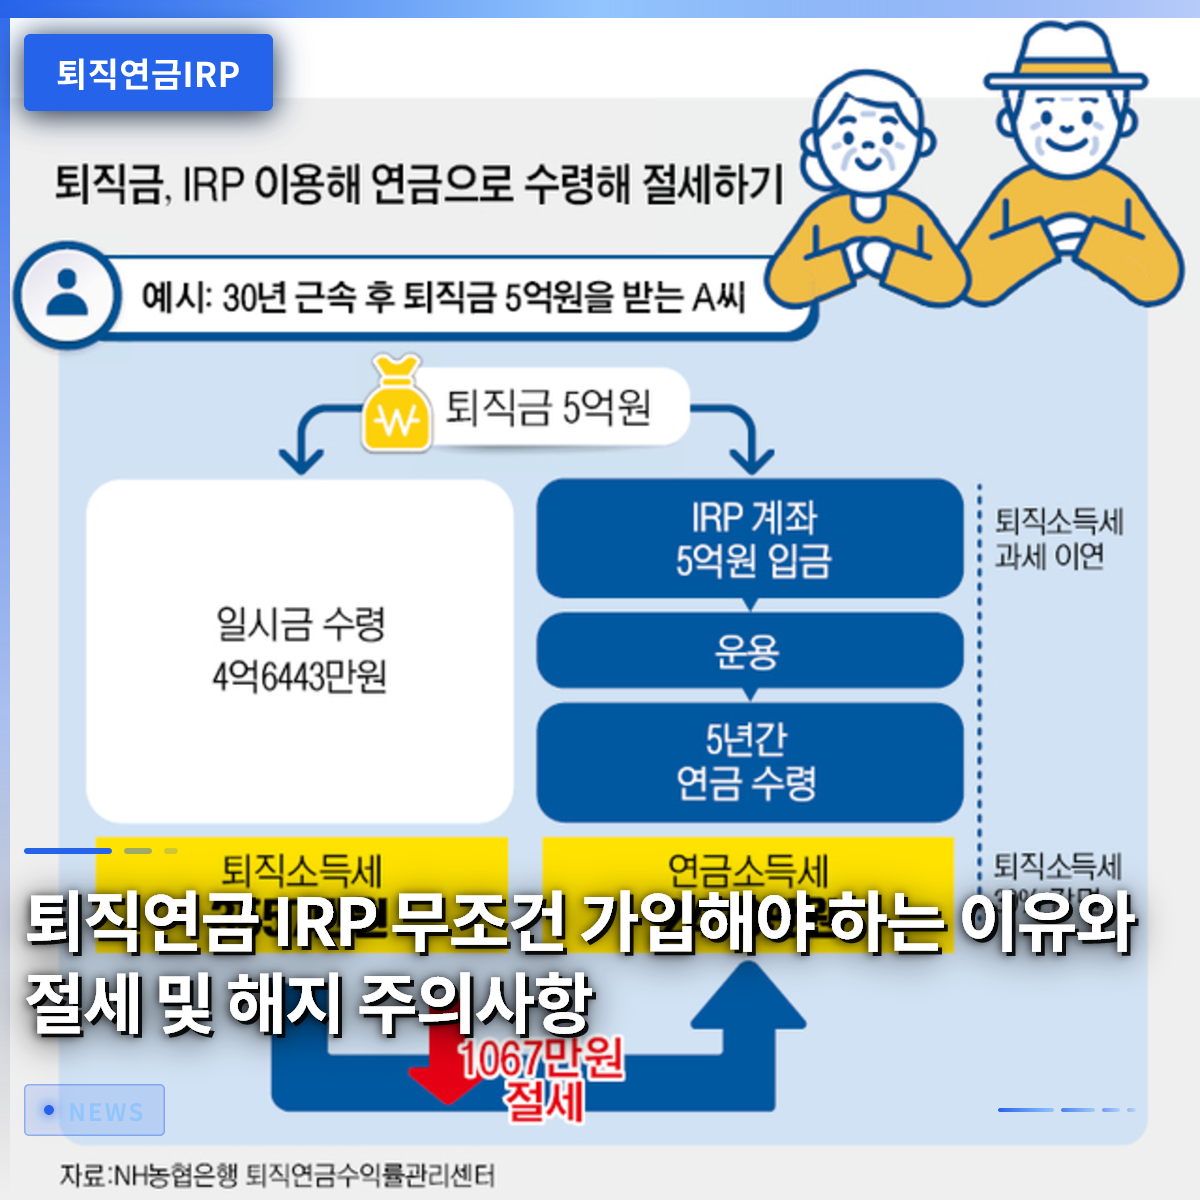
1. What is a Retirement Pension IRP?

The Individual Retirement Pension system is an account that allows workers to pool the severance pay they receive upon changing jobs or retiring, along with funds they contribute themselves, and manage them directly. In the past, when people quit their jobs, their severance pay would go directly into their bank accounts, often getting scattered on living expenses or entertainment. However, through this system, funds can be safely accumulated and received as a pension or a lump sum after the age of 55. Any employee can join, and it is also possible to prepare for retirement by making additional voluntary contributions. By putting in a small amount of surplus funds each month, you can also enjoy tax deduction benefits, making it an essential financial product for employees. In an era where you must manage your retirement funds yourself, this account is not an option but an essential asset management tool.
Since your severance pay accumulates in a single account every time you change jobs, managing your funds becomes much easier. Being able to see all your scattered money at a glance also helps prevent unnecessary spending. For example, Mr. Kim, an employee, used to spend all the severance pay he received when changing jobs in the past, but this time he is keeping it intact in his account and managing it. This way, keeping funds “locked away” from immediate view makes it possible to prepare for retirement from a long-term perspective. The government also actively encourages this system to help citizens achieve a stable retirement life.
The Retirement Pension IRP is an essential account for consolidating scattered severance pay to prepare for retirement and managing assets integrally.
2. Why You Should Receive Your Severance Pay via IRP

The biggest reason to choose this account instead of a regular bank account when receiving severance pay is that you can save on taxes. If you transfer the severance pay paid by your company according to the law into an Individual Retirement Pension account, no tax is deducted immediately, and taxation is deferred. In other words, since tax payment is postponed until you receive it as a pension after the age of 55, you can enjoy the compounding effect where your principal grows over time. If you bypass this process and receive the money in cash immediately, you will be subject to high severance income tax withheld at the source. In reality, many employees do not know this fact, spend the money, and later regret it after facing a tax bomb.
In addition to the tax deferral benefit, the tax rate applied when receiving the pension after retirement is also significantly lower. Receiving the funds in monthly pension installments rather than as a single lump sum can reduce taxes by up to 70%. Mr. Lee, an employee, receives his living expenses as a monthly pension after retirement and pays much less tax than if he were paying regular income tax. Reducing the tax burden while receiving retirement funds is a crucial factor in determining the quality of life after retirement. Therefore, when receiving your severance pay, you must first open this account and submit the necessary documents to the responsible department.
Receiving severance pay via IRP defers taxes and lowers the tax rate when receiving it as a pension later, which is advantageous for protecting your assets.
3. Tax Deduction Benefits and How to Use the Limits

One of the most welcome benefits for workers preparing retirement funds is the tax deduction they can receive during the year-end tax settlement. You can enjoy tax deduction benefits on contributions up to a maximum of 9 million won when combining pension savings and Individual Retirement Pensions. For workers with a total annual income of 50 million won or less, a higher deduction rate is applied, resulting in a substantial tax refund. Many employees enjoy the satisfaction of putting in a little money each month and receiving a refund of several hundred thousand to over one million won at year-end. Since it offers the dual benefit of saving and saving on taxes, it is increasingly popular for new graduates to join actively.
However, to receive the tax deduction, there is a condition that you must maintain the account for at least five years and receive the funds after the age of 50. If you deposit money solely for the deduction benefit and cancel the account urgently, you may have to return the benefits you have received so far. Mr. Park, an employee, filled the limit every year, which allowed him to receive a large refund during last year’s year-end tax settlement, enabling him to take a family trip. This way, setting contribution amounts strategically becomes an excellent strategy to achieve both asset formation and tax savings. It is advisable to wisely determine your monthly contribution amount considering your income level and financial capacity.
You can receive tax deduction benefits up to 9 million won annually, allowing you to solve both tax savings and retirement preparation simultaneously.
4. Mandatory Safe Asset Ratio and Investment Methods
There is a rule you must strictly follow when managing money in this account: at least 30% of your total assets must be allocated to safe assets. The law has established this safeguard to prevent you from investing your entire amount in equity funds or high-volatility stock trading products. Recently, more investors are utilizing bond-mixed products or interest-rate-based products to meet the safe asset ratio while pursuing stable returns. For example, by appropriately mixing equity products that track stock indices with safe bonds, you can complete a balanced portfolio. Since this is retirement money, the key is to generate returns that can beat inflation while minimizing the risk of principal loss.
In the past, people mostly managed their money through deposits and savings, which often resulted in returns lower than the inflation rate. However, with the recent launch of various products that can hold diverse bonds and high-quality assets, the range of choices has widened significantly. Mr. Choi, an employee, is steadily generating returns by holding stable products mixed with U.S. Treasury bonds in accordance with the safe asset regulations. Rather than blindly investing in risky assets, you need the wisdom to choose products that match your investment style and manage them long-term. You can change your portfolio anytime through financial company apps, allowing you to respond flexibly to market conditions.
At least 30% of your total assets must be in safe assets, and you should make balanced investments through various bond-mixed products.
5. Beware of the Tax Bomb from Early Cancellation
While accumulating retirement funds, there may be cases where you suddenly need a large sum of money and consider canceling the account, but this is a very risky choice. If you are forced to cancel the account early before the age of 55, you must return all the tax deduction benefits you have received. Furthermore, you will be subject to a tax of over 15% under the name of miscellaneous income tax on the management profits and deferred severance income. Seeing your hard-earned assets shrink due to taxes is bound to bring immense regret. Therefore, it is safer to think of the money in this account as an “ultra-long-term emergency fund” that you should not touch until retirement.
If you are in a situation where you must use the money, it is wiser to look into the special early withdrawal system rather than canceling the account unconditionally. If you meet the reasons specified by law, such as purchasing a house as a non-homeowner, securing a deposit for a lease, or bankruptcy or medical treatment for yourself or a family member, you can withdraw the funds at a lower tax rate. Mr. Jeong, an employee, needed a lump sum to buy a house and, upon researching the system, found that he met the special withdrawal requirements, allowing him to significantly reduce his tax burden. It is essential to contact a bank or securities company advisor before blindly pressing the cancel button to find ways to minimize the tax impact. To protect your valuable severance pay, the most important attitude is to accurately understand the tax regulations and respond accordingly.
Early cancellation can result in a high tax bomb, so you should first check the special withdrawal requirements and maintain the account as much as possible.
6. Outlook for Utilizing IRP for a Successful Retirement
Thanks to various government policy supports and tax system reforms, the importance of Individual Retirement Pensions is expected to grow even further. In the past, it was merely a warehouse for storing severance pay, but it has now evolved into a core financial platform for actively growing assets. Employees are also focusing on systematically managing their assets through this account rather than worrying about their post-retirement life. As more diverse high-quality financial products are expected to be added to the account in the future, managing returns will become much easier. We hope that all employees preparing for retirement will actively utilize this system to welcome a comfortable and leisurely retirement.
How about checking the return rate of your account right now and reviewing whether your portfolio is well-structured? Small attention and practice can accumulate to become a sturdy support that completely changes your retirement life 10 or 20 years from now. If you diligently take advantage of tax benefits and prevent unnecessary cancellations, anyone can complete successful retirement funds. I recommend establishing your own asset management principles that will not waver even in the changing financial environment. The Retirement Pension IRP is the most powerful weapon to firmly protect your happy retirement.
You must prepare solidly for the approaching retirement period through systematic asset management and consistent contributions.
Frequently Asked Questions
=