If you rely solely on the National Pension and take your retirement for granted, you may face severe living expense shortages when you actually retire. Therefore, you must start preparing a personal pension immediately. Lately, from young adults to those in their 40s and 50s approaching retirement, there is deep distrust regarding the fiscal stability of public pensions. In reality, it is almost impossible for children to send hundreds of thousands of won in pocket money every month, so you must build your own safety net for survival. In the past, there was a belief that the state would fully take responsibility for old age, but that structure is now significantly shaken. Therefore, we must actively utilize personal pensions, which are the final piece of the three-tier pension tower and our most reliable weapon. In this article, we will specifically examine why we need to join a personal pension now and how to structure our portfolio.
=
Why You Need a Personal Pension: Planning for Retirement Amidst the National Pension’s Depletion
1. The Limits of Public Pensions and the Need for Personal Pensions
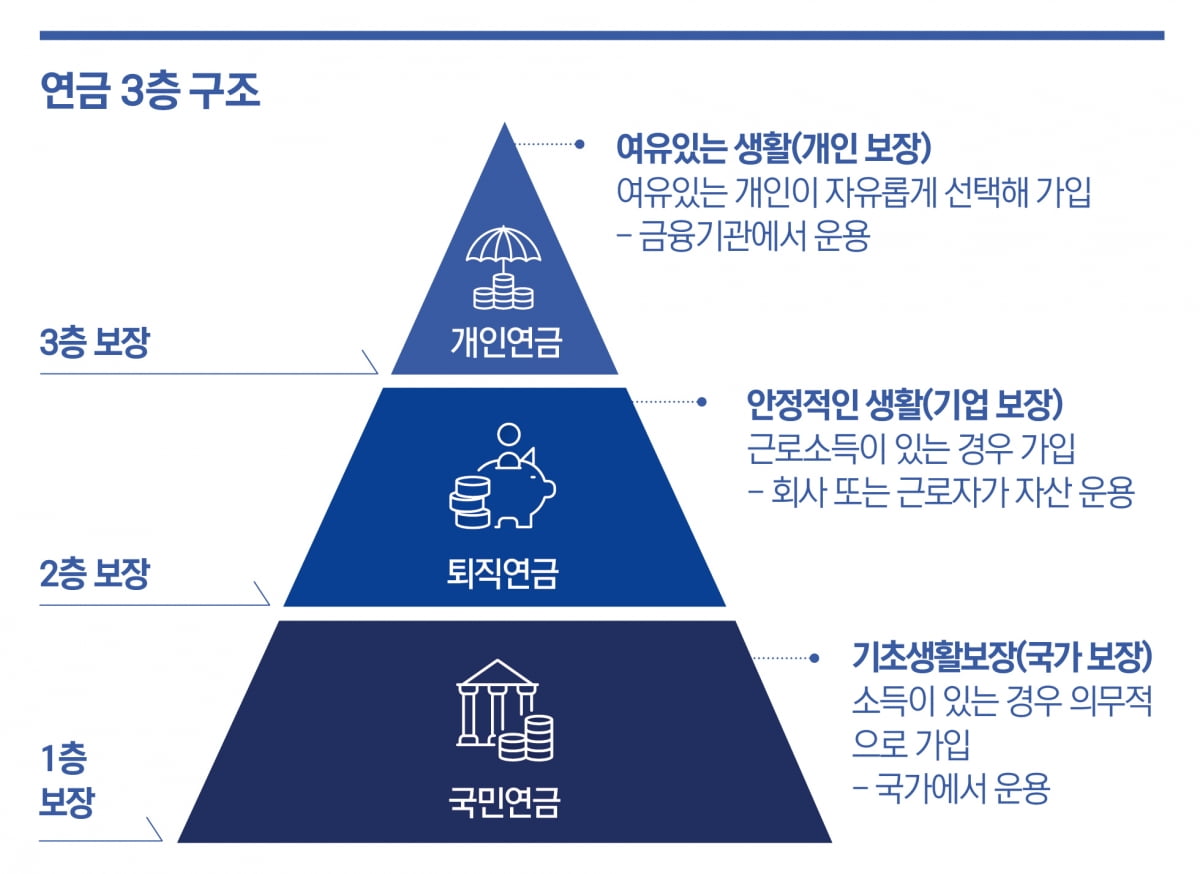
It is becoming increasingly difficult to fully support life after retirement with just the National Pension, which we diligently pay into every month. Economic experts constantly warn that the depletion date of the fund is being brought forward due to severe low birth rates and aging. Relying on the younger generation for support is close to impossible given economic realities, so we must save for our old age entirely on our own. If we retire without preparation, the social safety net may fail to function properly, forcing us into a harsh struggle for survival. To overcome this unstable situation, a private pension system where we save a fixed amount monthly is essential. When state systems waver, the only shield that protects you is ultimately the savings product registered in your own name.
Because the income replacement rate of the National Pension continues to decline, there is an urgent need for means to cover the shortfall in living expenses. You must keep in mind that maintaining a minimum standard of dignity after retirement requires much more money than you might think. Mr. Kim, an office worker, recently ran a retirement simulation, was shocked by the results, and immediately started making additional payments into pension products. At a time like this, the attitude of designing your own retirement with your own hands, without relying on others, is more important than ever. Instead of merely fearing an uncertain future, you must set up a practical savings plan right now.
As the fiscal instability of the public pension system grows, joining a private pension to protect your own retirement has become a necessity.
2. The Structure of the Three-Tier Pension Tower and Hidden Tax Traps
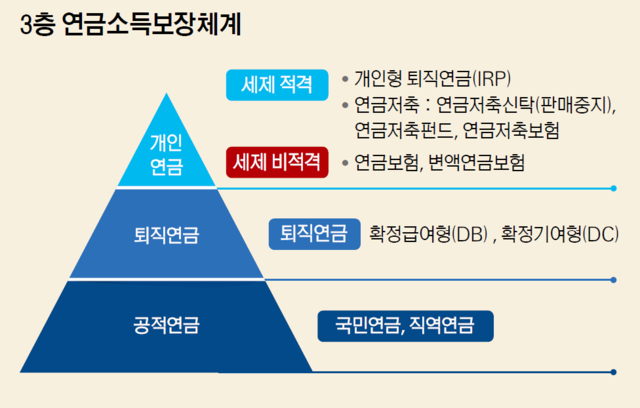
Many people boast that they have built a sturdy “three-tier pension tower” by combining the National Pension, corporate pension, and personal pension. However, when they actually start receiving their pensions after retirement, they are often greatly shocked by the amount deposited into their accounts. This is because the estimated benefits commonly seen during the planning stage are mostly pre-tax amounts with no taxes deducted. In reality, when receiving pensions at each stage, various taxes such as income tax or pension income tax are applied, reducing the actual amount received. If you do not accurately understand this tax structure in advance, your expected living expense plan after retirement may be completely thrown off track.
For example, if you receive your severance pay in the form of a pension or have received tax deductions by joining a personal pension savings account, those amounts become taxable when received later. Depending on whether they are included in comprehensive income taxation, you could face a tax bomb, so it is advisable to seek expert advice. Retirement planning is not just about saving a lot; how wisely you reduce taxes determines the overall return on investment. Therefore, you need the wisdom to carefully consider the scale of tax benefits and the future tax burden from the moment you choose a product. Do not trust only the surface numbers; you must thoroughly prepare based on the after-tax amount that actually enters your account.
Even if you have built a sturdy pension tower, if you do not calculate the taxes incurred upon receipt, your actual living expenses will be significantly short.
3. How to Maximize Tax Savings with Pension Savings
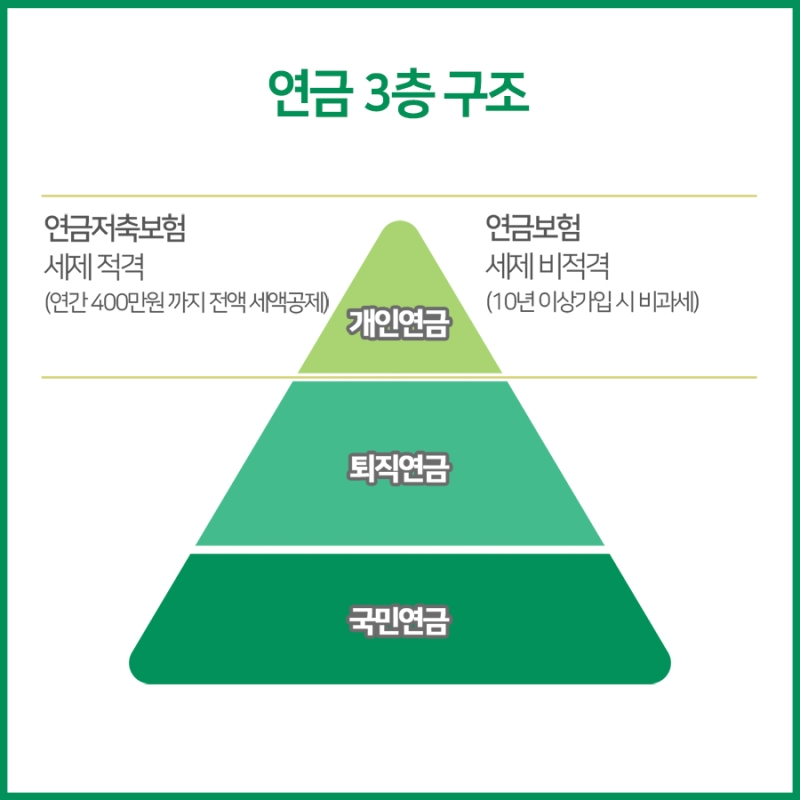
For both office workers and self-employed individuals, pension savings products are a grateful wealth management tool that provides significant tax deductions during the year-end tax settlement. Since you can get a certain percentage back based on the amount paid in, it is one of the most reliable ways to legally save on taxes. Recently, securities firms have been significantly increasing the variety of tax-saving financial products to improve investor convenience. Mr. Park, a young office worker, reinvests his entire year-end tax refund into his pension account every year, growing his assets faster than others. In this way, you can enjoy the two-fold benefit of carefully taking advantage of tax benefits while simultaneously securing funds for your future retirement.
However, if you terminate a pension savings product midway, you may face the disadvantage of having to return the tax benefits you received. Therefore, a long-term approach of consistently paying in monthly with surplus funds that you do not need immediately is very important. By utilizing various securities firm platforms, you can also directly invest in funds or exchange-traded funds (ETFs) according to your investment style. Whether you pursue principal protection and stable interest or engage in aggressive investing is up to your choice. If you capture both tax benefits and investment returns based on a thorough plan, your life after retirement will be much more abundant.
Pension savings is the best tax-saving product that provides valuable annual tax deduction benefits and helps with long-term asset formation.
4. Portfolio Strategies for Safe and Certain Asset Management
In the new normal era where inflation rates are soaring and the economic environment is changing rapidly, how you manage your pension assets determines your survival. Simply depositing a fixed amount every month is not enough; periodic asset allocation tailored to global economic trends is necessary. Recently, in the financial market, services have emerged that partner with asset custody specialists to safely keep valuables or physical assets. In this way, various financial institutions are rapidly introducing premium asset management systems for retirement customers. Retirement-focused blogs are seeing great popularity with articles sharing portfolios that invest a fixed amount monthly on a recurring basis.
When joining investment-type products, you should appropriately adjust the ratio of stocks to bonds according to your age and risk tolerance. As retirement approaches, it is safer to gradually increase the proportion of safe assets to protect the principal. Conversely, if you are still young, it is advantageous to mix in somewhat aggressive investment products to defend against inflation. Experts always emphasize the principle of diversification, which means not concentrating assets in one place but distributing them across multiple baskets. If you undergo a consistent rebalancing process every month, you can complete a stable retirement asset regardless of how the market fluctuates.
To have a successful retirement in a rapidly changing economic situation, periodic asset allocation and thorough diversification are essential.
5. Checking Your Estimated National Pension Benefits and Calculating the Shortfall
To check your exact retirement preparation status, you must first accurately check your estimated benefits through services like the National Digital Service. By visiting portal sites or the relevant public corporation’s homepage, you can easily find out your expected amount with just a few identity verifications. In this process, future income changes, inflation rates, and the average income level of all participants are comprehensively reflected. After checking, if the estimated amount is too low, you must immediately calculate the shortfall. Usually, the remainder after subtracting the estimated public pension amount from the minimum living expenses needed after retirement is the target amount you need to fill with a personal pension.
Mrs. Lee, a housewife, recently checked her estimated National Pension benefit and was shocked by the unexpectedly low amount, deciding to fill the gap with a personal pension. Instead of trembling with vague anxiety, facing your reality clearly with numbers is the first step in problem-solving. Only when you specifically grasp how much living expense is missing can you set an accurate goal for how much to save each month. Since the estimated benefit amount may change slightly according to economic indicators announced each year, it is a good habit to check regularly. This small act of objectively checking your current position becomes the magic key to creating a comfortable and leisurely retirement.
You must regularly check your estimated National Pension benefit and calculate the shortfall in living expenses to set an accurate personal pension goal.
6. Small Habits That Change the Future: Starting Pension Planning Today
When you start preparing for retirement is the most decisive factor in determining success or failure, and starting right now is the wisest choice. As time passes, the effect of compound interest becomes powerful, so those who join even one year earlier have a significant advantage. To climb the great mountain of retirement, the small savings habit practiced today becomes the most reliable climbing gear. For those just entering society, opening a pension account with a small, manageable amount is a great first step. The moment your future self will be most grateful to your past self is the moment you decisively decided to join a pension today.
Listen to the government’s pension reform discussions and changes in the financial market, but do not forget that you are ultimately the subject who protects your own life. Life after retirement, which may feel overwhelming and scary, can be beautiful enough with concrete plans and consistent practice. Open your smartphone app or visit your main bank today and carefully compare personal pension products suitable for you. One small decision will gift you a dignified and respectable retirement without having to ask your children for help. We cheer for your brilliant retirement and hope you take action now to dig a well of assets that will never run dry.
The longer you delay retirement preparation, the more you lose, so starting pension savings today, even with a small amount, is the most certain retirement strategy.
Frequently Asked Questions
=