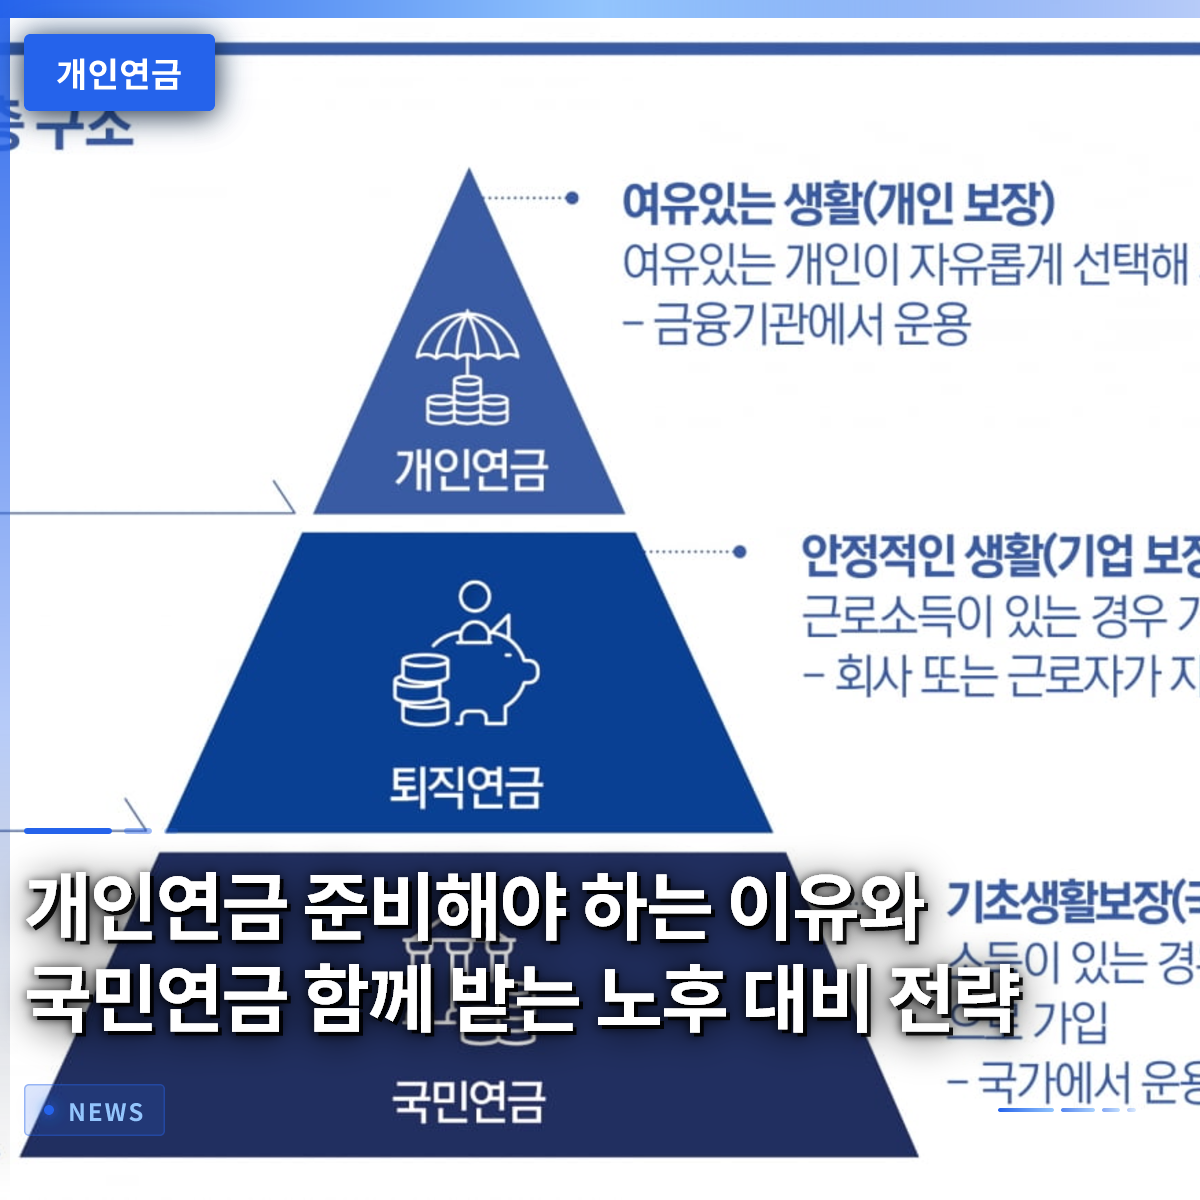
To complete a stable retirement life, you must not rely solely on the National Pension; you need to start preparing a personal pension immediately. This is because the importance of a financial foundation to support life after retirement is growing daily, driven by rapidly rising prices and increasing life expectancy. I often see acquaintances who have recently retired sighing as they look at the living expenses hitting their bank accounts every month. In reality, when you calculate how much retirement funding is needed, it becomes easy to realize that the amount guaranteed by the state is grossly insufficient. In this article, we will detail various methods for securing a pension that can complement the limitations of the National Pension and firmly protect your retirement. We hope that readers will take this opportunity to carefully review their retirement assets and formulate a practical plan.
=
Why You Need a Personal Pension: Strategies for Retirement Income Alongside the National Pension
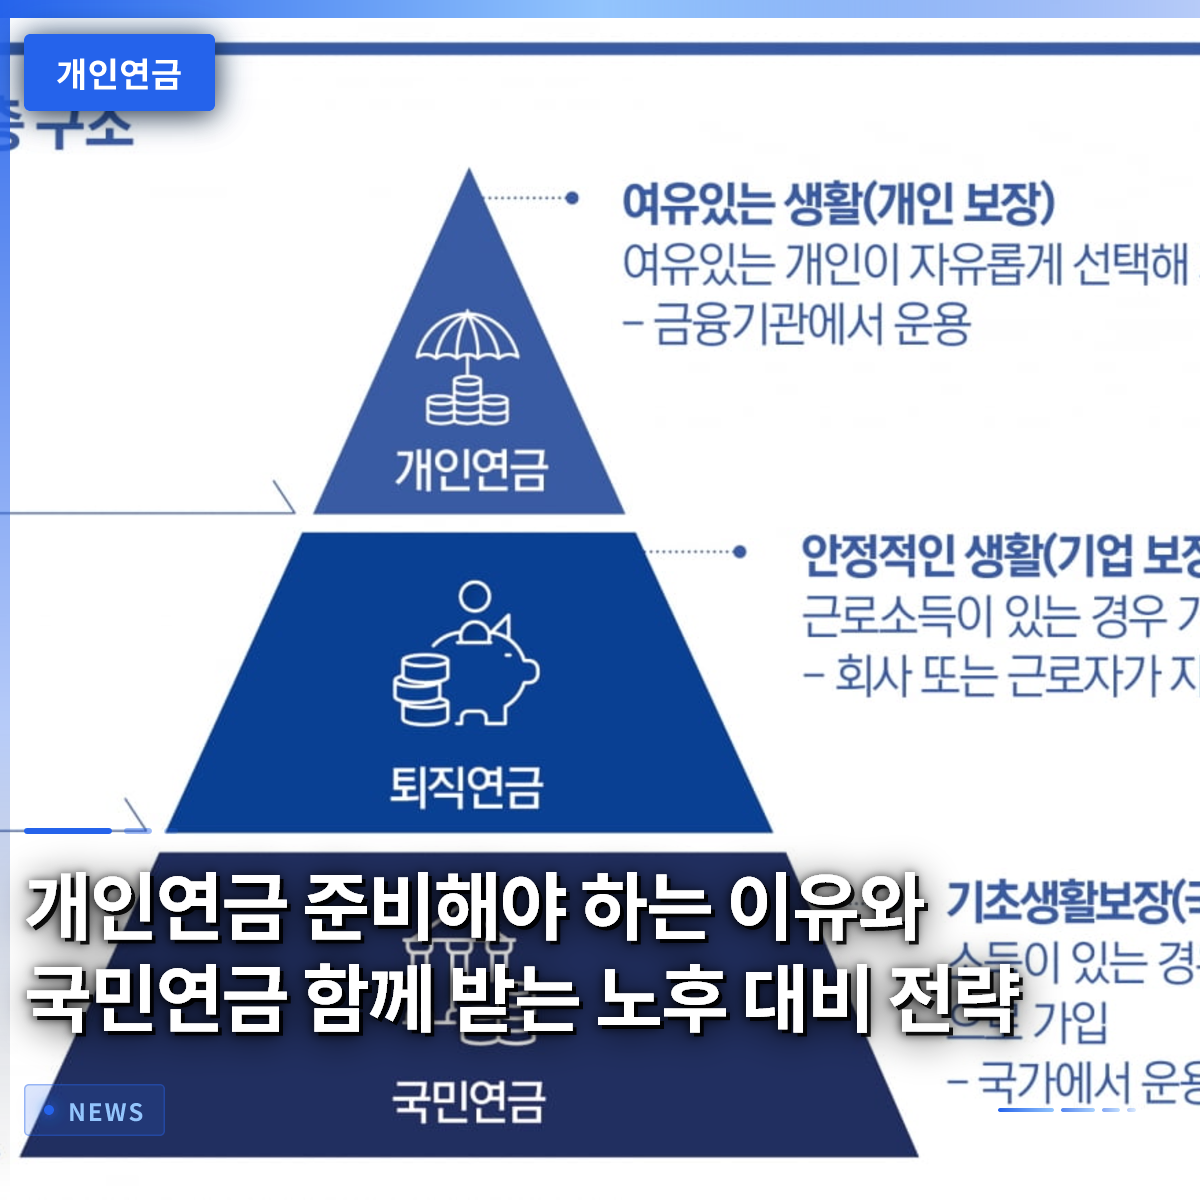
1. Limitations of the National Pension and Complementary Measures

If you wait for retirement relying solely on the National Pension system, you may face significant financial difficulties in old age. Even if you have worked for a long time, the actual amount received often falls short of expectations because it does not fully reflect inflation rates. Looking at cases of people around us with short enrollment periods or broken career histories, we can see that the monthly amount is often insufficient to cover basic needs like food, clothing, and shelter. Since the basic amount paid by the state is difficult to meet the baseline for retirement living expenses, an additional income source is essential. Ultimately, it is wise to actively utilize private products or retirement pensions that individuals enroll in directly to cover the shortfall in living expenses. More people are choosing to transfer the funds received upon leaving their jobs into pension accounts to be received in installments over a long period, rather than using them as a lump sum. It is essential to grow assets by managing investment products directly through various accounts offered by securities firms or banks. Only by completing a structure where individuals fill the gaps left by the national system can one feel truly secure. The habit of saving and investing on one’s own is the most powerful weapon that determines the quality of life in retirement.
Additional preparation through private products and retirement pensions is essential to cover the insufficient retirement living expenses that the National Pension alone cannot meet.
2. Understanding Types and Features of Personal Pensions

There are a wide variety of financial products on the market, so you must wisely choose the method that suits you. The most well-known tax-deductible products are very popular among office workers because they offer the benefit of receiving a tax refund during the annual tax settlement. If you pay in diligently and receive the funds in pension form when you reach retirement age, you can significantly reduce your tax burden. On the other hand, there are also savings-type products that focus on tax-exempt benefits rather than tax deductions, so you should choose based on your income level. Investment-type accounts enrolled through securities firms allow you to actively increase returns by selecting assets such as funds or exchange-traded funds (ETFs) yourself. By consistently buying in fixed amounts monthly, you can grow your assets over the long term without being shaken by market volatility. Stable products enrolled through banks have the advantage of principal protection, but considering inflation rates, their asset growth effect is somewhat disappointing. Therefore, you need the wisdom to appropriately combine these two methods by comprehensively considering your investment style and the remaining time until retirement.
You should understand the characteristics of various types, such as tax-deductible products and investment-type accounts, and choose the method that suits you.
3. Maximizing Tax Benefits and Tax Savings

One of the biggest attractions of using a pension account is the substantial tax refund received during the annual tax settlement. It is considered a representative wealth management tool actively encouraged by the state because it alleviates the burden of income tax that office workers pay monthly. You can receive a deduction for a certain percentage of the amount paid in during the year, which can noticeably boost your actual rate of return. Seeing colleagues brag about the amount they receive as a refund during the annual tax settlement season often makes one regret not starting this system sooner. Additionally, when receiving the pension after retirement, a much lower tax rate is applied compared to general income tax, allowing you to minimize the tax burden. If excessive taxes are imposed in a situation where income decreases with age, it can deal a heavy blow to retirement life. Once you reach the age where you can enjoy the benefit of low-rate separate taxation, you can use your funds comfortably with greatly reduced tax worries. The taxes saved this way are usefully employed either as a source for reinvestment or to supplement living expenses for a more comfortable life. The tax-saving effect enjoyed annually through consistent contributions is a major driving force that sustains retirement preparation.
You can increase the real value of your assets through the annual tax deduction and the low-rate taxation benefit applied upon receipt.
4. The Ideal Combination of National and Personal Pensions
To enjoy a stable retirement life, the key is to construct a portfolio that harmoniously arranges the two systems. The basic benefit amount guaranteed by the state serves as a solid foundation, coming in as a fixed monthly income. When the cash flow from private products prepared separately by the individual is added to this, a comfortable living expense is finally completed. In fact, when running retirement fund simulations, it is most stable when the two pillars share the majority of the target living expenses evenly. In the early stages of retirement, activity levels are high, and costs for medical care and leisure are relatively significant, requiring more cash flow. At this time, it is a wise retirement strategy to actively withdraw the assets you have accumulated to enjoy a life without shortages. As time passes and you get older, basic expenses decrease, and you can maintain your life sufficiently with just the fixed benefit amount. Therefore, you must plan a system in advance that flexibly adjusts the inflow and outflow of funds according to the life cycle.
You must harmoniously mix the public system that builds a foundation with private products that create flexible cash flow.
5. The Magic of Compound Interest: Start in Your Youth
To enjoy the effect of compound interest, where assets grow over time, you must open an account as soon as possible, even if it is just one day earlier. In the early stages of one’s career, the word “retirement” feels too distant, making it easy to focus only on immediate consumption or short-term savings. However, if you develop the habit of consistently paying in small amounts monthly while you are young, it will return as an enormous difference later on. I recommend setting up an automatic transfer of a certain portion of your salary to pension assets from the moment you take your first step into the workforce. You can often hear stories of people who realized the importance of retirement late and tried to save money in a rush but failed. If time is short, the amount that must be paid in monthly increases accordingly, acting as a serious burden on household economics. On the other hand, those who prepared steadily from their 20s or 30s show that they can reach their target assets comfortably even with small amounts. The wisdom of sacrificing a little of today’s consumption for the sake of your future self ultimately leads to a comfortable and dignified old age.
You must start consistent contributions, even with small amounts, at an early stage to fully enjoy the magic of compound interest.
6. Practical Steps for a Successful Retirement
You must immediately look transparently at your current financial asset status and create an action plan to fill in the gaps. Start by logging into your bank or securities firm application and carefully checking and reviewing the details of the products you are currently enrolled in. If you have not made any preparations yet, I recommend opening a new pension savings account, even with a small amount, and setting up automatic transfers. In the coming aging society, the most reliable friend that will protect the dignity of your life is ultimately the assets you have accumulated yourself. Imagine the future you smiling while looking at the deposit notifications hitting your bank account every month, and take a step forward starting today.
You must check your current asset status and put it into practice immediately by opening an account and setting up automatic transfers today.
Frequently Asked Questions
=