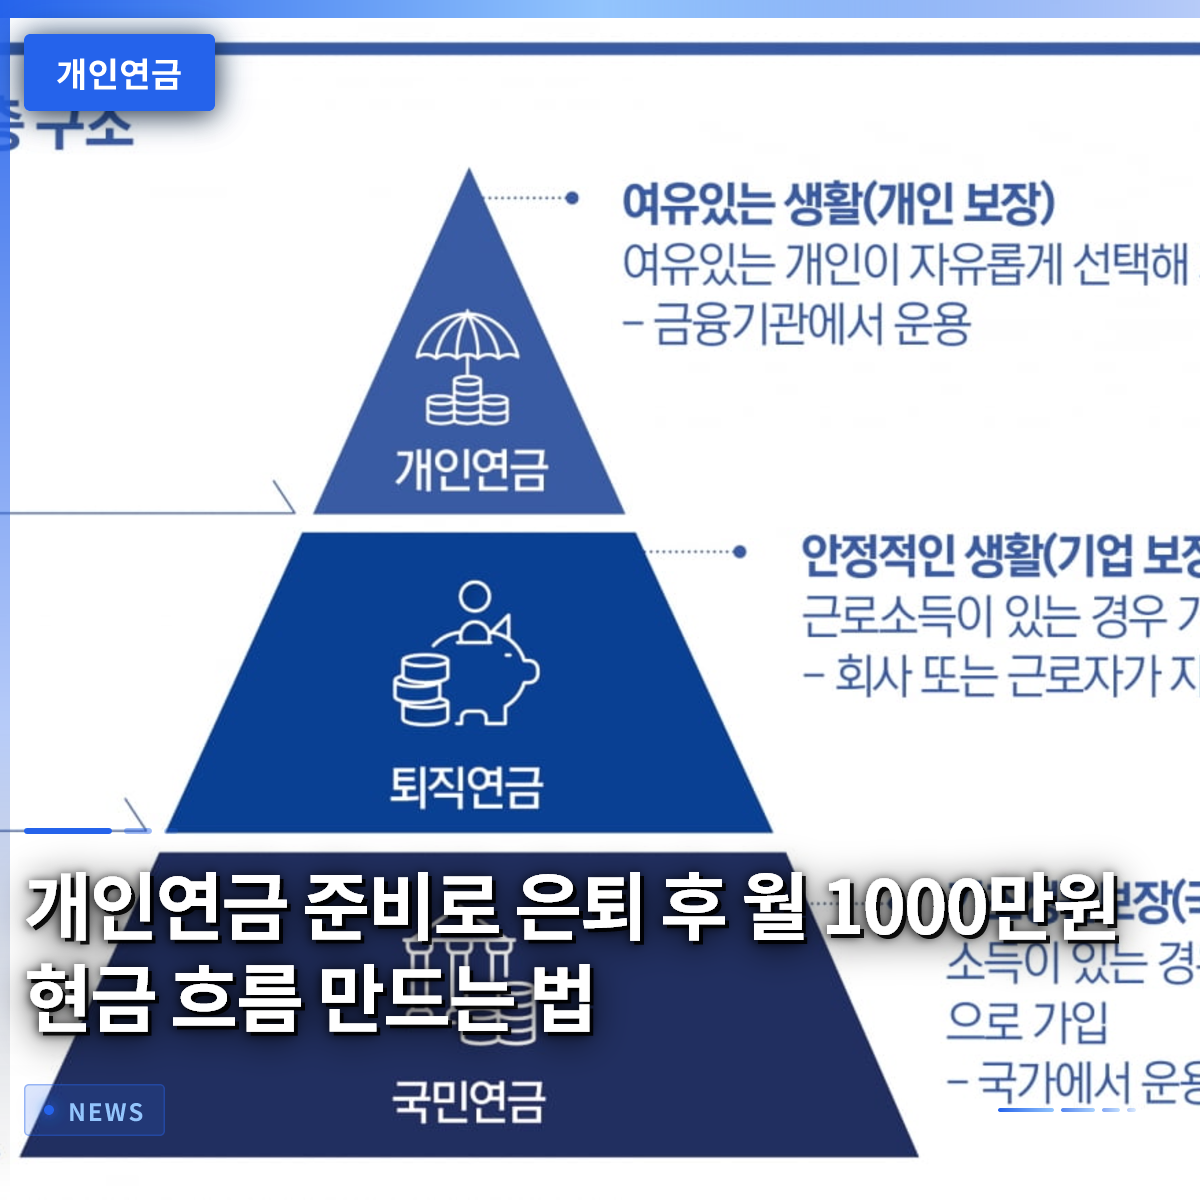
To establish a stable cash flow after retirement, you must start preparing your personal pension immediately. We often see friends who shouted “YOLO” and spent freely in their younger days deeply regretting their choices and starting to save assets once they hit their 40s. As proven by cases where individuals accumulated seed capital in their 40s and grew their assets into the hundreds of millions of won through long-term investments in U.S. stock index-linked products and various financial instruments, time can be on our side. Relying solely on severance pay or the National Pension is often insufficient to keep up with inflation, making self-funded preparation essential. This article will meticulously cover everything from how to check your status via the Integrated Pension Portal to specific asset allocation and tax-saving strategies. I hope this article helps you find a clear path through the daunting task of retirement planning.
=
How to Build a Monthly Cash Flow of 10 Million Won After Retirement Through Personal Pension Preparation
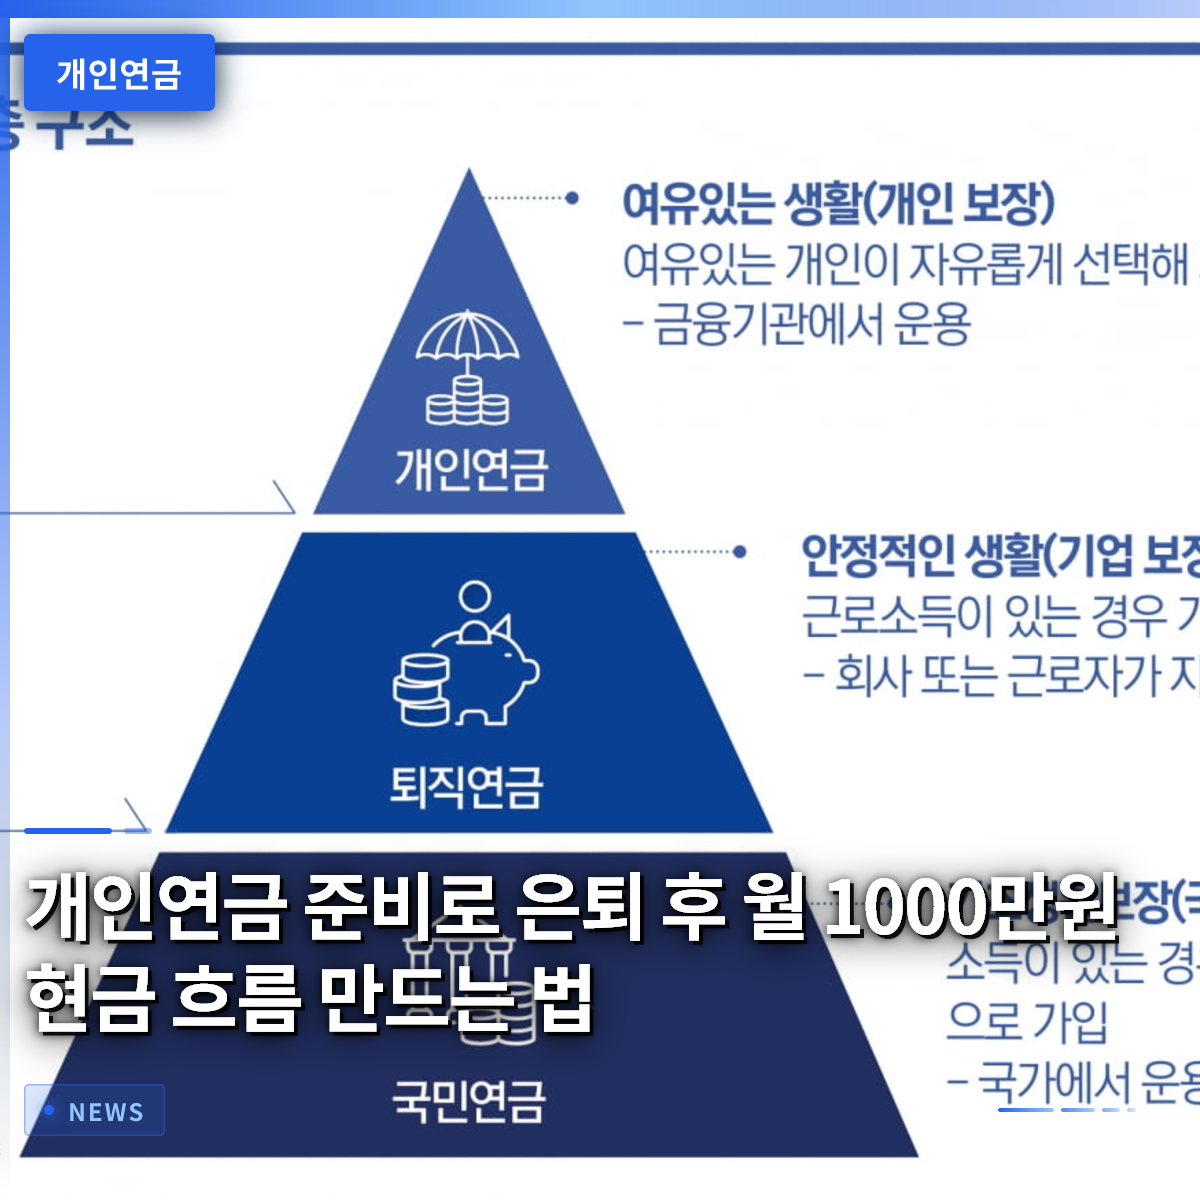
1. Getting a Clear Overview of Your Pension Status via the Integrated Pension Portal

Checking all the pension products you have joined so far in one place is the first step toward successful retirement fund planning. By using the Integrated Pension Portal site operated by the Financial Services Commission, you can verify the National Pension, corporate pensions, and individual products all at once. If multiple financial products you signed up for during your working life are scattered, it can be difficult to grasp the total scale of your assets. The inquiry process provides detailed expected pension amounts by income period, allowing you to intuitively calculate how much additional living expenses you will need. Occasionally, depending on the type of your company’s pension system, the balance in specific accounts may not be immediately visible. However, this does not mean your valuable pension information is missing or lost, so there is no need to worry excessively. Due to the nature of Defined Benefit (DB) plans, it is structurally difficult for individuals to directly check monthly contributions, which can cause discrepancies at the time of inquiry. In such cases, it is safer to contact your company’s relevant department or the financial institution directly to confirm the exact contribution details. Simply knowing the exact scale of your assets makes your future financial direction much clearer.
Use the Integrated Pension Portal to check all scattered pensions at a glance and accurately grasp the scale of your retirement assets.
2. Long-Term U.S. Stock Investment Strategy Starting in Your 40s

To grow your assets rapidly before retirement, a long-term investment strategy that leverages the growth potential of the stock market is essential. Recently, among investors in their 40s, a method of consistently investing in products tracking major indices like the S&P 500 or Nasdaq 100 has become very popular. By not getting overly excited or depressed by short-term stock price fluctuations and instead buying a fixed amount monthly through systematic accumulation, a massive asset base can accumulate before you know it. Those who stepped away from a YOLO lifestyle, controlled their spending, and poured all their surplus funds into index products have achieved surprising returns in just a few years. When engaging in such long-term investments, it is wise to utilize systems that maximize tax benefits rather than using general accounts. Operating both an Individual Retirement Pension (IRP) and an Individual Comprehensive Asset Management Account (ISA) simultaneously allows you to enjoy both tax deduction benefits and tax-exempt effects. The refunds received at the end of each year during tax settlement can be reinvested, becoming a magical financial tool that maximizes compound interest. Investors who stick to their principles without wavering even in highly volatile markets ultimately secure a successful retirement.
Invest long-term in index products like the S&P 500 and utilize tax-advantaged accounts to grow your assets rapidly.
3. Realistic Design for a Monthly Cash Flow of 10 Million Won After Retirement

The dream of a monthly cash flow of 10 million won after retirement is only possible when backed by thorough preparation and diversified income sources. Looking at the additional income sources that famous broadcasters and writers have consistently prepared for before retirement, a common pattern emerges. They did not rely on a single source of income but built multiple pipelines, including stock dividends, real estate rent, and personal pension contributions. The result of rationally controlling expenses and investing surplus funds in asset growth from a young age begins to shine brilliantly in one’s mid-to-late 50s. The total scale of pension assets in our country is still in its infancy compared to developed nations. While it is disappointing when compared to the massive assets rolling in overseas markets, the amount deposited into your account can vary significantly depending on individual effort. Even if it is not the huge sum of 10 million won, creating a cash flow sufficient for a couple to live comfortably is a perfectly achievable goal. The habit of setting aside a fixed amount each month and steadily accumulating it in a pension account is the most reliable preparation for the future.
Create a comfortable cash flow after retirement through diversified income sources and consistent pension contributions.
4. Protecting Personal Pension Assets During Personal Rehabilitation
When forced to apply for personal rehabilitation due to an unexpected economic crisis, one of the biggest concerns is the safety of valuable pension assets. Many people lose sleep worrying that the insurance or pension products they have struggled to pay into monthly might be seized or canceled in an instant. However, not all products are subject to mandatory execution; there are ways to be protected based on strict court criteria. Courts make flexible judgments regarding pension assets that meet certain conditions, considering the debtor’s minimum human dignity and retirement security. Court rulings may vary depending on the time of enrollment, the type of product, and the current contribution status. Therefore, if you enter rehabilitation proceedings, you should consult with experts in the field to find ways to protect your assets. Rather than giving up unconditionally, active measures are needed to protect retirement assets within the framework allowed by the legal system. If you accurately understand the nature of your pension account and respond accordingly even in a crisis, you can sufficiently prevent the worst-case scenario.
Pension assets may be protected during personal rehabilitation proceedings depending on court criteria and product type, so consult with an expert.
5. Rebalancing Pension Assets to Respond to Volatile Markets
Investors’ hearts burn as they watch the returns in their pension accounts fluctuate every time the stock market swings. In such times, it is important to periodically review and rebalance your portfolio rather than letting emotions drive you to hit the sell button. In a situation where market-leading themes change frequently, wisdom is needed to appropriately adjust the ratio between safe and risky assets. Holding a balanced mix of quality products from various sectors acts as a sturdy shield, where other assets defend against losses if a specific stock declines. Recently, in the financial market, products that reinterpret traditional asset allocation methods in a modern way to respond to volatility have become popular. Looking at the products that individual investors have bought the most, there is a clear trend of pursuing both stable cash dividends and capital appreciation. You must maintain a sense of balance by opening your account on a regular monthly cycle, selling off assets that have grown too large in proportion, and buying more of underperforming assets. This mechanical asset management habit strengthens the fundamental health of your pension account in the long run.
Flexibly respond to market volatility and enhance account stability through periodic rebalancing and asset allocation.
6. Practical Advice and Outlook for a Successful Retirement
As we have seen, a prosperous retirement is not achieved overnight but is completed through consistent practice over a long period. Prices continue to rise, and the economic environment flows in unpredictable directions, but thoroughly prepared assets will not betray us. Accurately checking your current position via the Integrated Pension Portal and the simple act of depositing a fixed amount into your pension account every month can change your future. I recommend that you leave the YOLO era behind and start paying attention to U.S. index products or tax-saving accounts starting today. The future financial environment will become even more complex, and the weight of being responsible for your own retirement will only grow heavier. Only wise investors who actively utilize government support systems and various financial products can enjoy a leisurely life after retirement. Stop hesitating and visit a nearby financial institution or open your mobile app right now to open a pension account. Small beginnings will accumulate to become the strongest and most reliable economic fence that supports you for the rest of your life.
Do not delay; check your pension account today and start consistent contributions to prepare for a stable future.
Frequently Asked Questions
=