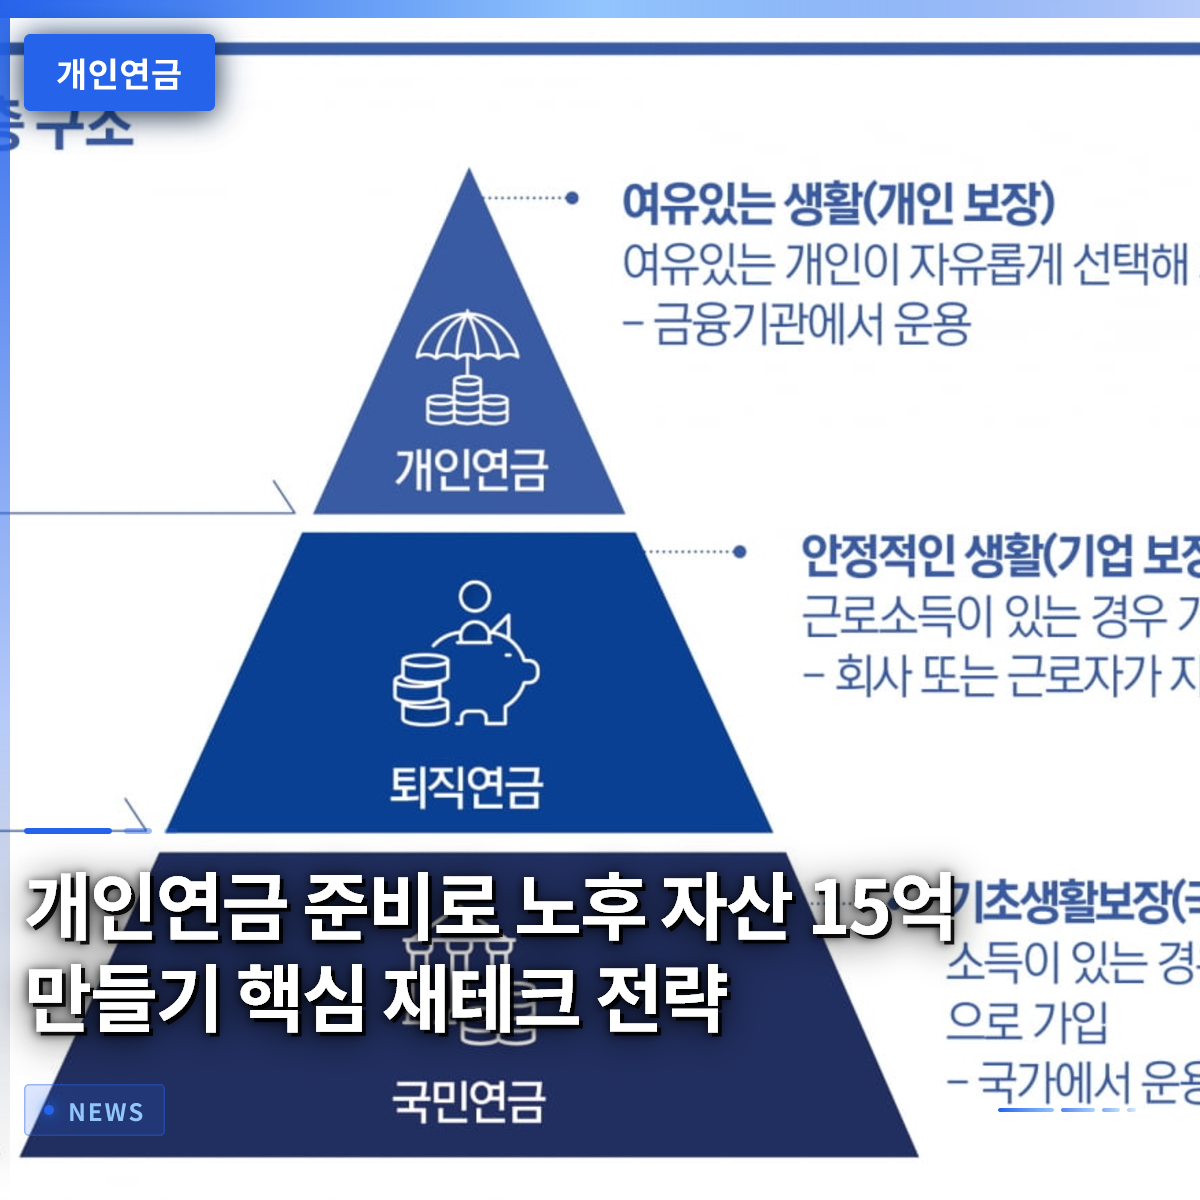
If you dream of a stable retirement, the most reliable solution is to open a personal pension account immediately and set up automatic monthly transfers. Looking around, you will find many people who realize too late that the National Pension alone will not be enough to cover their living expenses as retirement approaches, leading to regret. In fact, the common trait among those who have consistently grown their assets over more than a decade to accumulate hundreds of millions of won in their 40s is that they actively utilized individual retirement pensions and personal pension savings from an early stage. It is essential to adopt a smart fund management approach that not only involves simple savings but also navigates volatile markets while taking advantage of tax benefits. In this article, we will thoroughly cover everything from enrolling in a personal pension to specific management methods that will guarantee a prosperous life after retirement. We hope you will gain practical wisdom that you can put into action starting today.
=
Building 1.5 Billion Won in Retirement Assets Through Personal Pension Preparation: Key Wealth Management Strategies
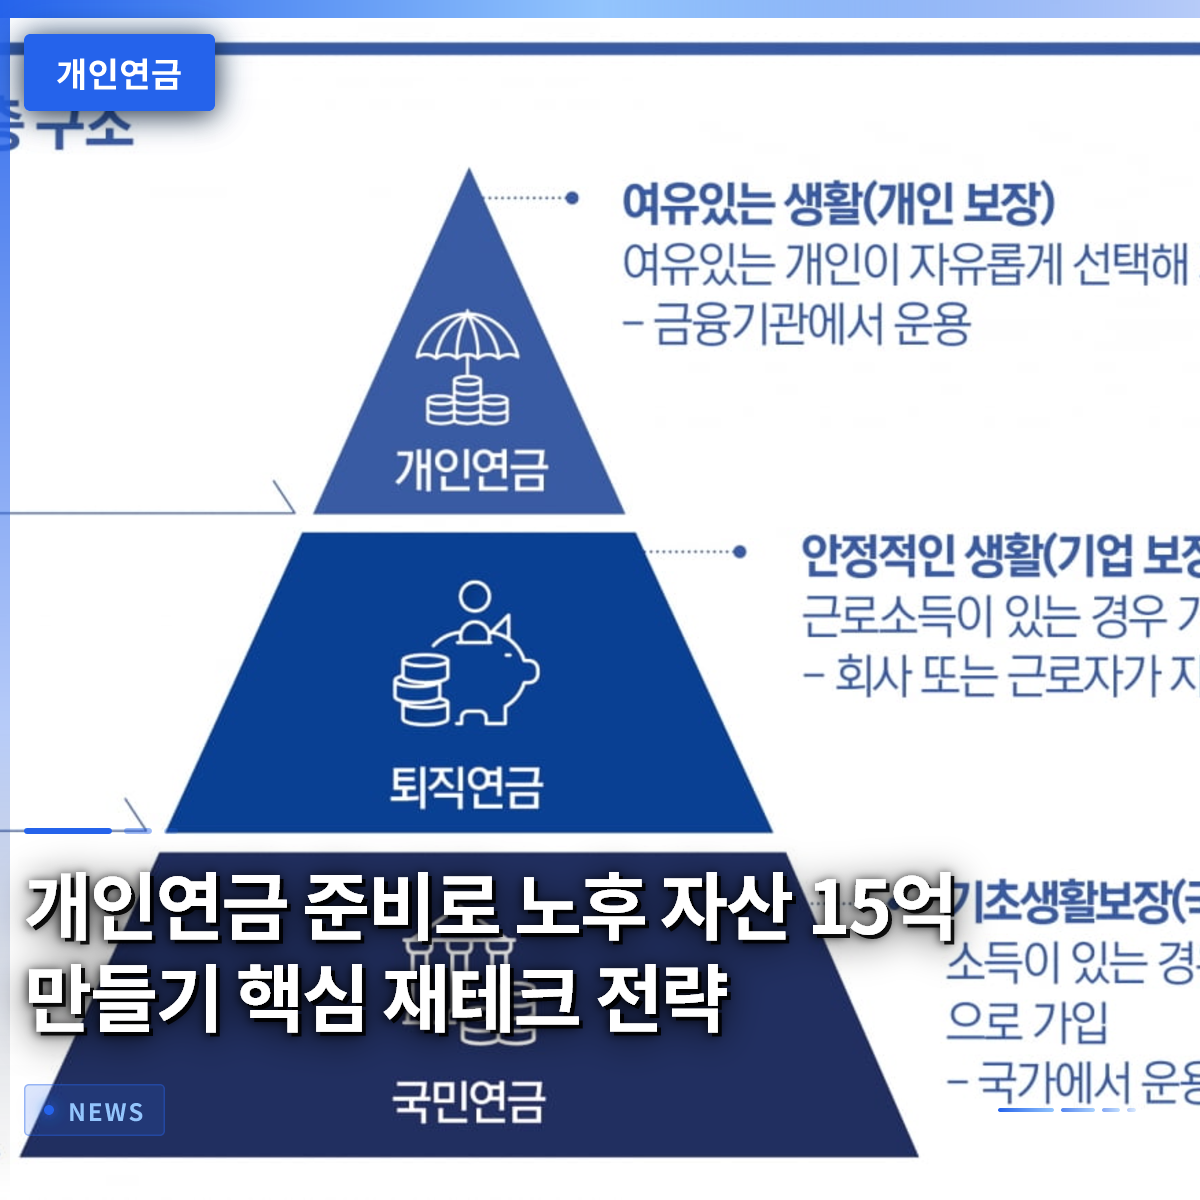
1. Why You Should Start a Personal Pension Now

When preparing for retirement, relying solely on the National Pension or corporate pension can lead to significant financial setbacks. It is disheartening to face the reality that the projected pension amount you will receive is far insufficient to cover living expenses, especially as prices rise sharply every year. In fact, as the period of income loss after retirement for office workers lengthens, the value of personal pensions prepared in one’s youth is shining brightly. Observing people in their 50s who boast a monthly cash flow of several million won, it is clear that they meticulously prepared private pensions before retirement. We have entered an era where the pension paid by the state alone is struggling to cover skyrocketing medical costs and basic living expenses. Therefore, the reason why you must reduce unnecessary monthly expenses to deposit money into a personal pension account right now lies precisely in this reality.
If you indulge in a lavish lifestyle in your youth and delay saving, you will eventually face unbearable economic pain. The case of a 40-year-old office worker who, after enjoying the “YOLO” culture and focusing only on present happiness, suddenly woke up to start investing and built assets worth hundreds of millions of won offers a significant lesson. They did not simply save their salaries; they also secured tax deduction benefits and diversified their long-term investment funds between personal pensions and comprehensive asset management accounts. This difference in small habits becomes the decisive factor that completely changes the quality of life in old age. If you do not start now, you will have to pay a high price later, so you should begin by looking into opening a pension account today. While you hesitate, prices will rise further, and the opportunities available to us will diminish.
You should start a personal pension immediately to prepare for a retirement that the National Pension alone cannot cover.
2. Checking Your Pension at a Glance via the Integrated Pension Portal

Few people know exactly how much they have contributed to the National Pension, corporate pension, and personal pension so far. By using the Integrated Pension Portal service operated by the Financial Supervisory Service, you can easily check all this information with a single login using a public certificate. You can save significant time and effort without having to visit multiple financial institution websites to find your enrollment details. Once you grasp the contribution status and expected benefit amounts of the pension savings products registered in your name at a glance, you can formulate a clear plan for how much more you need to save. Occasionally, companies operate their corporate pensions as DB (Defined Benefit) plans, so the accumulated amount may not be immediately visible in your personal account; this is not an omission, so you can rest assured.
Accurately assessing the current state of your assets in this way is the first step and most important foundation for successful wealth management. If you only feel vague anxiety without checking your actual balances, your retirement preparation will inevitably remain flawed. After easily completing the inquiry via smartphone or computer, please set a specific monthly contribution amount to fill the gap. If there are any products where contributions have unexpectedly stopped, it is wise to rectify them immediately to fill the gap in your assets. The courage to open the inquiry screen right now and face your pension report card creates future prosperity.
Using the Integrated Pension Portal allows you to grasp your scattered pension assets at a glance and fill in the gaps.
3. The Powerful Weapon of Tax Benefits and Pension Savings

The most attractive feature of enrolling in a personal pension is undoubtedly the substantial tax deduction benefit available during the year-end tax settlement. Since a certain percentage of the amount contributed consistently each year is refunded from your taxes, it is considered an essential tax-saving tool for office workers. By filling up to the limit set by the National Tax Service, you can enjoy the double benefit of protecting your hard-earned money while simultaneously growing your retirement funds. In fact, for many wealth management experts, the personal pension savings contribution record is the first item they check when the year-end tax settlement season arrives. Since you can get the money that would have gone to taxes back into your account to use as a seed for reinvestment, there is no better deal.
However, be careful: if you enroll solely for the tax deduction benefit and cancel the account midway, you may have to return the benefits you received. Pension products are, as the name suggests, long-distance races that must be run to the end to reveal their true value. Even if sudden funding needs arise, you need the wisdom to maintain your pension account and utilize other emergency funds instead. The longer the contribution period, the more the compound interest effect is maximized, allowing you to witness the miracle of your principal snowballing. This is an excellent strategy that achieves both the immediate benefit of tax savings and the long-term goal of a secure cash flow after retirement.
The core advantage of a personal pension is enjoying long-term compound interest effects while securing year-end tax deduction benefits.
4. Wise Asset Allocation and Utilization of Equity Assets
Within a personal pension account, you should not simply accumulate cash but actively grow your assets by investing in various financial products. The most widely used method is long-term investment in products that track major U.S. stock market indices such as the S&P 500 or the Nasdaq 100. By consistently investing in an upward-trending index through dollar-cost averaging, even in volatile markets, you can lower your average purchase price. People who internalized this investment strategy from a young age experience explosive growth in their asset size over time. While referring to portfolios recommended by experts, it is important to adjust the appropriate weightings considering your investment style and the remaining time until retirement.
On the other hand, caution is needed as there are cases where investors lose assets by recklessly investing in single stocks or risky derivatives. For individual investors to stably accumulate retirement funds, it is safer to structure the account primarily with high-quality products that diversify across the entire market. By setting up automatic purchases on a fixed date each month, you can mechanically accumulate assets without being swayed by emotions. This structure allows you to buy more units at lower prices when the market falls and see your assets grow when it rises. This robust asset allocation structure creates a warm cash flow that comes in like a salary every month after retirement.
You must build assets that are not shaken by volatility by investing in high-quality index products through long-term dollar-cost averaging.
5. Crisis Situations and Legal Protection of Personal Pensions
In life, you may encounter unexpected economic crises or fall into extreme difficulty due to debt issues. Many people worry whether their personal pension accounts, which they have diligently contributed to, will be entirely seized if they undergo legal debt adjustment procedures. Fortunately, not all personal pensions are automatically subject to seizure; the court comprehensively reviews factors such as the enrollment date and contribution status. Since this system is designed to guarantee a minimum livelihood in old age, legal protection is available under certain conditions. Therefore, even during economically difficult times, it is wise to carefully examine relevant laws and regulations rather than rashly canceling your pension account.
In difficult moments, it is most important to steady your mind and protect your pension assets, which are your last line of defense for the future. If you give up or recklessly withdraw funds based on incorrect rumors from others, you will incur significant losses that are hard to recover. You need to make the effort to find ways to safely protect your assets by consulting with experts or following accurate guidance from relevant agencies. Like a shield that withstands storms, personal pensions serve as the final support when our lives are most shaken. A firm mindset that does not let go of retirement preparation even in crisis ultimately completes a successful retirement.
Even in economic crisis situations, personal pensions protect your valuable retirement assets through legal protection mechanisms.
6. Mindset and Action for a Successful Retirement
As we have seen, personal pensions are not just simple savings products but the most powerful weapon determining the quality of life in old age. The small action of opening your pension account today and starting automatic transfers with a manageable monthly amount creates big changes. Imagine yourself smiling ten or twenty years from now, and sincerely plant the seeds in this moment. Only those who exercise the wisdom to prepare for the future while others shout “YOLO” and enjoy the present can enjoy true financial freedom after retirement. If you walk the path steadily while securing both the magic of compound interest and tax-saving benefits, you will certainly be reborn as a successful asset holder. Do not delay any longer; turn on your smartphone today, check your pension account, and start a new leap.
Only when consistent action is combined with a long-term perspective can you achieve a successful retirement and financial freedom.
Frequently Asked Questions
=