Personal pension savings are an essential financial product that helps secure stable living funds after retirement while simultaneously allowing you to claim substantial tax refunds during your annual tax settlement. Mr. Kim, an office worker, says he was on the verge of having to pay additional taxes during last year’s settlement but was able to breathe a sigh of relief thanks to his personal pension savings. Many people feel overwhelmed when trying to choose from the countless products available on the market. Recently, directly investing in stocks or index-tracking products rather than interest-based products has gained popularity as a way to defend against inflation. Through this article, we will carefully examine everything from tax deduction limits to management tips via securities firms. If you do not prepare for retirement in advance, you may face significant financial difficulties later, so you must start preparing now.
=
How to Prepare for Retirement with Personal Pension Savings Tax Deduction Limits and Fund Management
1. What is Personal Pension Savings and Why Should You Join?

Personal pension savings are a representative tax-saving account created by the government to help secure income in old age. By saving a certain amount every month, you can enjoy the exceptional benefit of receiving a tax refund during your annual tax settlement. This is why many office workers join this product, hoping for a 13th-month salary every year. These days, as retirement ages are getting younger, statistics continue to show that the National Pension alone is far from sufficient for a comfortable retirement. Therefore, it is more important than ever to gradually build assets through a personal account from a young age. In reality, if you look around, many retirees find themselves having to look for jobs again later in life because they lack living expenses after retirement. People who opened pension accounts in their youth enjoy a comfortable life because they built their assets while enjoying tax benefits. Compared to simply letting money sit in a basic savings account, there is a huge difference in tax savings and investment returns. Therefore, if you have any spare funds right now, there is no reason to delay joining.
Personal pension savings are the most reliable means to secure both retirement preparation and annual tax settlement deductions.
2. The Decisive Differences Between Pension Savings Insurance and Funds
In the past, most people joined insurance products offered by banks or insurance companies to receive stable interest. However, as the low-interest-rate environment has prolonged, many people have been disappointed by low returns that cannot even keep up with inflation. On the other hand, fund products joined through securities firms allow you to directly invest in various index-tracking products listed on the stock market or in high-quality companies. For example, investing in a product that holds stocks of major U.S. corporations can be expected to yield much higher asset growth effects in the long term. While insurance products have the advantage of principal protection, considering the rate of inflation, the real value of your assets may actually decrease. Fund products fluctuate in price depending on market conditions, so they may seem unstable in the short term, but they are much more advantageous for long-term investments of ten years or more. In fact, when comparing the final asset size of someone who invested in insurance versus someone who invested in funds over ten years, a huge gap emerges. Since retirement funds are money that will be kept for at least ten years, it is wise to invest in assets that can withstand volatility and trend upwards.
If you want long-term asset growth, fund management through a securities firm is more advantageous than principal-guaranteed insurance.
3. Complete Guide to Tax Deduction Limits and Rates for 2026

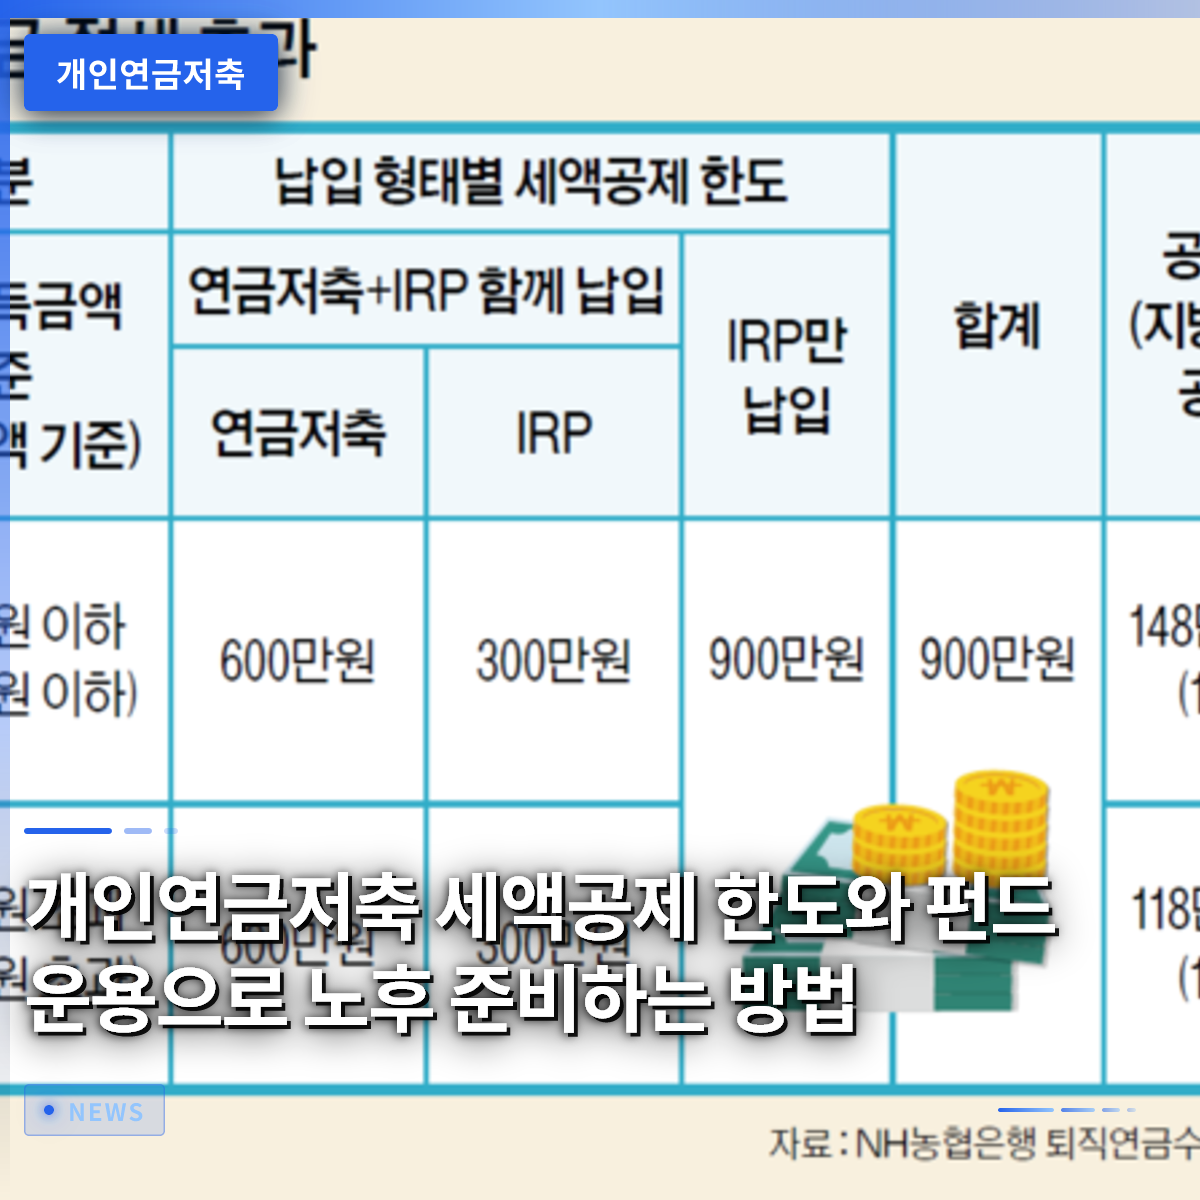
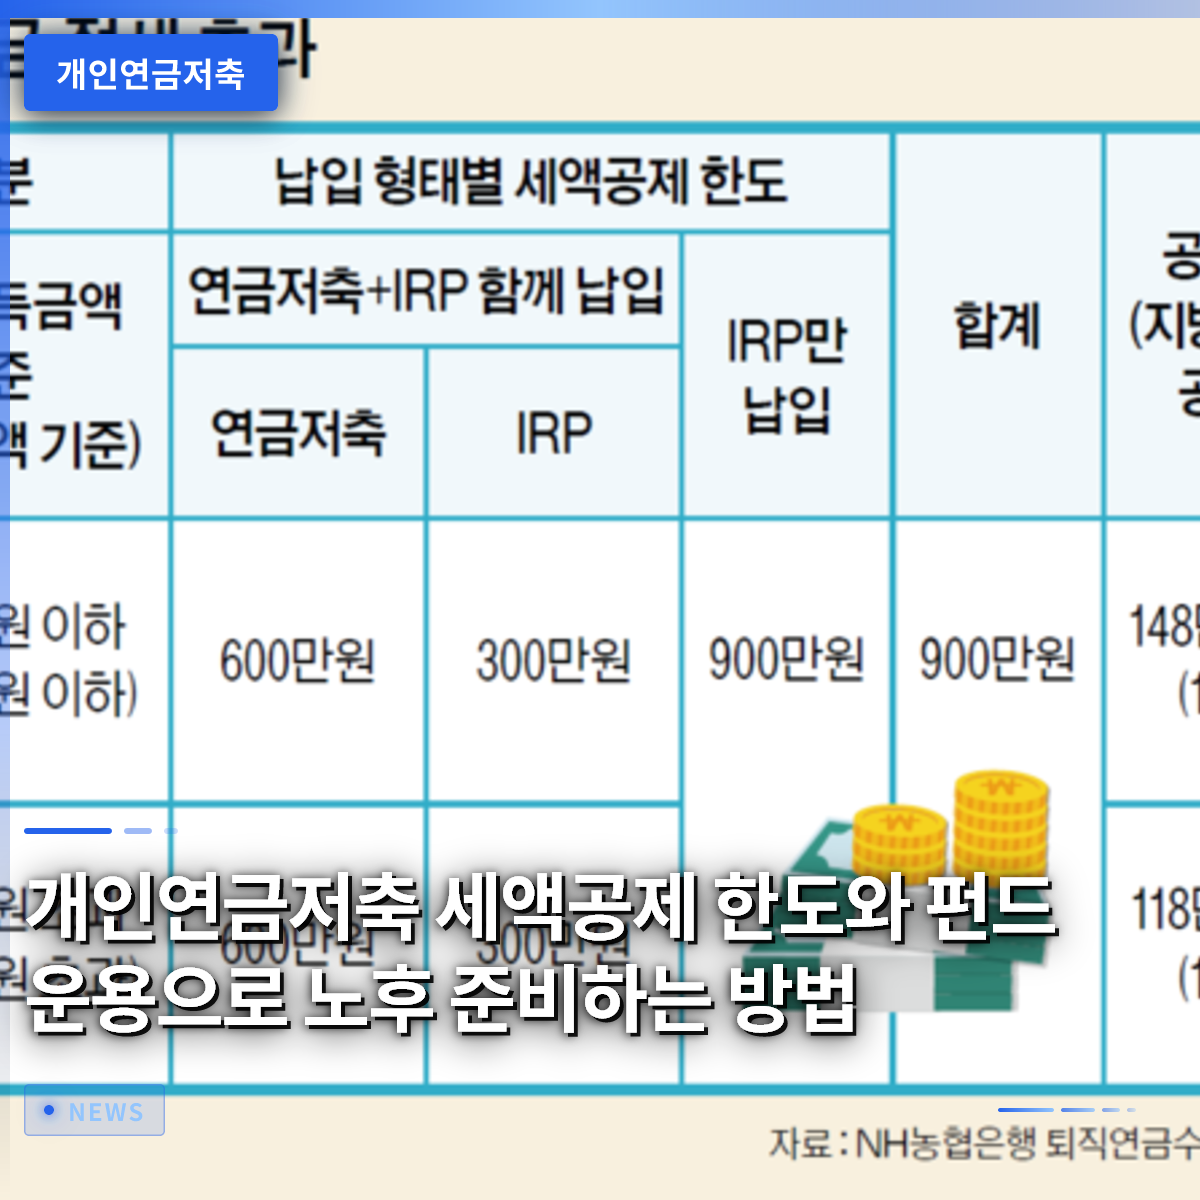
Under current tax laws, personal pension savings are eligible for tax deductions up to a maximum of 6 million won annually. If you also contribute to an Individual Retirement Pension (IRP) alongside this, the deduction limit increases to a combined maximum of 9 million won across both accounts. Office workers with a total annual income of 55 million won or less can enjoy a high deduction rate of 16.5%, receiving a refund of up to 1.485 million won. Even if your total income is higher, you can still receive a substantial refund with a 13.2% deduction rate. Office workers who consistently contribute 500,000 won monthly to reach the annual 6 million won limit feel a great sense of accomplishment every tax settlement season. It is equivalent to accumulating valuable money that would have gone to taxes directly into your account, providing a two-for-one benefit. Occasionally, some people cannot fill the limit due to a lack of lump-sum funds, but you can still enjoy sufficient benefits by contributing as much as your budget allows. The important thing is to develop the habit of contributing consistently every year and maintaining the account without closing it midway.
Combined deductions are possible up to a maximum of 9 million won annually, with refunds of up to 16.5% depending on income level.
4. Investment Strategies Using Index-Tracking Products and High-Quality Companies
Within a pension savings account, you can freely choose and trade various domestic and international equity or bond products. In particular, diversifying investments into products that track the entire U.S. market or representative high-quality corporate stock indices is the most popular method. Mr. Park, an office worker, sets up automatic transfers to buy a U.S. index-tracking product with a fixed amount every month, allowing him to focus on his daily life. Instead of selling in panic whenever the market wobbles, he consistently accumulated shares, resulting in excellent long-term performance. While individual company stocks carry the risk of bankruptcy, index-tracking products that invest in global economic growth have a very high probability of trending upwards in the long term. If you reinvest the refunds received from your annual tax settlement back into the account at the end of the year, you can maximize the effect of compound interest. By utilizing the automatic purchase features provided in securities firm apps, even busy office workers can easily continue their investments. While referring to the asset allocation ratios recommended by experts, you should adjust the ratio of stocks to bonds according to your own investment style.
Consistently accumulating U.S. index-tracking products using automatic purchase features allows you to enjoy compound interest.
5. Precautions Regarding the Tax Bomb from Early Termination
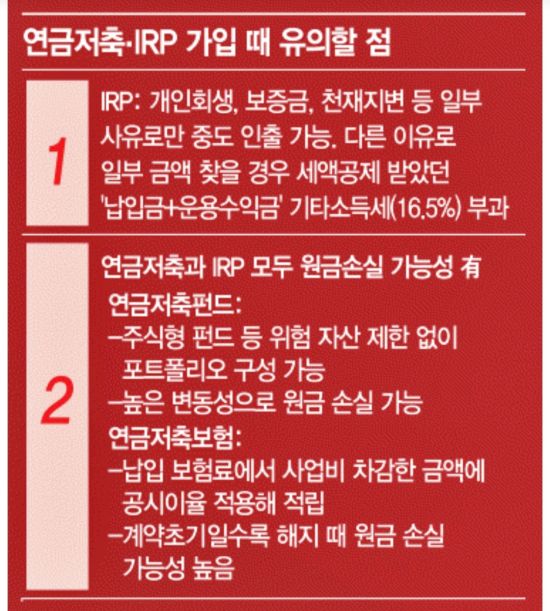
Although the account is opened for retirement, if you terminate it midway because you suddenly need a large amount of money, you may face unexpected disadvantages. A tax of a whopping 16.5% is imposed as miscellaneous income tax on all the tax deductions you have received so far and the investment returns generated during that period. This leads to the absurd situation where you have to pay out in taxes the money you carefully saved by avoiding taxes. Therefore, you should manage only your surplus funds with the mindset that you will absolutely not withdraw the money in this account until retirement. If you are in a situation where you inevitably need money, it is better to utilize a loan secured by the account balance instead of terminating it. Most securities firms offer services that lend funds at low interest rates using the pension account balance as collateral. This allows you to maintain the tax benefits while smartly putting out the immediate financial fire. If you have acquaintances considering termination, you must definitely inform them of these risks and alternatives.
Early termination requires paying back the benefits received, so you should use collateral loans when you need urgent funds.
6. Practical Guide and Outlook for a Successful Retirement
In the coming era of an aging population, thorough self-directed asset management will be the key factor determining an individual’s quality of life. Simply setting up automatic transfers from a portion of your monthly salary to a pension account can significantly reduce future anxiety. The government is also showing a trend of gradually expanding tax benefits to prevent old-age poverty among citizens. The small savings habit you start now will return as a huge asset that is hard to imagine ten or twenty years from now. Do not delay any longer; open a securities firm app today, open a pension account in your name, and start your first contribution.
Consistent pension savings started now are the only key to creating a prosperous and stable future.
Frequently Asked Questions
=