To secure high savings account interest rates reaching up to 6% annually, simply walking into a bank is not enough; thorough analysis of the terms and conditions is essential. Recently, as volatility in the financial markets has increased, high-interest savings products that help build stable assets have once again drawn attention. Mr. Kim, an office worker, reached the maturity date of a product he had casually signed up for last year and decided to carefully compare interest rates before joining a new one this time. He judged that it would be better to safely preserve his principal and secure definite interest, given the reports of high volatility in the stock market. In fact, recently launched special products often yield significantly higher interest than expected, provided that you meet their strict preferential conditions. In this article, we will compare the financial products offering the most favorable rates at the current moment and thoroughly uncover the secrets to maximizing your actual interest income.
=
Comparing the Best Savings Account Interest Rates in 2026 and Smart Ways to Maximize Earnings
1. Trends in High-Interest Products from Credit Unions
Some credit unions are introducing attractive fixed deposits and savings products with annual interest rates exceeding 4%, targeting the Chuseok holiday or specific seasons. In the past, you had to visit a physical branch to open an account, but now, with the activation of non-face-to-face transactions, anyone can easily sign up. For example, institutions like Anyang Credit Union offer relatively high interest rates, attracting many customers. As the number of credit union customers has surpassed 10 million, becoming widely popular, the competition for deposits among these institutions has become even fiercer. In this atmosphere, putting in a little extra effort can help you discover hidden gem products that offer much more favorable conditions than commercial banks. The sign-up process via mobile apps has also been greatly simplified, allowing busy office workers to easily manage their lump sums during their lunch breaks.
Consumers should not just look at the highest advertised interest rate number but must carefully calculate the actual after-tax interest they will receive. In the case of credit unions, under the Deposit Insurance Act, the principal and a modest amount of interest are safely protected up to 50 million won per person. Therefore, rather than putting all your spare funds into one place, a diversification strategy of depositing 50 million won at a time is essential. Looking at recent trends in the financial market, the preference for safe assets is clear, and the number of people seeking savings products remains high. When entering a period of rising interest rates, it is wise to manage lump sums by splitting them into moderate terms rather than locking them away for too long. Since the competition for special products among financial institutions is expected to continue, it is important to develop the habit of frequently checking for related news.
Using non-face-to-face products from credit unions can yield higher interest rates than commercial banks, and diversification within the deposit insurance limit is essential.
2. Nonghyup Health Promotion Special Products
Special savings products launched by Nonghyup affiliates are hugely popular because they allow customers to enjoy high interest rate benefits while taking care of their health in their daily lives. A representative example is the NH Credit Union’s “Correct Earth” regular savings plan, an eco-friendly health product that offers preferential interest rates if you commit to quitting smoking or engaging in eco-friendly activities. This product received a warm response immediately after its launch, with its limit quickly exhausted and sales ending early. Due to continuous requests from customers, it was recently re-released in limited quantities, offering an exceptional annual interest rate of up to 6%. If you are someone who consistently manages their health, you can naturally meet the preferential conditions, enjoying the double benefit of improved well-being and better returns. It is expected that financial products that encourage changes in lifestyle habits, rather than just saving money, will increase in the future.
Mr. Park, who had been deciding to quit smoking, found a product he liked this time and signed up, gaining significant motivation. This product is differentiated by pursuing the values of environmental protection and health promotion simultaneously while providing substantial economic rewards. If you wish to sign up, you must quickly check the conditions and proceed with the registration via the mobile app before the limited quantity is sold out. It is essential to carefully read the preferential conditions and check in advance whether you can realistically achieve the required items. Remember that small changes in daily habits can serve as a solid catalyst for increasing your account balance by year’s end. The integration of finance and daily life is set to become an important trend that will change how we manage our assets in the future.
You can secure high interest rates of up to 6% annually by meeting special preferential conditions such as health management and environmental protection commitments.
3. Interest Rate Comparison for Regional Nonghyup and Livestock Cooperatives
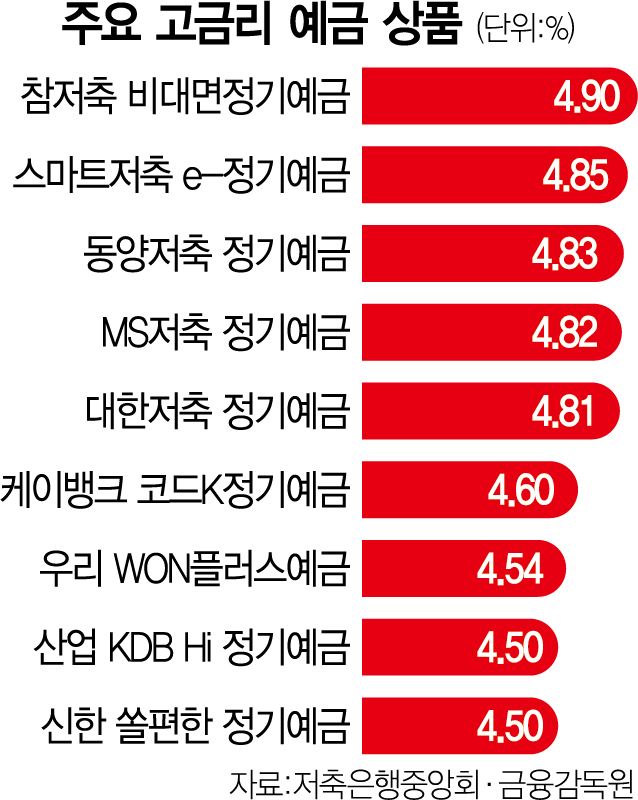
Regional Nonghyup and livestock cooperatives spread across the country operate by setting different interest rates on their own, even while following headquarters guidelines. Local cooperatives such as Gimpo Livestock Nonghyup, Geyang Nonghyup, and Daejeon Horticulture Nonghyup are attracting funds by offering interest rates higher than the commercial bank average. In fact, by checking official websites or related financial comparison platforms, you can easily see that there are quite significant interest rate differences by region. Therefore, the more effort you put in, the higher the probability of finding a solid product that offers slightly higher interest than others. Not only parents living in the provinces but also office workers in Seoul are increasingly signing up for products from cooperatives in other regions through non-face-to-face services.
However, when signing up for products from regional cooperatives, it is safe to briefly review the cooperative’s soundness indicators and management disclosures. You need the wisdom to check if delinquency rates and capital adequacy ratios are good and to manage your assets within the appropriate deposit insurance limit. Mr. Choi, a neighbor, carefully organized the interest rates of several regional cooperatives in an Excel file and signed up non-face-to-face for the one with the highest rate. As a result, he earned significantly more interest income than if he had deposited elsewhere, earning the envy of those around him. This shows that by tolerating a bit of hassle, you can secure a definite breakthrough to defend against inflation and grow your assets. The diligence to periodically search for hidden high-interest product information across the country determines the success of your financial management.
Interest rates vary by branch for regional Nonghyup and livestock cooperatives, so comparing them carefully and signing up non-face-to-face can yield higher returns.
4. Base Interest Rate Fluctuations and Deposit/Savings Strategies
Depending on the trend of the Bank of Korea’s base interest rate, which product—deposit or savings—is advantageous changes from moment to moment. Recently, as the base interest rate fluctuates around 3%, a reversal phenomenon where deposit rates are more favorable in the short term than savings rates often occurs. Mrs. Lee, a housewife, chose to lock a lump sum in a fixed deposit with a higher rate for a certain period rather than automatically putting it into a savings account whenever she had extra money. During periods of rising interest rates, locking funds for too long makes it difficult to switch to products with higher rates later, so keeping the maturity period short is advantageous. On the other hand, for young office workers who need to save a fixed amount from their monthly income, the savings account method remains the best tool for forced saving.
Experts advise that the greater the economic uncertainty, the more important it is to keep emergency funds in parking accounts that can be withdrawn at any time. Parking accounts are considered essential for emergency fund management because they offer interest even for a one-day deposit and allow immediate withdrawal when needed. When signing up for a savings account, you should set the automatic transfer date to immediately after your payday to prevent funds from leaking to other places. After accurately calculating the amount remaining after fixed monthly expenses, you should determine the savings amount within a reasonable limit. In times of rapidly changing interest rate environments, the ability to plan your liquidity and respond flexibly is more important than anything else.
During periods of base interest rate fluctuation, it is advantageous to put lump sums into short-term deposits, keep emergency funds in parking accounts, and make savings contributions aligned with your payday.
5. How to Secure 100% of Preferential Interest Rate Conditions
Do not be dazzled by the highest interest rate numbers advertised by banks; you must carefully evaluate the preferential interest rate conditions you can actually achieve. Many financial products impose conditions such as preferential rates for first-time customers, consent to receive marketing, and credit card usage records. Mr. Jung, a college student, hesitated because of a condition requiring him to issue a card he rarely used, but he met the conditions and ultimately received a high interest rate. However, if issuing a card you don’t usually use leads to unnecessary spending, it can result in a situation where you don’t even break even. Therefore, you need the cool-headedness to calculate whether the cost of spending to meet preferential conditions is less than the profit gained from interest.
In many cases, you can secure preferential interest rates simply by designating an automatic transfer account at that bank or meeting primary banking performance metrics. Items like consent to receive marketing are representative tips that anyone can easily meet by just changing a few smartphone notification settings. Before signing the contract, you must carefully read the terms and repeatedly check via the staff or app screen to ensure no conditions are missed. Occasionally, stories of regret appear on online communities where people failed to receive the preferential rate in the final month due to misunderstanding the conditions. The meticulousness to read even the small-print clauses is the key that ultimately makes your account balance substantial.
Avoid preferential conditions that induce unnecessary spending and increase your rate through simple items like notification settings or automatic transfers.
6. Outlook for Savings Strategies in the Second Half of 2026
The financial market in the second half of this year is expected to continue experiencing interest rate volatility due to domestic and international economic variables, making diversification more important than ever. Global economic indicators, such as the overheating controversy in the AI industry and movements in US Treasury yields, are causing subtle ripples in domestic savings products. In such times, rather than going all-in on a single product, it is necessary to have the wisdom to appropriately divide funds among deposits, savings accounts, and parking accounts. Mr. Kang, an office worker, has been following economic news daily and, in preparation for the possibility of interest rate cuts, has already signed up for multiple products with different maturity dates. He says that by diversifying the maturity of his funds, he can respond flexibly no matter how interest rates move, giving him much more peace of mind.
The most certain way to prepare for an uncertain future is to start now by reducing unnecessary expenses and building the habit of consistent saving. When news of high-interest special products comes out, you need the execution to open your mobile app without hesitation and quickly check the conditions and limits. Financial information is only visible to those who know it, and the structure is such that only those who act actively can enjoy greater interest benefits. Based on the various savings tips and product comparison insights reviewed today, we hope you will grow your precious assets safely and robustly. Imagine yourself smiling at a more substantial account balance around this time next year, and check your savings plan right now.
To safely protect your assets against second-half economic uncertainty, you should diversify maturity dates and build the habit of consistent saving.
Frequently Asked Questions
=