If you want to effectively save a lump sum, it is crucial to carefully examine not only the base interest rate but also the preferential interest rate items you can personally qualify for. Recently, special savings products that offer higher interest rates simply by practicing healthy habits, such as walking or quitting smoking, have gained significant popularity. For example, you can receive much more favorable terms than standard products just by walking more than 10,000 steps daily on your commute or keeping a pledge to quit smoking. Rather than blindly signing up for products recommended by others, you need the wisdom to select the most beneficial financial product that fits your lifestyle. In this article, we will clearly explain everything from how to compare interest rates across different banks to specific tips for uncovering hidden benefits. Let’s look at how to plan your savings to avoid losses during this period of high volatility.
=
How to Compare High-Rate Savings Accounts and Find Special Products Offering Up to 6% Annual Interest
1. How to Carefully Compare Base and Preferential Interest Rates
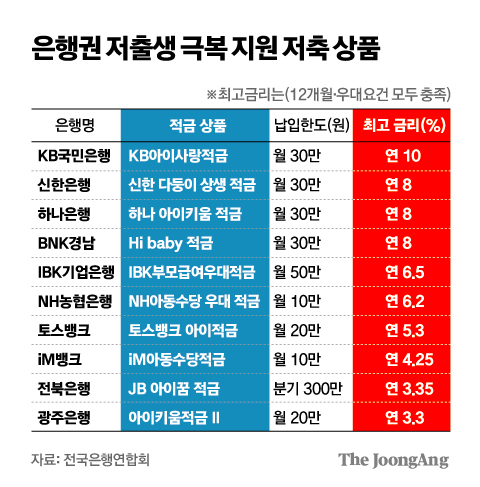
Many people sign up for savings accounts based solely on the highest interest rate prominently displayed at bank branches or on mobile screens, only to be disappointed by the significantly lower interest they actually receive. Behind the flashy advertising slogans of banks, there are often strict conditions hidden, making thorough analysis necessary. When comparing savings interest rates, you must first check the base rate and then evaluate which preferential rate conditions you can realistically meet. If it is difficult for you to meet basic conditions such as salary transfers, automatic transfers, or marketing consent, the actual applicable interest rate may be noticeably lower. Therefore, you should develop the habit of accurately calculating the final interest you will receive relative to the amount you diligently save each month. Do not rely solely on recommendations from people around you; the process of carefully comparing options according to your own financial transaction habits is the starting point for successful saving. The high numbers you see on mobile screens are usually the maximum interest rates that are only granted when all various strict ancillary transaction conditions are met. Rather than signing up unconditionally just because it is your main bank, you must make an effort to compare the conditions of several financial institutions side by side. In particular, since the applicable interest rate can vary depending on monthly contribution limits or the term of the account, it is advisable to read the detailed regulations carefully. If complex calculations are difficult, using a bank interest rate comparison website to compare figures at a glance is an excellent method. Although it may seem like a small difference, the interest amount returned after one year can vary significantly, so it is important to start off on the right foot.
When comparing savings interest rates, you should carefully evaluate the base and preferential interest rates you can actually achieve, rather than just the maximum rate advertised.
2. Unique Savings Products That Reward You with Extra Interest for Health Management
Recently, the financial sector has seen a surge in attention for unique products that go beyond simply depositing money by encouraging customers to adopt healthy lifestyle habits. Notably, methods that offer high preferential interest rates upon completing daily life challenges, such as hitting step count goals or making a pledge to quit smoking, are being actively operated. In fact, a specific regular savings product launched by a savings bank received a great response by offering an exceptional interest rate of up to 6% per annum for participating in smoking cessation and eco-friendly pledges. This product, which had sold out and ended its sales period, was even re-released in limited quantities due to strong customer demand. By verifying your daily walking exercise through a smartphone app and making a pledge to engage in eco-friendly activities you already practice, you can significantly boost your deposit and savings interest. These products, which allow you to save money while taking care of your health, offer a two-for-one benefit and provide busy modern people with a unique enjoyment of saving. These health-promoting financial products have the advantage of offering both small daily fun and a sense of achievement, moving away from the rigid traditional saving methods. You can receive interest rate benefits from the bank simply by walking a bit more on your commute or practicing quitting smoking, which you may have been intending to do for a while. From the perspective of financial companies, customer health also leads to risk management, making it a structure beneficial to both sides. However, since these special products usually have strict limitations on sales periods and the number of available slots, it is advantageous to hear about their release quickly. You need to be diligent by turning on notifications in the mobile financial apps you frequently use or frequently checking for related news.
Unique special products that offer high interest rates of up to 6% per annum for practicing health management habits like walking or quitting smoking are very popular.
3. Short-Term Savings Strategy Instead of 1-Year Maturity When Interest Rates Rise
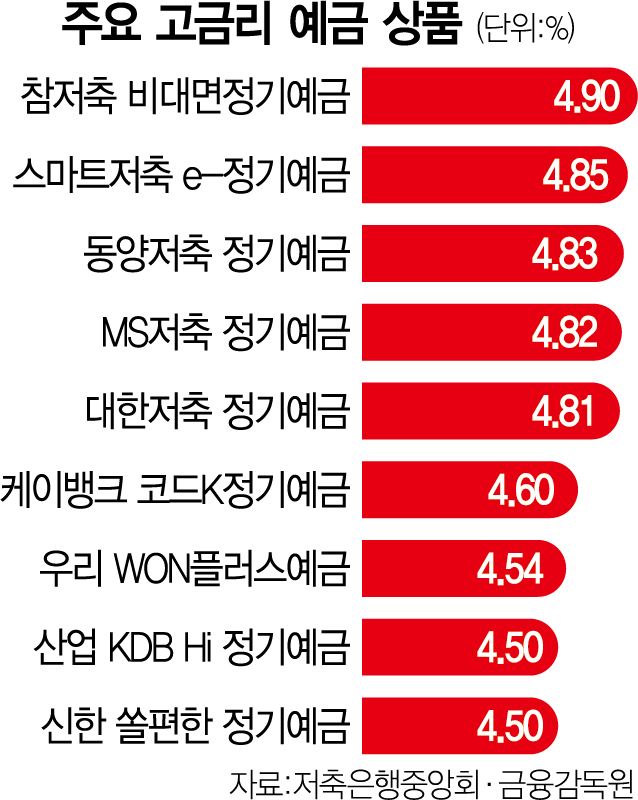
When overall market interest rates are rising, locking your money away for a long period of more than one year is not necessarily the best choice. If a new product offering much more attractive interest rates is released a few months later, you may find it regrettable to break your already committed long-term product. If you withdraw early, the interest you have diligently accumulated will be significantly reduced, forcing you to endure the full term reluctantly. Therefore, when interest rates are on an upward trend, it is much wiser to use short-term savings products with 3-month or 6-month terms to handle the situation flexibly. This involves saving a lump sum over a short period and then checking the market situation each time the term matures to switch to a place offering higher interest rates. This approach prevents your funds from being tied up for a long time and secures the flexibility to fully enjoy the benefits of rising market interest rates. Reading the flow of market interest rate fluctuations may seem complex, but it is a part that can be sufficiently sensed in our daily lives with a little attention. When prices rise and loan interest rates start to move, the deposit and savings market is bound to follow an upward trend. Rather than forcing yourself into long-term products and missing opportunities during this period, you need the wisdom to diversify your portfolio with a focus on short-term products. If you divide your monthly surplus funds into several short-term accounts, you can flexibly respond to sudden needs for funds. Instead of blindly choosing a long maturity just because a bank branch employee told you to, try practicing breaking down your cycle to match your own fund management plan.
When interest rates are rising, it is advantageous to adopt a strategy of flexibly switching to short-term savings with 3-month or 6-month terms instead of 1-year long-term products.
4. Differences Between Deposits and Savings and the Correct Way to Compare Interest Rates
One of the most common mistakes made by young people entering the workforce who are looking into bank products for the first time is simply comparing deposit interest rates and savings interest rates one-to-one. If you already have a lump sum of tens of millions of won, a fixed deposit is advantageous, but when saving a fixed amount from your monthly salary, a savings account is the answer. This is because a fixed deposit accrues the agreed interest on the entire principal deposited at the beginning until maturity, whereas a savings account has different deposit periods for each monthly contribution. For example, a 4% per annum deposit and a 4% per annum savings account will inevitably result in a huge difference in the actual interest amount accumulated in your account. This is because in a savings account, interest is applied for 12 months only to the money deposited in the first month, while the money deposited in the last month only accrues one month’s worth of interest. Therefore, you must accurately recognize that investing a lump sum and saving monthly are fundamentally different in purpose and calculation method before making comparisons. When browsing financial company websites or comparison apps, deposit rates may appear high while savings rates appear relatively low, which can be confusing. However, this is a natural result of the difference in calculation methods, so you should be careful not to confuse the nature of the two products and make the wrong choice. If you have already gathered seed money, you should use deposit products to steadily earn interest, and if you are saving a fixed amount from your monthly income, you should use savings accounts. The reason why people sometimes get confused after signing up for a high-interest savings account and seeing the actual amount received is precisely because they missed this calculation method. Once you understand the basic structure of financial products, your eyes will be much sharper when looking at bank interest rate comparison tables, and you will be able to easily spot the best products for you.
You should choose deposits for investing existing lump sums and savings for monthly saving, keeping in mind that the interest calculation methods for these two products are completely different.
5. Tips for Easily and Quickly Finding Mobile Special Savings Products
These days, it is an era where you can sign up for special savings products with just a few taps on a smartphone app without visiting a bank branch in person. Mobile-only products often have slightly higher interest rates than products at general branch counters because they can save on branch operating costs. In particular, various financial institutions, including the National Agricultural Cooperative Federation, provide services that allow you to compare interest rates by regional cooperative and sign up immediately through their mobile apps. In the case of regional agricultural and livestock cooperatives, the applicable interest rate can vary slightly between the head office and branches, so if you look carefully, you can find hidden gems. Since mobile special products have short sales periods and sales stop immediately once the designated quantity is sold out, speed is of the essence. You need to be diligent by setting notifications for the mobile apps of banks you are interested in and immediately proceeding with the sign-up process when you hear news of a special product release. The fact that you can easily open an account with your smartphone while lying on the sofa at home, without needing to stand in line at a branch, is one of the greatest blessings of the digital finance era. However, when proceeding with non-face-to-face sign-up, you should check detailed requirements such as identity verification procedures and conditions for lifting account limits in advance to avoid any issues. Occasionally, submitting a sign-up application does not immediately confirm account opening, as there may be a qualification review process. Therefore, it is safer to prepare the necessary documents or authentication means in advance with some leeway, rather than trying to connect just in time before the special product deadline. Even if your parents are not familiar with the mobile environment, anyone can easily become the beneficiary of a high-interest special product with a little practice with the help of their children.
By using mobile apps instead of visiting branches, you can compare regional interest rates and quickly sign up for limited-sale special savings products.
6. The Right Attitude for a Successful Saving Life
The future financial environment will change from moment to moment, and interest rates are expected to continue rising and falling in line with economic conditions. In such uncertain times, it is wise to diversify across multiple accounts to reduce risk rather than putting all your funds into a single product. Maintaining the habit of saving consistently every month while cultivating the eye to closely observe market interest rate trends is the shortcut to becoming wealthy. Rather than being swayed by hearsay that others say is good, you must create a savings portfolio that perfectly matches your income level and spending plans. We hope you will actively practice the methods of comparing base and preferential rates, the strategy of utilizing short-term savings, and the tips for finding mobile special products that you have learned today. Why not start wise asset management right now by turning on your smartphone and checking the current interest rates of the bank you use? Small practices will accumulate to become a solid lump sum that fills your account in the future. In the changing economic flow, protecting and growing our precious assets ultimately depends on constant interest and information literacy. If you pay attention to the various changes in the financial market and move one step faster than others, you will certainly be able to secure more interest than others. Saving is not just a battle of numbers but a enjoyable journey to prepare for your future, so it is important to continue steadily without rushing. We hope you will widely share the useful information you learned today with your family and friends so that you can all enjoy wise financial lives together. We will continue to share various stories based on substantial and practical financial information to help fill your wallets. Since a little interest can bring in big money, let’s re-examine our saving habits and start fresh from today.
In an uncertain financial environment, anyone can successfully save a lump sum by maintaining constant interest and a diversified saving strategy.
Frequently Asked Questions
=