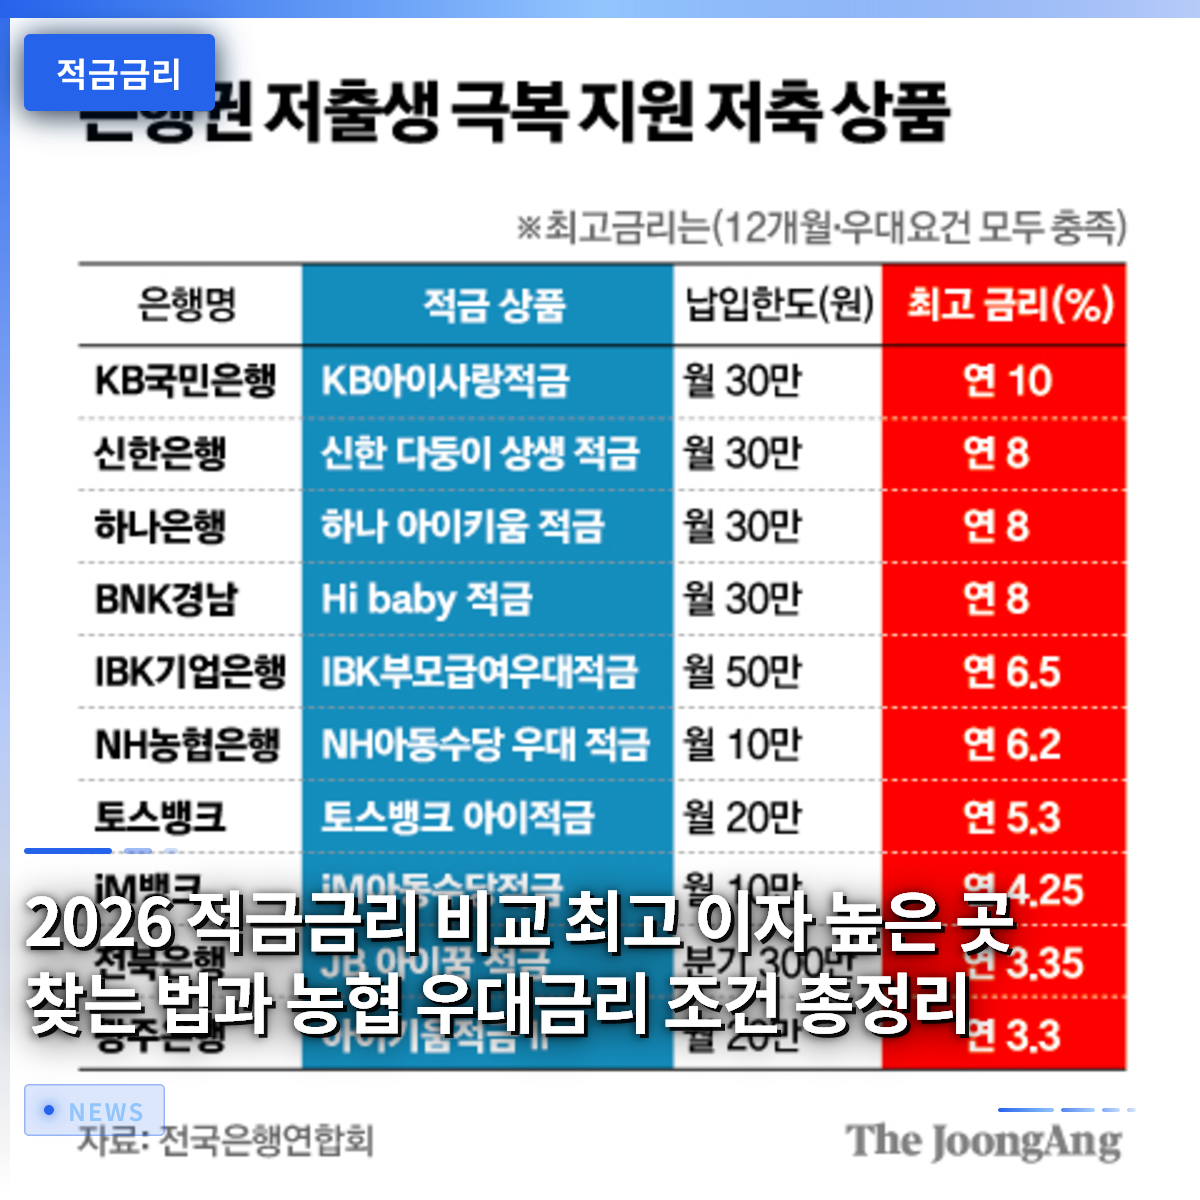
Looking at the current trends in savings interest rates at commercial banks in 2026, there is intense competition to offer even slightly higher returns. The era of simply depositing money at any bank is over; you must carefully scrutinize the conditions to secure significantly higher interest than others. Mr. Kim, an office worker whose savings account recently reached maturity, has noticed a slight increase in interest compared to the past and is now searching for new products. In fact, special promotional products that offer exceptional interest rates in exchange for daily life practices, such as walking or quitting smoking, are gaining immense popularity. This article examines the most advantageous financial products for building your initial capital at this point in time and provides specific tips on finding the highest interest rates. We will walk through methods to grow your money safely and effectively in a complex financial market.
=
2026 Savings Interest Rate Comparison: How to Find the Highest Rates and a Complete Guide to Nonghyup Preferential Rate Conditions
1. The Opportunity for Up to 6% Annual Interest: Nonghyup Health Promotion Special Savings
One of the most talked-about products in the financial sector recently is the NH Savings Bank “Correct Earth” regular savings account. Due to overwhelming customer response, this product has been relaunch with an exceptional interest rate condition of up to 6% per annum. It is not just about depositing money; it offers preferential interest rates if you commit to maintaining your health or living an eco-friendly lifestyle in your daily routine. Simply practicing quitting smoking and consistently verifying your walking exercise can significantly increase your interest benefits, attracting many people. When it was previously launched, the limited quantity sold out quickly, leaving many interested applicants disappointed. Since this launch is also limited in quantity, you risk missing out on a good opportunity if you don’t act quickly. Financial products that allow you to build assets while maintaining your health are expected to become more common in the future. For office workers who enjoy regular walking, this is a perfect fit. In fact, among subscribers, there are many favorable reviews describing it as a “two-for-one” experience where they exercise and save money simultaneously. The ease of verifying these practices through banking apps has also sparked a very enthusiastic response among younger demographics.
NH Savings Bank’s regular savings account, which combines daily health management with environmental pledges, is gaining significant popularity by offering interest rates of up to 6% per annum.
2. High-Interest Products for Children and Managing Holiday Allowances
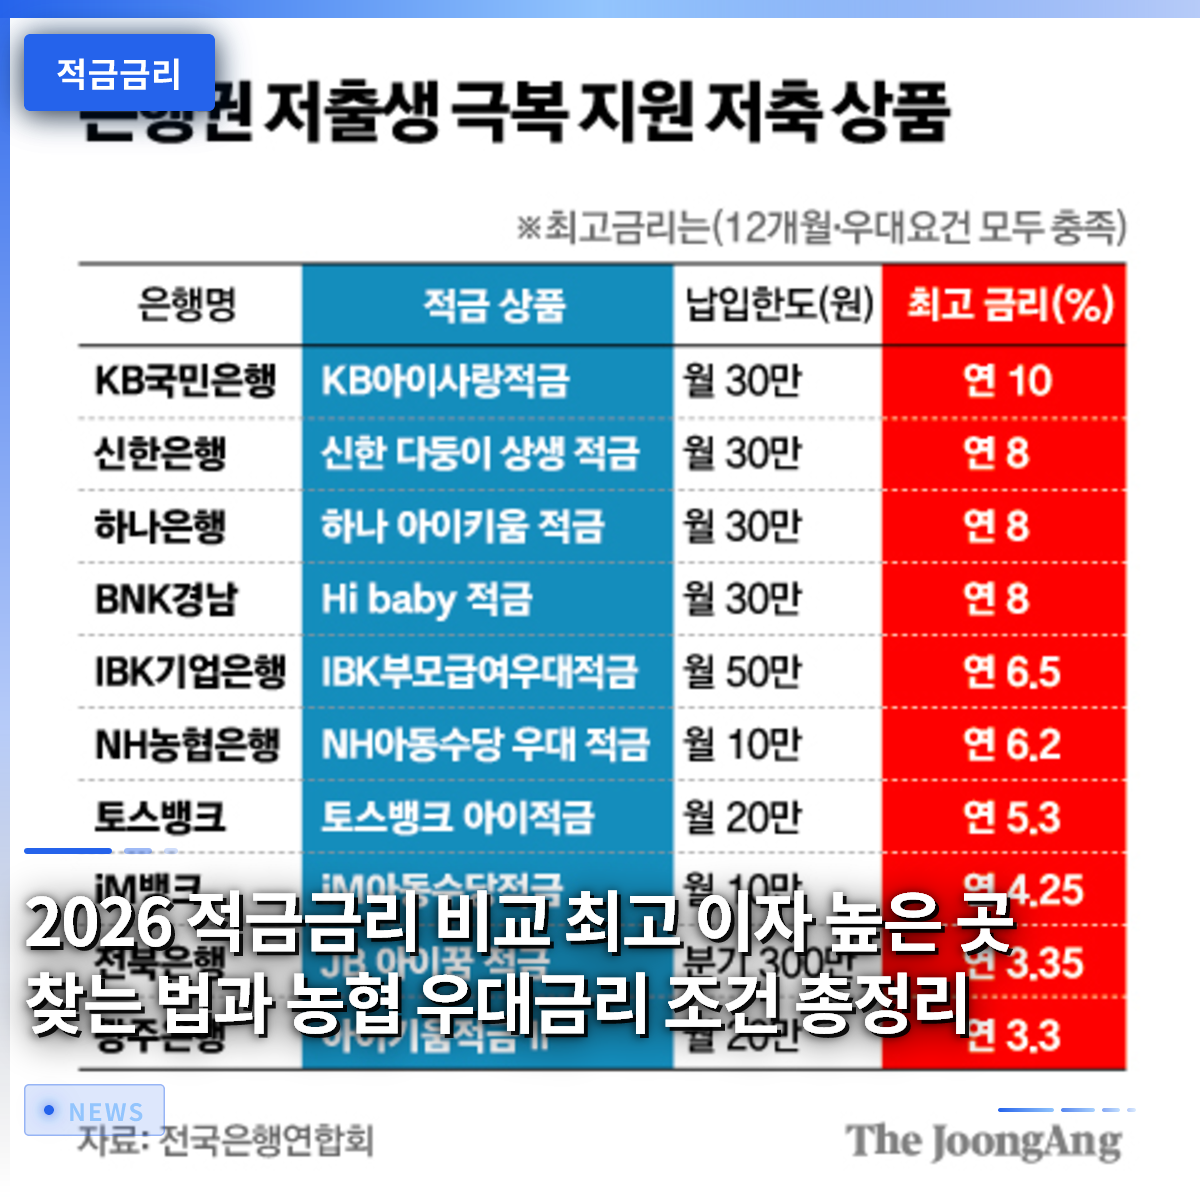
Among parents, high-interest products that can be opened in their children’s names and wealth management strategies for allowances are major topics of interest. Parents who aim to consistently save a surplus of 200,000 to 300,000 KRW per month are closely watching children’s exclusive products from major commercial banks. Representative products, such as Hana Bank’s “Dreaming Piggy Bank,” help cultivate children’s saving habits within the maximum monthly deposit limit. A significant advantage is that you can deposit holiday or birthday allowances directly into the account and enjoy the benefits of compound interest. It yields a two-for-one effect by teaching children the joy of saving from a young age and naturally instilling economic concepts. Many parents share stories of being deeply moved when the small amounts of allowance they steadily deposited into their children’s accounts eventually grew into a substantial sum. Children’s savings accounts at commercial banks often offer preferential interest rates compared to general products, so careful comparison is essential. You may receive additional interest depending on the subscription period or the setup of automatic transfers, so you should verify these details before visiting a bank branch. It is widely regarded as the ultimate first tool for economic education for your child’s future.
By utilizing commercial bank savings products in your child’s name, you can grow holiday allowances at high interest rates while naturally fostering your child’s saving habits.
3. Building a 3-Year Starter Capital for Young Adults: Youth Future Savings
The second recruitment schedule for the Youth Future Savings, a product designed to help new entrants to the workforce and young adults build solid assets, has finally been announced. This product allows you to receive substantial government contribution funds if you diligently save up to 500,000 KRW per month for three years. It boasts a perceived interest rate that is incomparable to general commercial products, making it a must-apply option for eligible individuals. With the added benefit of tax exemption, the scale of the starter capital you will hold in three years is larger than you might imagine. While saving a fixed amount monthly may seem burdensome at first, it can be viewed as the most certain investment for your future. Mr. Park, a young office worker nearby, signed up for this savings account immediately after joining his first job and has been steadily setting aside a portion of his salary each month. He says that although he initially hesitated because it felt like his money was tied up, he has come to enjoy watching the balance grow in his account over time. Given the enormous benefit of government contribution funds, this is an essential financial item that eligible young people should never miss. As the deadline approaches, applications may surge and cause server issues, so it is wise to prepare your documents in advance.
The Youth Future Savings, which involves deposits of up to 500,000 KRW per month for three years, offers young people the best opportunity for asset formation thanks to government contributions and tax exemption benefits.
4. Smart Deposit Strategies for Finding Higher Interest Rates
Although there are countless financial products in the market, finding the one that truly suits you with the highest interest rate is not as easy as it seems. Experts advise that rather than blindly chasing the highest rate, it is important to ensure flexibility according to the nature of your funds. For example, if you are certain you will need the money in one year, it is best to lock it in a regular savings account; if you are unsure when you will need it, you should utilize a parking account. Since each bank has strict hurdles, such as preferential conditions for primary customers or automatic transfer performance, you must scrutinize the details. Using internet comparison apps or financial portals allows you to check the most advantageous products for your conditions in just a few seconds. Mr. Lee, an office worker, has set up a system where his salary is automatically distributed across multiple accounts on payday to strictly control his spending. The secret to breaking the habit of indiscriminate consumption and increasing your savings rate is to meticulously manage your savings maturity dates. He continues a smart financial life by sharing information about high-interest products with colleagues, helping each other secure greater benefits. Everyone can agree that small differences accumulate to create a significant asset gap over several years.
To secure maximum interest, you should appropriately allocate funds between savings accounts and parking accounts based on usage and duration, and carefully review primary customer conditions.
5. Key Precautions When Signing Up for Nonghyup Special Products
When signing up for Nonghyup deposit and savings products, there are often cases where people suffer losses by rushing to sign up solely based on high interest rates. Since Nonghyup consists of different legal entities for local agricultural cooperatives and the central association, the interest rates and preferential conditions applied can vary by branch. It is necessary to accurately verify whether the product you are interested in is based on headquarters standards or specific local cooperative standards. Additionally, there are significant differences in tax benefits, such as tax-exempt savings, depending on whether you are a member. Even when signing up easily and non-face-to-face through mobile apps, you should not skim over these detailed terms; you must read them carefully. In communities sharing information about Nonghyup regular savings special promotions, there is active exchange of information on which branches offer the highest rates. By putting in a little effort or obtaining the latest information online, you can seize the luck of securing an interest rate more than 1% higher than others. You must firmly resolve not to cancel midway, as you can only receive the promised maximum interest if you make deposits diligently every month during the subscription period. It is also a very wise method to check in advance whether partial withdrawal is possible in case you suddenly need a large sum of money.
Nonghyup special products may have different rates and conditions depending on the branch, so you must carefully verify member tax-exempt benefits and other details to avoid losses.
6. 2026 Second Half Savings Interest Rate Outlook and Our Approach
The future financial market is highly likely to see slight fluctuations in savings interest rates due to changes in the domestic and international economic environment. Banks’ deposit product interest rate strategies change frequently depending on the movement of US Treasury yields and domestic inflation rates. In times like these, it is most important to maintain a steady attitude by setting a clear savings plan and consistently saving money without being shaken. Whether interest rates are high or low, the habit of building starter capital serves as a sturdy pillar supporting our lives. Rather than being swayed by flashy investment rumors around us, we should rediscover the value of savings accounts that offer safe and certain interest. Why not check your account balance today and look for the best special promotional product you can sign up for immediately? Even small amounts, if saved consistently every month, will eventually lead to the joy of receiving a substantial maturity interest statement after a year. Taking that small step to knock on the bank’s door will be the definitive key to making your future more abundant and stable. We will continue to help you manage your assets confidently, providing more useful financial information and solid wealth management know-how.
During periods of high interest rate volatility, the key is to maintain an unshakable saving habit and find and execute the optimal product suited to your needs.
Frequently Asked Questions
=