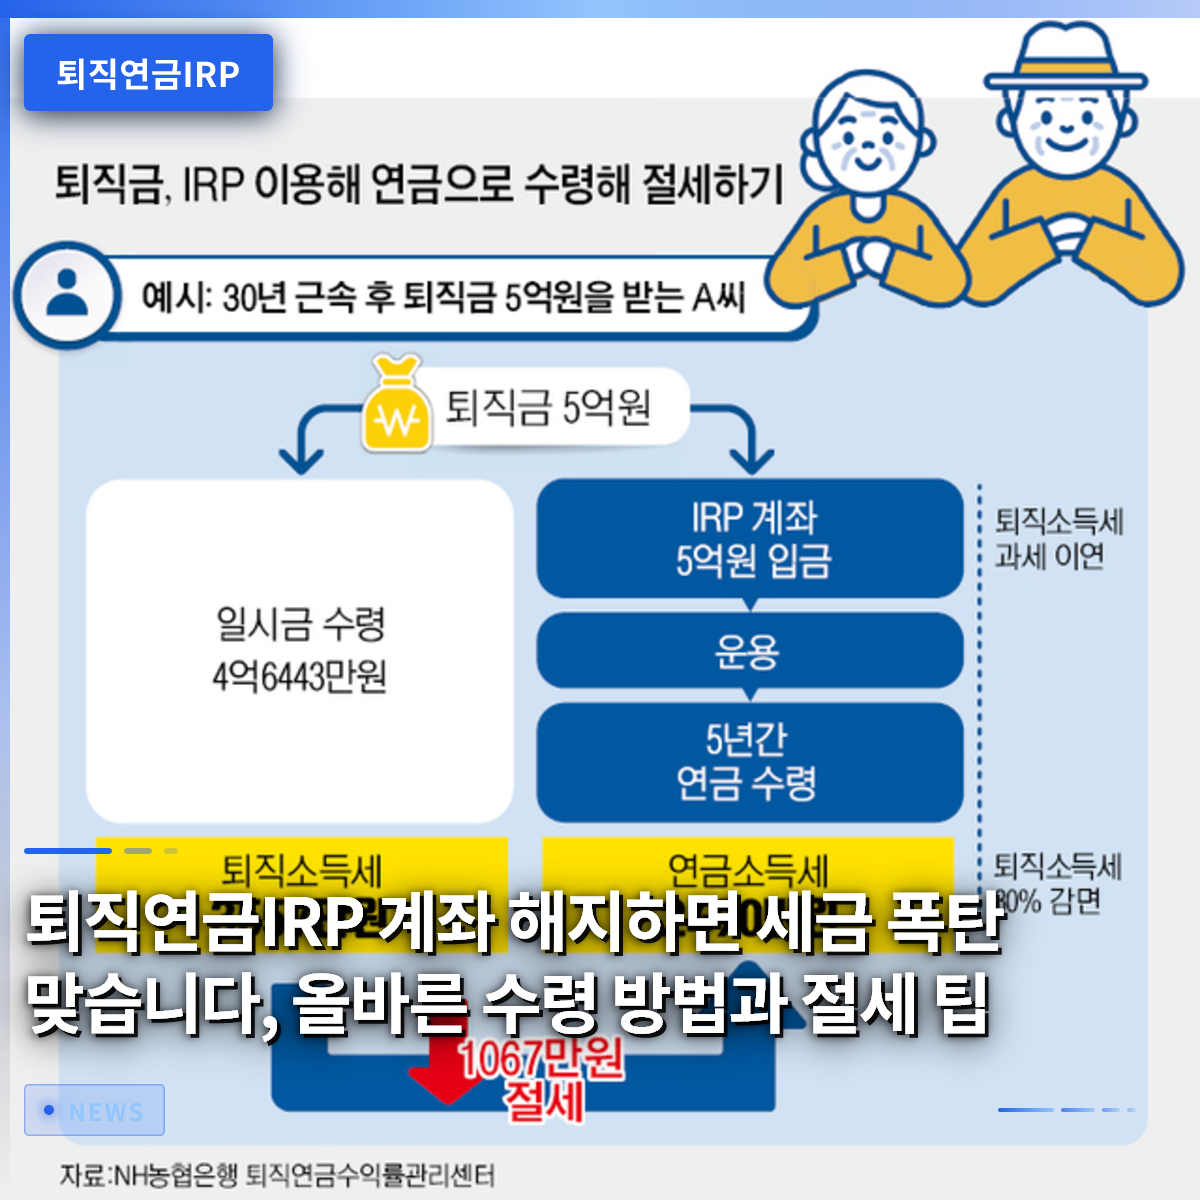
If you do not properly manage your Retirement Pension IRP (Individual Retirement Pension) account, you may end up paying a lump sum tax of several million won. Therefore, if you are planning to change jobs or retire, it is essential to understand the specific characteristics of your account. It is common to see people who, upon changing jobs, withdraw their severance pay to cover immediate cash needs and spend it right away or close their accounts. However, it is easy to overlook the fact that statistics show a significant amount of funds are being withdrawn prematurely, resulting in substantial tax losses. In fact, over the past few years, a considerable portion of funds transferred to personal retirement pension accounts has been withdrawn, leading to regrettable situations where subscribers have lost valuable tax benefits. In this article, we will thoroughly explain everything from the correct methods for receiving retirement pension funds to practical tips for saving on taxes, making it easy for anyone to understand. Instead of using complex financial jargon, we will explain things based on everyday examples, so please read through carefully to the end.
=
Closing Your Retirement Pension IRP Account Triggers a Tax Bomb: Correct Withdrawal Methods and Tax-Saving Tips
1. What is a Retirement Pension IRP Account?

A Retirement Pension IRP refers to a personal retirement pension account where employees can pool their valuable severance pay received upon changing jobs or retiring, and either manage it themselves or utilize it as retirement funds later on. In the past, it was common for people to receive their severance pay directly into a regular bank account upon leaving a company and use it for living expenses. However, the system has changed, and if certain conditions are met, the severance pay must be transferred to this account. The eligibility has been broadened to include not only office workers but also self-employed individuals and delivery workers who need to prepare for their own retirement. This account is not merely a savings account for storing money; it is a space for growing assets by investing in various financial products such as stocks, bonds, and funds. In particular, contributions made by individuals are eligible for tax deductions during the year-end tax settlement, making it an essential tax-saving tool among office workers.
Many people make the mistake of not opening this account or closing it immediately after opening it simply because they find it troublesome when leaving a company. However, the true value of this account is only realized when it is received in the form of a pension that generates a stable monthly cash flow after retirement. It plays the role of a lubricant that firmly supports the middle stage of the retirement preparation pyramid, often referred to as the “three-tier structure,” and should never be taken lightly. If you close the account just because you think you need a lump sum of money right now, you may find yourself with significantly insufficient funds in hand when you truly need them at retirement. Therefore, when changing or leaving a job, you must start by safely transferring your existing severance pay to this account.
The Retirement Pension IRP is an essential account for pooling severance pay, managing it for retirement, and enjoying tax benefits.
2. Why You Must Always Deposit Severance Pay into an IRP Account

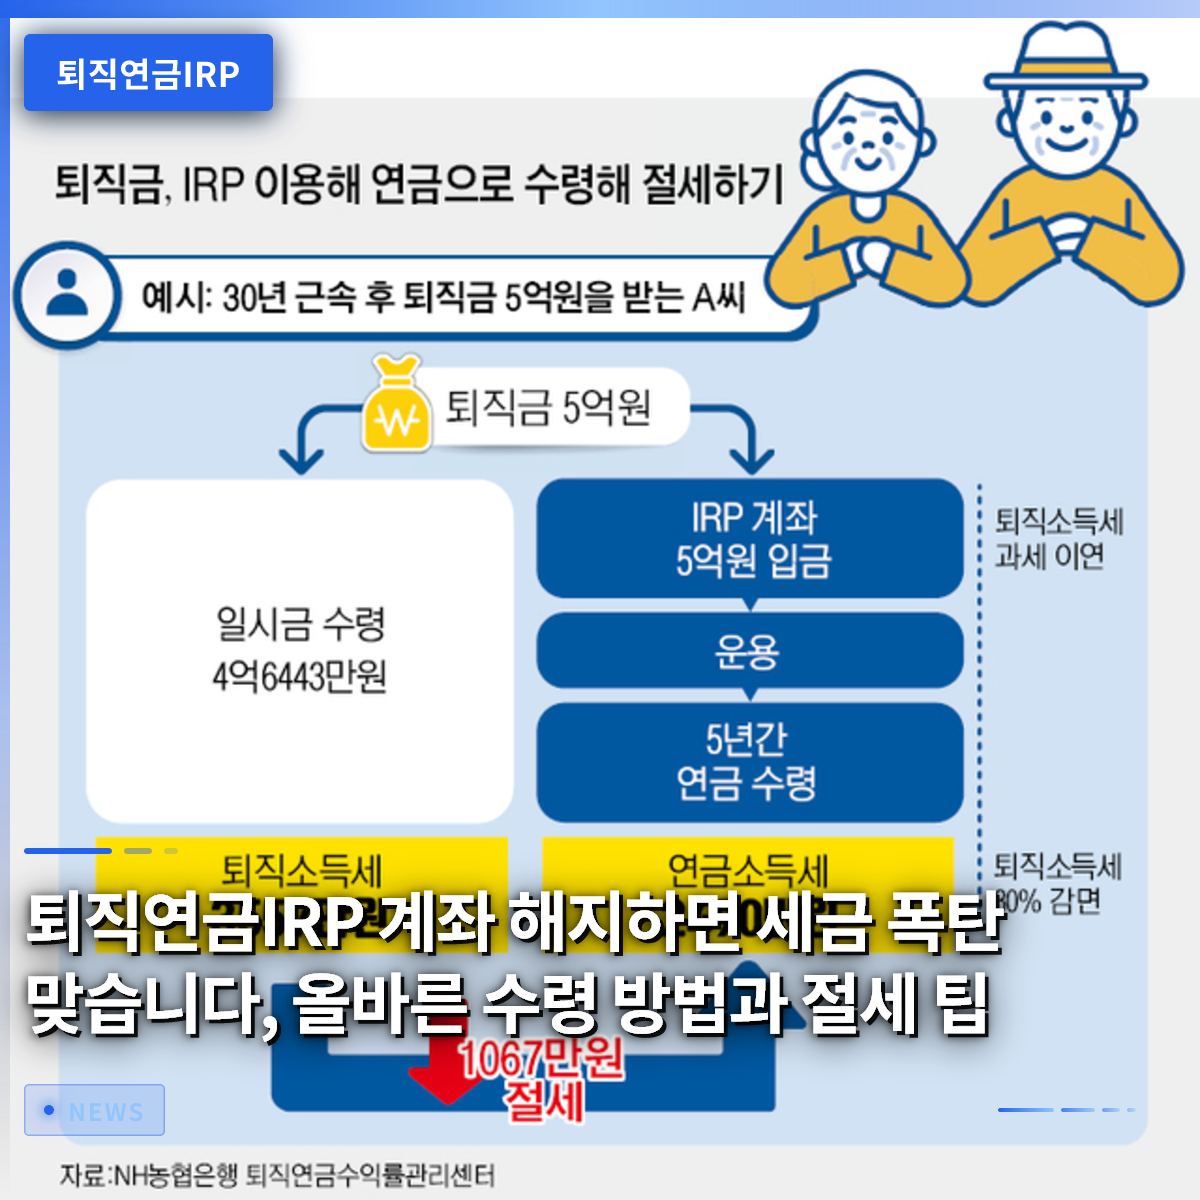
The reason why severance pay incurred when leaving a company must be received in a Retirement Pension IRP account rather than a regular account is due to the substantial tax reduction benefits. If you receive your severance pay directly into a regular bank account, the government treats it as retirement income and immediately deducts taxes at the high rates prescribed by law. However, if you transfer this money directly to an IRP account, you can defer paying taxes immediately; this is known as the tax-deferral effect. Since the money that would have gone to taxes remains in the account, it can continue to grow through the power of compound interest, leading to a significant difference in the final asset size.
In fact, Mr. Kim, an office worker, recently transferred his severance pay from a job change directly to his IRP account, saving several million won in taxes immediately. If he had received only the remaining amount after all taxes were deducted, the investment funds available for his new challenges would have been reduced accordingly. Later, if he receives this money in pension form after retirement, it will be subject to a much lower tax rate than the original retirement income tax rate, drastically reducing the tax burden. The government has provided these strong tax incentives to encourage pension withdrawals to help citizens secure a stable retirement life. Therefore, if you have severance pay, it is a wise choice to abandon the idea of withdrawing it as cash and instead safely transfer it to the account.
Receiving severance pay in an IRP allows you to save on taxes through the tax-deferral effect and grow your assets more significantly.
3. The Fearsome Tax Bomb You Face When Closing Early

If you close your Retirement Pension IRP account midway due to an urgent need for a lump sum of money, you will face the terrifying situation of having to return all the tax benefits you have received. The moment you break the account, the government not only recoups all the taxes that were previously spared but also forcibly deducts taxes at a high rate under the name of miscellaneous income tax. It is inevitable to feel frustrated and overwhelmed when you witness your valuable severance pay principal, accumulated through hard work, shrinking due to taxes. In reality, over the past few years, numerous subscribers have experienced the pain of a significant portion of their cumulative funds disappearing into thin air after depositing money into these accounts and then closing them due to personal circumstances.
You often see people around you closing these accounts under the pretext of needing to increase their jeonse (deposit) or facing sudden large medical bills. However, if you fall under the unavoidable circumstances defined by law, there are ways to withdraw money midway without closing the account, so you must absolutely avoid recklessly breaking the account. You should carefully review the exception clauses, such as purchasing your own home or securing a jeonse deposit as a non-homeowner, or receiving long-term care treatment for six months or more for yourself or a family member. If you close the account due to a simple change of heart or impulsive spending rather than these exceptional situations, the tower of your retirement preparation that you have built up will collapse in an instant. Trying to escape an immediate crisis can lead to a massive disaster in your retirement, so early closure is an action that must be avoided at all costs.
Closing an IRP account early triggers a tax bomb and significantly damages retirement funds, so it should be avoided.
4. Asset Management Strategies Utilizing Robo-Advisors and Artificial Intelligence
For subscribers who are unsure which financial products to invest in after opening a Retirement Pension IRP account, artificial intelligence technology is now being actively introduced. Financial companies are operating services that carefully analyze each subscriber’s investment goals, tendencies, and remaining time until retirement to propose optimal asset allocation portfolios. By leveraging AI algorithms and massive big data, returns can be managed more objectively and stably than if a person were to analyze the market directly. In fact, variable funds and pension products that have adopted this latest technology are recording excellent performance by undergoing a rebalancing process that automatically adjusts the portfolio according to market conditions.
It is practically impossible for general investors to monitor the constantly changing stock market trends daily and directly select and trade stocks. However, by utilizing AI-based automated management services, you can effectively reduce the extent of losses through mechanical responses even when the market suddenly crashes or fluctuates. Statistically, pension-type products tend to significantly lower the maximum loss rate compared to general investment products while still delivering stable long-term performance. This means you can enjoy expert-level asset management for free or at a low cost without having to worry about investments in your busy daily life. Therefore, do not leave your account unattended; actively utilize these advanced management systems to strengthen the health of your assets.
Utilizing AI-based asset management services allows you to expect stable returns without complex worries.
5. Maximizing Tax Deduction Limits and How to Receive Monthly Retirement Income
The Retirement Pension IRP account is not just a place to store the severance pay provided by your company; it is also widely used for individuals to make additional cash contributions to maximize tax deduction benefits. You can receive tax deductions at a certain rate on the amount deposited annually when combining pension savings accounts and IRP accounts, which is why it is called a mandatory course for office workers’ year-end tax settlement. If you fill up the limit, the refund amount returned to your account at year-end is substantial, so it is known as a treasure-like tax-saving account among office workers. The assets accumulated in this way transform into a reliable pension that generates a steady monthly cash flow when the time for retirement arrives.
After retirement, the National Pension alone is insufficient to cover monthly living expenses, making this personal pension asset the key to determining the quality of your retirement life. You must complete a structure where the National Pension (the first floor) provides the basic defense, the corporate pension (the second floor) acts as the middle lubricant, and the IRP and pension savings (the third floor) supplement the insufficient living expenses. Once you create a monthly cash flow that hits your account like rent, you can enjoy a comfortable life without economic worries even after retirement. Depositing a little spare cash into this account now is the most certain and reliable way to repay your future self. If you carefully calculate the limits and develop the habit of making consistent annual contributions, you will be able to enjoy your retirement with a smile and leisure.
Filling the annual tax deduction limit allows you to save on taxes while securing a reliable cash flow after retirement.
6. The Future of Wise Pension Management for a Successful Retirement
The Retirement Pension IRP account has now become a core infrastructure that determines the successful retirement of office workers in South Korea, going beyond being a mere storage account for severance pay. In the future, as the financial market changes, more diverse investment tools and convenient asset management features will be added, further broadening the choices for subscribers. The government and financial institutions are also preparing various institutional supplements to ensure that citizens can easily maintain their retirement funds without closing them early. No matter how fast the world changes or how unstable the economic situation becomes, having just one systematically managed pension account provides a sturdy support pillar.
Even now, many people are repeating the mistake of breaking or neglecting their valuable pension accounts, swayed by immediate temptations. However, starting today, you should carefully check where your retirement pension account is invested and absolutely avoid unnecessary closures. You need the wisdom to consistently manage your assets with the help of expert advice or AI systems and to fully take advantage of tax deduction benefits. Life after retirement is inevitably transformed 180 degrees depending on how you prepared your pension with the right mindset in your younger days. Do not delay any longer; check the status of your IRP account right today and take a wise first step toward your future.
Maintaining and systematically managing your Retirement Pension IRP account until the end is the only shortcut to a successful retirement.
Frequently Asked Questions
=