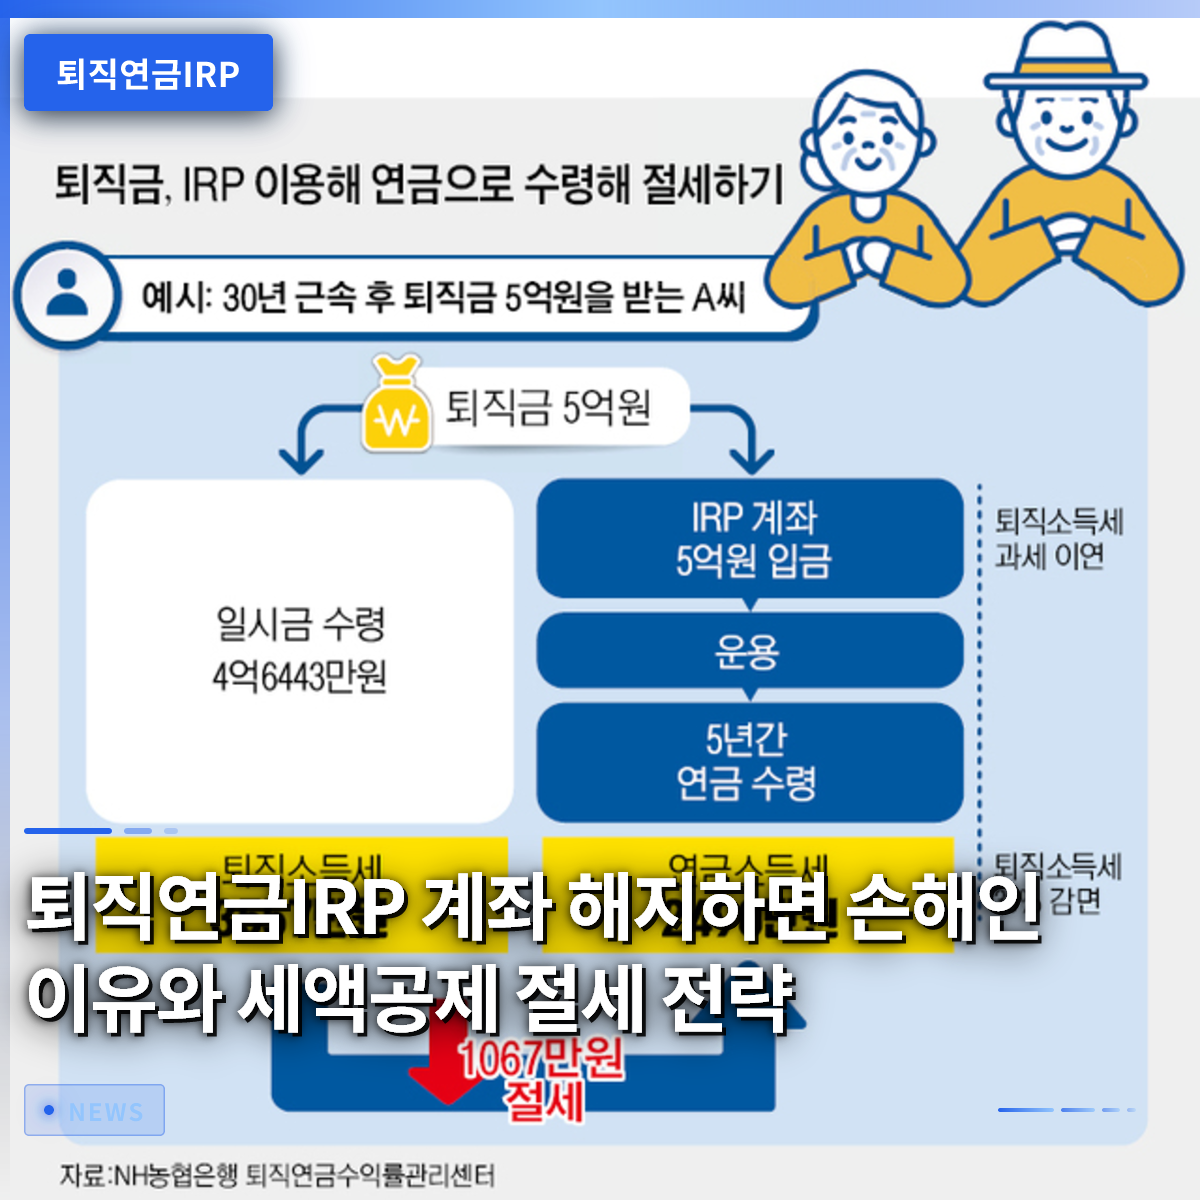
The Individual Retirement Pension (IRP) account is an essential financial product that must be utilized to save on taxes and accumulate retirement funds during your working life. Many people immediately close their accounts when they receive a lump sum upon changing jobs or retiring, which is a shortcut to facing a tax bomb and losing valuable retirement assets. In fact, statistics from recent years prove this, showing that a significant portion of funds transferred to IRP accounts has been lost due to early termination. Mr. Kim, an office worker, regretted it after receiving a massive tax notice; he had received his severance pay directly into his checking account three years ago when he changed jobs and spent it all. In this article, we will carefully examine why you should keep your IRP account until the end and how to grow your savings while saving on taxes.
=
Why Closing Your IRP Account Is a Bad Idea and Tax Deduction Strategies for Savings
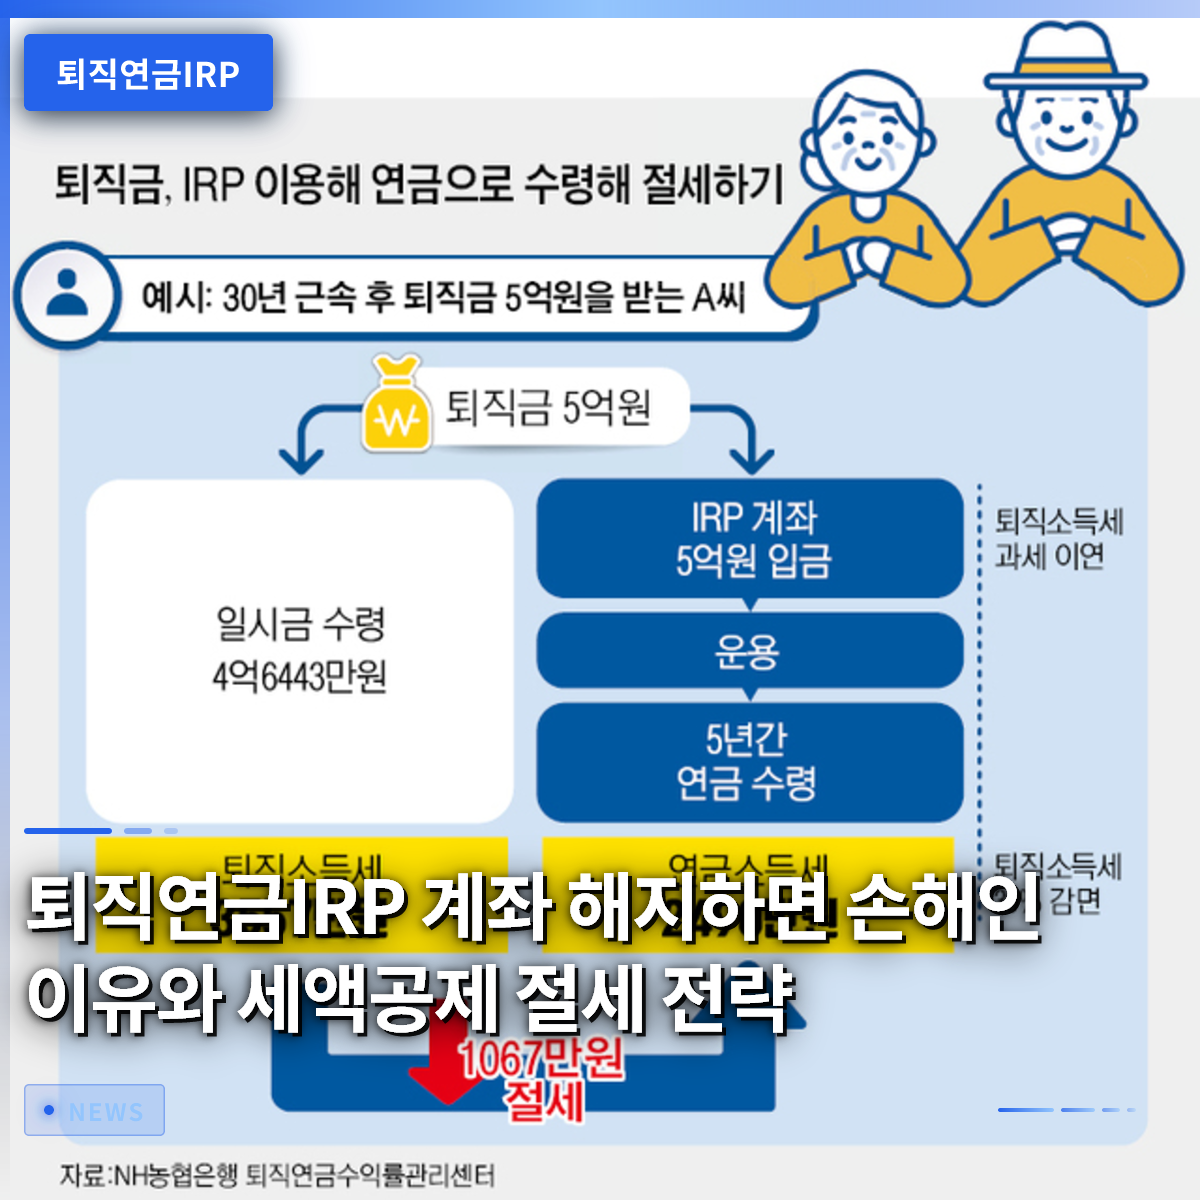
1. Why You Should Receive Your Severance Pay in an IRP

Severance pay incurred when leaving a job or changing employers must be transferred to an IRP account to fully enjoy tax exemption benefits. If you receive your severance pay directly into a regular checking account, you will have to pay the severance income tax withheld by your company, resulting in a significant loss. However, if you transfer the funds to an IRP account, you can defer paying taxes immediately and reduce the tax rate by up to 30 percent when receiving it as a pension later. If you fail to take advantage of these legal tax-saving benefits provided by the state, you are the only one who suffers the loss.
Mr. Park, who worked at a small and medium-sized enterprise in a regional area, transferred his severance pay to an IRP account when he changed jobs last year, allowing him to avoid paying several million won in taxes immediately. The money deposited in this account can significantly reduce the tax burden if received in installments as a pension upon reaching retirement age. You should be careful not to break the account midway just because you need a lump sum, as doing so requires you to pay all the deferred taxes at once. Therefore, when facing major life changes such as job changes or retirement, the first thing to do is open an IRP account at a bank or securities firm.
You should receive your severance pay in an IRP account instead of a regular checking account to defer taxes and lower the tax rate when receiving it as a pension later.
2. Reasons for High Cancellation Rates and Fatal Losses

Recent statistics show a regrettable phenomenon where a significant amount of money deposited into IRP accounts is terminated early. If you break the account because you urgently need cash, not only will the tax benefits accumulated so far be wasted, but you will also face heavy taxes under the name of miscellaneous income tax. Mr. Lee, an office worker, closed his IRP account, where he had been saving for retirement, to increase his deposit for a lease, only to suffer an unexpected tax shock and hold his head in despair. Since you have to return all the tax deduction benefits received during the year-end settlement, the actual amount of money you end up with is much less than you might think.
Retirement funds are assets that must be kept and viewed over a long period of ten or twenty years to truly exhibit compound interest effects. The moment you terminate it midway, all the financial advantages enjoyed up to that point disappear, leaving you with only losses. Governments and financial institutions have prepared various safety devices and alternatives to prevent such indiscriminate early termination, but a change in individual awareness is most important. When you need urgent cash, it is a much wiser choice to look into exceptional withdrawal conditions allowed by law or collateral loan systems rather than closing the entire account.
Closing your IRP account because you need urgent cash results in fatal losses, as you must return all tax deductions and deferred taxes.
3. Tax Deduction Limits and Additional Contribution Strategies

An IRP account is not just a place to store severance pay; it is also a powerful tax-saving tool that allows you to make additional contributions annually to get your taxes back. If you fill up to the maximum annual contribution limit combining your pension savings account and IRP, you can receive a substantial refund during the year-end tax settlement. Although the deduction rate varies depending on your salary level, simply making consistent annual contributions can yield significant wealth management benefits. Self-employed individuals and freelancers who do not receive separate severance pay from a company can also join this account directly to enjoy tax deduction benefits.
Mr. Choi, who has been interested in wealth management since his early career, has been receiving generous refunds every year-end settlement season thanks to depositing a fixed amount into his IRP account every month. The employer contributions made to the Defined Contribution (DC) pension by the company are separate from the individual’s contribution amount eligible for tax deductions, so it is important to distinguish this clearly. Remember that tax deduction benefits apply only to the amounts you directly deposit from your own account, so it is best to fill up to the limit. If you are the only one missing out on tax-saving benefits that everyone else is taking advantage of, it is no different from throwing money on the street every year.
Making additional contributions to your IRP account annually allows you to maximize tax deduction benefits during the year-end settlement.
4. Safe Asset Management and Utilizing Artificial Intelligence
If you open an IRP account and leave it untouched, the real value of your retirement assets may decrease as they fail to keep up with inflation. Recently, many financial institutions have been utilizing artificial intelligence algorithms and big data analysis technologies to propose asset allocation portfolios tailored to subscribers’ preferences. If you are unsure about which stocks or bonds to invest in, it is advantageous to actively utilize these automated asset management features. Actual statistics show that products using AI-based robo-advisor services have recorded more stable and superior performance compared to general management methods.
When the stock market fluctuates drastically, general investors are prone to making wrong decisions out of fear, but the system performs rebalancing operations calmly. Mr. Jung, who is close to retirement, almost incurred losses by picking stocks himself but is now safely diversifying and managing his assets through an AI portfolio service. If you put all your assets only in principal-guaranteed products, they will not grow in the era of ultra-low interest rates, so you must combine them with fund investments that match your appropriate risk tolerance. You should periodically review the various investment products and market trends provided by financial companies to maintain a healthy return rate on your account.
Utilizing AI asset allocation and rebalancing services allows you to expect stable returns without the complex worries of investing.
5. Creating a Monthly Cash Flow Like a Salary for Retirement
The biggest concern after retirement is the disappearance of fixed monthly income, and the key to solving this is receiving a pension. In the three-tier pension pyramid structure, while the National Pension builds the most basic defense line, the IRP plays the role of a reliable lubricant that fills the gap in living expenses. Instead of receiving your severance pay all at once and spending it, receiving it as a pension over 10 years or more significantly reduces the tax burden and allows you to use it like a salary for life. If couples manage their respective accounts well, they can create a stable cash flow after retirement that is no less enviable than during their working years.
Mr. Kang, who works at a retirees’ association, vowed to receive his funds as a pension in installments after seeing people around him squander their severance pay within a few years. He set up his IRP account to transfer a fixed amount to his checking account every month, which brought him peace of mind and completely eliminated his worries about retirement living expenses. In your younger days, you should focus on the fun of accumulating a lump sum, but at the point of retirement, how stable a cash flow you create determines the quality of the latter half of your life. Instead of being tempted by small amounts of money right in front of you and closing your account, you should imagine the joy of the pension hitting your account every month in the future.
Receiving assets from your IRP account in the form of a pension allows you to save on taxes while creating a stable cash flow for retirement.
6. Practical Strategies for a Successful Retirement
As we have seen so far, the IRP account is not just a savings account but the ultimate tax-saving weapon that every office worker in South Korea should take care of. Do not repeat the past mistake of carelessly closing your account every time you change jobs; instead, you should develop the habit of inheriting and maintaining your account until the end. You should make small additional contributions annually to secure tax deduction benefits and manage your return rate through AI-based asset allocation services. The person who can turn the vague fear of retirement into a concrete asset management plan is none other than yourself, who is reading this article.
Do not be swayed by wrong rumors around you; check the status of your pension account via an app today and inspect any deficiencies. You must never forget that small attention and practice can completely change the retirement landscape ten or twenty years from now. Starting today, begin wise asset management that reduces taxes and grows returns to meet a confident and comfortable retirement. The most certain investment for your future self begins with cherishing your IRP account right now.
Maintaining and actively managing your IRP account until the end is the only way to create a successful retirement.
Frequently Asked Questions
=